Blog

  • Thruvision Maintains £8 Million FY27 Revenue Guidance as Order Backlog Reaches £2.6 Million

    Thruvision Maintains £8 Million FY27 Revenue Guidance as Order Backlog Reaches £2.6 Million

    Thruvision Group (LSE:THRU) reported first-half revenue of £2.6 million for the 2027 financial year, unchanged from the comparable period and in line with expectations, while its order backlog increased to £2.6 million. The security technology company maintained its full-year revenue guidance of £8 million, supported by existing orders and contracts scheduled for delivery during the second half.

    The company reported that its partner network accounted for almost 60% of first-half sales, reflecting an increased contribution from its distribution channels. Thruvision has expanded its network of value-added resellers in the UK and Benelux region and recruited additional sales personnel in the United States and UK.

    During the period, Thruvision secured further retail distribution agreements in Europe and added its first Canadian government customer. The company also reported a contract valued at more than £3 million to deploy its security screening systems across multiple airports in South-East Asia, with deployment planned for the second half of FY27.

    The airport agreement represents a significant component of the company’s reported contract activity and contributes to its order pipeline for the remainder of the financial year.

    Thruvision identified public space protection and transport hub security as areas of increasing demand for its technology. The company said its contract activity and distribution network expansion have improved revenue visibility, with management maintaining its expectations for continued growth into FY28.

    The company’s full-year revenue forecast remains unchanged at £8 million, compared with the £2.6 million recorded in the first half.

    About Thruvision Group plc

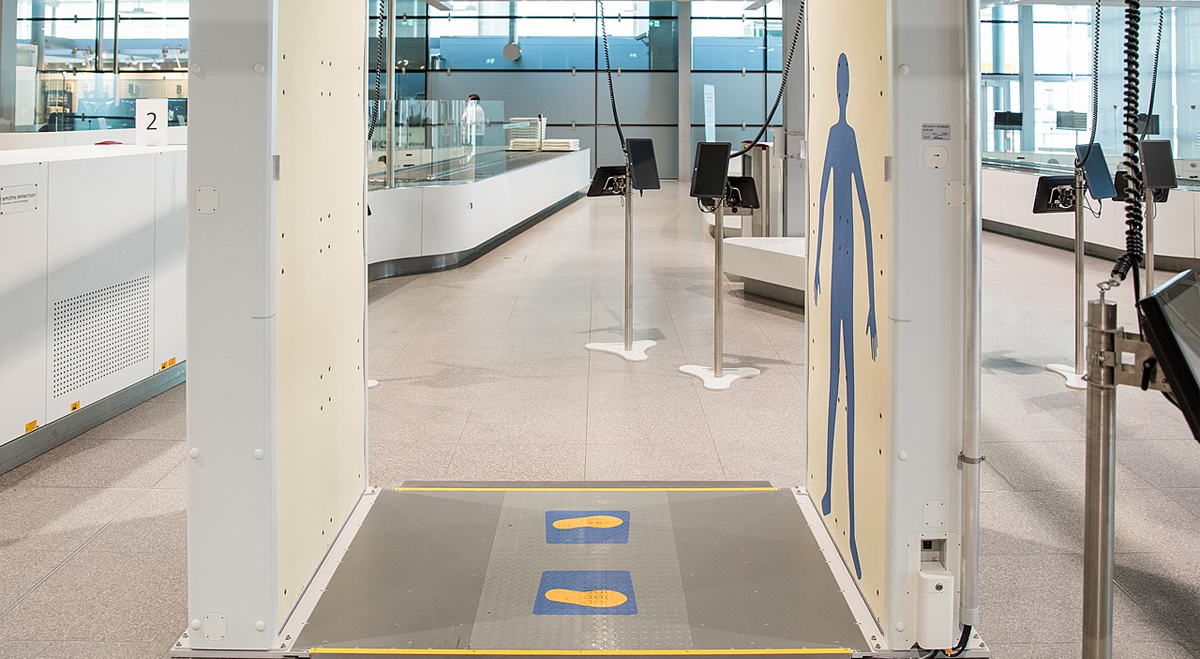
    Thruvision Group plc develops and manufactures walk-through security screening technology for government and commercial customers in more than 30 countries. Its AI-enabled systems are designed to detect concealed metallic and non-metallic objects in real time, including in locations with high pedestrian traffic. The company maintains offices and manufacturing operations in the UK and United States.

  • Citi Data Shows US Luxury Spending Declined 5% in Q3, Ending First-Half Growth

    Citi Data Shows US Luxury Spending Declined 5% in Q3, Ending First-Half Growth

    U.S. consumer spending on luxury brands declined 5% year over year in the third quarter of 2026, reversing the increases recorded during the first six months of the year, according to credit card data analysed by Citi.

    The bank reported a 6% annual decline in September, following reductions of 4% in July and August. September represented the largest monthly decrease of the quarter.

    The third-quarter contraction followed spending growth of 5% in the first quarter and 3% in the second, making it the first quarter of 2026 to record a year-over-year decline.

    Citi said the latest figures reflected a combination of continued geopolitical uncertainty and a more difficult comparison with spending levels a year earlier.

    The two-year stacked spending measure also declined, moving to negative 6% in September from negative 5% in August.

    Jewellery and Watches Record Larger Declines

    Spending trends varied across luxury product categories during September, according to Citi’s transaction analysis.

    Leather goods and ready-to-wear apparel showed sequential improvements, while jewellery and watch purchases declined more substantially.

    The bank noted that comparisons with tariff-related purchases made a year earlier contributed to the reduction in jewellery and watch spending.

    Average spending per transaction decreased by a low-single-digit percentage on an annual basis.

    The number of customers making purchases also remained below the previous year’s level, falling 5%, although the customer growth measure improved compared with earlier readings.

    These figures indicate that both transaction values and customer activity contributed to the annual reduction in spending during September.

    Consumer Surveys Point to Softer Sentiment

    Citi’s findings coincided with weaker consumer confidence readings in the United States.

    September surveys conducted by the Conference Board and the University of Michigan indicated less favourable views of business conditions and employment prospects, alongside continuing concerns about inflation.

    The bank said the latest transaction figures and commentary from luxury businesses suggest that U.S. spending patterns may be returning towards more normalised levels.

    However, Citi expects consumers in higher-income groups to remain comparatively resilient, with gains in equity market wealth continuing to support their financial position.

    The bank’s observations come ahead of the next round of corporate earnings announcements, when luxury companies are expected to provide updated information on regional demand.

    Citi Identifies Luxury Groups With Greater US Market Exposure

    Citi highlighted differences in the extent to which publicly traded luxury companies depend on U.S. consumers.

    Tapestry (NYSE:TPR), Capri Holdings (NYSE:CPRI), Watches of Switzerland (LSE:WOSG), Birkenstock (NYSE:BIRK) and EssilorLuxottica (EU:EL) were identified among the companies with the greatest U.S. exposure.

    Companies with comparatively lower exposure included Moncler (BIT:MONC), Prada Group (USOTC:PRDSY), Swatch Group (USOTC:SWGNF), Hermes (LSE:RMS) and Burberry (LSE:BRBY).

    The geographic distribution of sales provides context for assessing how changes in U.S. luxury spending may affect individual companies.

    Citi’s analysis uses selected credit card transaction records from a panel exceeding 10 million U.S. cardholders, meaning the results reflect the spending patterns of that sample rather than the entire luxury market.

    The findings show that U.S. luxury spending moved into negative annual growth during the third quarter, with differences across product categories and customer spending measures ahead of the upcoming earnings season.

  • AI and Technology Expected to Drive Two-Thirds of S&P 500 Earnings Growth in Q3

    AI and Technology Expected to Drive Two-Thirds of S&P 500 Earnings Growth in Q3

    Artificial intelligence-related companies are expected to account for much of the anticipated increase in U.S. corporate earnings during the third quarter of 2026, with analysts forecasting overall S&P 500 profit growth of approximately 31% compared with a year earlier.

    According to LSEG earnings and equity research head Tajinder Dhillon, around two-thirds of the projected increase is expected to come from the technology sector and AI-related companies, including Alphabet (NASDAQ:GOOG), Amazon.com (NASDAQ:AMZN) and Meta Platforms (NASDAQ:META).

    The earnings outlook follows a period of gains in technology shares that helped lift the S&P 500 to a record high this week.

    Investors are preparing for the quarterly reporting season, which is expected to begin next week with financial results from JPMorgan Chase (NYSE:JPM), Goldman Sachs (NYSE:GS) and other major banks.

    Sector Forecasts Show Differences in Earnings Growth

    Technology and AI-related businesses are expected to account for the largest share of third-quarter earnings expansion, although energy companies are also forecast to report substantial increases.

    Wells Fargo Investment Institute’s Sameer Samana estimates that technology and AI could contribute between 70% and 80% of overall earnings growth.

    Energy sector profits are projected to increase approximately 115% year over year, following a roughly 30% rise in U.S. oil prices during the third quarter amid the ongoing U.S.-Israeli war with Iran.

    Other sectors are expected to report considerably lower growth rates. Consumer staples and real estate are among the industries with the smallest projected increases in earnings compared with the same period last year.

    The sector forecasts suggest that aggregate S&P 500 earnings growth will depend heavily on the performance of companies associated with AI investment and energy markets.

    Third-Quarter Growth Forecast Below Previous Quarter

    The expected 31% increase in third-quarter earnings would represent a moderation from the second quarter, when S&P 500 profits rose nearly 54% year over year, according to LSEG.

    That was the highest reported growth rate since 2021.

    Excluding mark-to-market investment gains recorded by Alphabet and Amazon.com, second-quarter earnings increased approximately 35%, also representing the highest growth rate since 2021.

    Market strategists expect many companies to exceed analysts’ earnings estimates during the third-quarter reporting period, although questions remain about the sustainability of the current growth cycle.

    Anthony Saglimbene, chief market strategist at Ameriprise Financial, said continued investment in AI infrastructure has raised expectations for corporate performance.

    He noted that successive quarters of capital spending increase the financial performance required to sustain investor expectations, particularly among companies benefiting from AI development.

    Semiconductor Profit Growth Expected to Moderate

    Earnings among U.S. semiconductor manufacturers are forecast to increase approximately 136% compared with the third quarter of 2025, according to LSEG data.

    The projected growth rate is below the roughly 158% increase recorded in the second quarter.

    Nick Raich, chief executive of Earnings Scout, said upward revisions to earnings forecasts are beginning to slow, although AI infrastructure investment continues at a substantial pace.

    Raich cited recent results from Micron Technology (NASDAQ:MU) as an indication that companies supplying AI-related infrastructure continue to receive orders and investment commitments.

    Micron last month issued a quarterly revenue forecast above market expectations and reported that customer commitments under long-term supply agreements had reached $32 billion.

    Google also entered into a substantial power agreement with Constellation Energy this week, adding to developments associated with infrastructure spending.

    Rising Borrowing Costs Remain Under Review

    Alongside AI-related spending, investors are expected to focus on the effects of higher interest rates on corporate earnings.

    U.S. bond yields have increased amid inflation expectations, rising oil prices and concerns about public debt in France and other countries.

    Samana identified utilities and other companies that rely heavily on borrowing as potentially exposed to higher financing costs.

    The third-quarter reporting season will provide updated information on whether AI-related companies can maintain their recent earnings growth rates and how higher interest expenses are affecting other sectors.

    While the overall earnings outlook remains for substantial year-over-year growth, LSEG estimates indicate a slower pace than in the second quarter and continued concentration of profit increases among technology and AI-related businesses.

  • UBS Projects Gold at $5,400 by September 2027 Despite Near-Term Risk of $4,000 Retest

    UBS Projects Gold at $5,400 by September 2027 Despite Near-Term Risk of $4,000 Retest

    UBS has maintained its forecast for gold to reach $5,400 per ounce by September 2027, while warning that higher U.S. real interest rates and a firm dollar could lead to a short-term decline towards $4,000.

    UBS strategist Giovanni Staunovo said the current interest rate environment has increased the cost of holding non-yielding assets such as gold.

    Spot prices stood at $4,191 per ounce on Friday at the time of the original report, with the bank identifying $4,000 as a potential support level where longer-term buyers could enter the market.

    Staunovo attributed recent selling pressure partly to speculative investors reducing net long positions in gold futures and options.

    In contrast, investment flows into gold-backed ETFs have continued in recent weeks, with holdings remaining relatively stable despite movements in bond yields.

    Structural Demand Remains a Factor in UBS Outlook

    According to UBS, gold’s response to rising real yields has been less pronounced than in previous market cycles.

    Staunovo suggested that continued demand from central banks and other longer-term buyers has partly offset the effects of higher interest rates.

    The bank identified several factors supporting its gold outlook, including reserve diversification by central banks, concerns about public debt and borrowing costs, expectations for eventual dollar depreciation and demand from China.

    UBS also expects seasonal purchases in India to contribute to demand, particularly if prices decline during the country’s festival period.

    Preliminary September data showed China purchased 23 metric tons of gold, while Uzbekistan acquired 7 metric tons.

    The bank expects total annual central bank purchases to range between 750 and 1,000 metric tons.

    Interest Rate Expectations Differ From Market Pricing

    UBS noted that financial markets are currently anticipating slightly more than 75 basis points of Federal Reserve rate increases through 2027.

    The bank’s own forecast differs, calling for one further rate increase in 2026 followed by two quarter-percentage-point reductions in 2027.

    Staunovo expects changes in market expectations surrounding monetary tightening to influence gold prices, particularly if real interest rates begin to decline.

    UBS forecasts gold reaching $4,600 per ounce in December 2026, followed by $5,000 in March 2027 and $5,200 in June. Its September 2027 target stands at $5,400 per ounce.

    The projections reflect the bank’s expectation that demand from central banks and other investors will continue to influence the gold market even if higher interest rates create near-term price pressure.

    UBS Identifies $4,000 as Potential Buying Level

    Staunovo expects structural investment demand to provide support if gold prices move back towards $4,000 per ounce.

    The strategist considers declines towards that level potential opportunities to increase gold holdings, consistent with UBS’s longer-term price forecasts.

    He also recommends that investors interested in real assets consider allocating a mid-single-digit percentage of their portfolios to gold.

    The bank’s outlook therefore distinguishes between the possibility of further short-term price declines and its expectations for higher gold prices during 2027, with interest rates, currency movements and central bank purchases remaining principal factors in its projections.

  • Barclays Forecasts 16% European Earnings Growth in 2026 Despite Rising Bond Yields

    Barclays Forecasts 16% European Earnings Growth in 2026 Despite Rising Bond Yields

    Barclays expects European corporate earnings to increase by 16% in 2026 and 10% in 2027, although its strategists anticipate a more restrictive environment for equity markets as global monetary policy shifts towards higher interest rates.

    In a research note led by Emmanuel Cau, the bank said the end of the global monetary easing cycle is removing a source of support for equities, potentially limiting future returns and moderating economic growth.

    The strategists noted that economic activity continues to benefit from fiscal spending and capital investment in artificial intelligence, infrastructure and strategic autonomy. Nominal economic growth also remains above nominal bond yields, according to the bank.

    However, Barclays expects higher financing costs to place limits on debt-funded AI investment and contribute to wider differences in equity performance across sectors and companies.

    Interest Rates Change Equity Valuation Conditions

    The bank said rising government bond yields are increasing competition between equities, fixed-income investments and cash.

    As interest rates move higher, Barclays expects investors to place greater emphasis on earnings performance, particularly as equity risk premiums have continued to decline.

    The strategists said the investment environment now offers fewer advantages from holding equities solely because alternative assets provide limited returns.

    Barclays expects corporate earnings to remain a principal factor supporting European stock valuations, with the current investment cycle contributing to continued profit growth.

    The bank anticipates that third-quarter earnings growth will remain in double digits, although below the pace recorded during the second quarter.

    Price-to-earnings ratios have also returned towards historical averages, according to Barclays, following recent market adjustments.

    Market Positioning and Fourth-Quarter Prospects

    Barclays said the combination of rising oil prices, higher bond yields and renewed fiscal uncertainty affected European equities during September, following gains earlier in the summer.

    France has been a particular focus of fiscal concerns, although the bank does not consider the current situation comparable with the European sovereign debt crisis of 2011.

    The strategists believe that investor positioning has become less extended, while seasonal patterns could provide some support during the final quarter of the year.

    They also noted that equity markets have already adjusted to higher financing costs and energy prices through lower valuation multiples and reduced participation in market gains.

    Current market pricing implies three to four interest rate increases by major central banks over the coming 12 months, according to Barclays.

    In energy markets, improved crude oil flows have helped contain Brent prices, although uncertainty remains over the possibility of a sustained easing of tensions between the United States and Iran.

    The bank therefore sees a limited possibility of further gains in European equities before year-end rather than a broad improvement in market conditions.

    Barclays Maintains Regional and Sector Preferences

    Barclays continues to hold a market-weight allocation to European equities relative to U.S. stocks.

    Within Europe, the bank prefers Germany and peripheral markets over France, while Japan remains its principal regional overweight.

    The strategists favour companies exposed to capital investment spending, alongside banking stocks. Barclays has also selectively increased allocations to telecommunications businesses with lower sensitivity to wider market movements.

    By contrast, the bank maintains a cautious assessment of consumer, real estate and materials companies, reflecting their sensitivity to interest rates and energy costs.

    Barclays said AI-related investment continues to support growth, although enthusiasm surrounding the sector has moderated as borrowing costs increase.

    The bank’s forecasts suggest that European earnings could continue expanding through 2027, while higher bond yields and tighter monetary conditions may limit the extent of equity market gains.

  • ECB’s Lane Links Rising Bond Yields to U.S. AI Spending as Energy Inflation Remains Under Review

    ECB’s Lane Links Rising Bond Yields to U.S. AI Spending as Energy Inflation Remains Under Review

    European Central Bank chief economist Philip Lane said increased investment in artificial intelligence, particularly in the United States, is contributing to higher long-term bond yields, adding another global factor to the ECB’s assessment of monetary policy.

    Speaking in an interview with Italian news agency ANSA published Tuesday, Lane identified AI investment as a major development affecting international economic conditions.

    He explained that U.S. companies are taking on substantial long-term debt to finance AI-related spending, contributing to upward pressure on bond yields.

    The expansion of artificial intelligence is also affecting global trade flows, with demand increasing for semiconductor chips and other materials associated with the technology. Lane noted that European businesses participate in parts of this supply chain.

    Higher long-term interest rates can restrict economic activity and reduce inflation in the eurozone, particularly when the increases originate from global rather than domestic developments, Lane said.

    He added that the ECB would incorporate these effects into its assessment of inflation, economic risks and the appropriate level of policy interest rates.

    ECB Monitors Energy Costs and Secondary Inflation Effects

    Lane said energy prices remain an important consideration for monetary policy following the increases that have contributed to the ECB’s recent rate decisions.

    Although energy costs have risen, he indicated that there has been limited evidence so far of substantial second-round inflation effects, where initial price increases spread more widely through the economy.

    The extent of any further transmission remains uncertain, according to Lane, who cautioned against assuming that current conditions fit neatly into the ECB’s baseline or adverse economic projections.

    Lane also discussed the eurozone’s performance during the summer, when a temporary reduction in energy prices following an understanding between Iran and the United States provided some support to economic activity.

    He said renewed increases in energy costs and uncertainty surrounding the conflict have created questions about whether those conditions will continue.

    Government Spending and Italian Inflation

    Looking at fiscal policy, Lane noted that this year’s economic support includes Germany’s infrastructure and defence programme, alongside the concluding year of the European Union’s Next Generation recovery fund.

    He indicated that the composition of fiscal support would change in the years ahead.

    In Italy, where the latest reported inflation rate stood at 4.1%, Lane supported targeted assistance for households with lower incomes rather than broad-based fiscal expansion.

    He said general increases in public spending would not help bring inflation back to the ECB’s 2% target within an appropriate timeframe.

    The ECB’s September forecasts anticipate that Italian wages will increase faster than consumer prices in 2027 and 2028.

    However, Lane warned that wage growth exceeding sustainable levels could affect foreign investment and employers’ willingness to recruit additional workers.

    Interest Rate Policy and Long-Term Economic Stability

    Lane reiterated the ECB’s position that interest rate increases are intended to preserve price stability.

    He said inflation remaining at 3% or 4% would have substantial effects on households, while expectations of persistently elevated inflation could also contribute to rising long-term borrowing costs.

    Lane advised governments to account for higher interest expenses when preparing public budgets and to focus on reforms that support economic growth.

    His remarks outlined several considerations for ECB policymakers, including global borrowing linked to AI investment, energy market developments, inflation expectations and the future direction of fiscal policy.

  • UBS Expects Copper Market Shortfall to Increase in 2027, Forecasts $15,500 Price

    UBS Expects Copper Market Shortfall to Increase in 2027, Forecasts $15,500 Price

    UBS has maintained its positive assessment of the copper market, projecting a larger supply deficit in 2027 and forecasting that prices will move towards $15,500 per metric ton.

    The bank estimates that the copper market will record a supply shortfall of 219,000 metric tons in 2026, rising to 379,000 metric tons the following year.

    The forecasts indicate an increase of 160,000 metric tons in the annual deficit, reflecting UBS’s expectation of a widening imbalance between copper availability and demand.

    Based on its supply outlook, UBS expects copper prices to approach $15,500 per metric ton in 2027.

    The bank has also reiterated its recommendation for investors to hold long positions in the commodity, citing its expectations for the market.

    In addition, UBS considers potential near-term declines in copper prices as opportunities to add exposure through long positions.

    The bank’s outlook therefore combines expectations of a widening supply deficit with a forecast for higher copper prices in 2027, while maintaining its existing positioning recommendation.

  • Bernstein Sees Further Memory Chip Price Increases After Nearly 20% Rise in Q3

    Bernstein Sees Further Memory Chip Price Increases After Nearly 20% Rise in Q3

    Prices for memory chips climbed by almost 20% during the third quarter of 2026 compared with the preceding three months, according to Bernstein, which expects supply shortages to continue affecting the market into 2027.

    The research firm’s assessment of contract pricing showed that conventional DRAM and NAND memory products both recorded increases during the July-to-September period. The quarterly advance was smaller than that recorded in the second quarter but remained above historical pricing trends.

    Bernstein identified demand from artificial intelligence applications as a principal factor behind the supply imbalance. The firm said AI-related requirements continue to exceed available production, contributing to persistent shortages across the memory market.

    Looking ahead, Bernstein anticipates another increase in memory contract prices during the final quarter of 2026. It also expects supply constraints to remain in place during 2027, potentially extending the period of rising prices.

    Despite that outlook, the firm expects the potential magnitude of future price increases to become more limited. Price ceilings established under long-term agreements could restrict adjustments, while the growing cost of memory components may constrain spending across both AI and traditional computing applications.

    Bernstein also highlighted the effects of higher memory prices on customers outside the artificial intelligence market, where component costs are increasing alongside AI-related demand.

    The firm’s projections point to continued supply constraints and further pricing adjustments, although contractual limits and customer cost pressures are expected to affect the extent of future increases.

  • US Stock Futures Climb as Tech Shares Seek Recovery Following Nasdaq Sell-Off: Dow Jones, S&P, Nasdaq, Wall Street

    US Stock Futures Climb as Tech Shares Seek Recovery Following Nasdaq Sell-Off: Dow Jones, S&P, Nasdaq, Wall Street

    US stock index futures advanced on Friday as investors looked towards a potential recovery in technology shares following a difficult session on Wall Street, while lower crude oil prices helped ease concerns about inflation.

    Nasdaq 100 futures gained 0.7%, suggesting that technology stocks could lead early gains after Thursday’s decline, which was intensified by reports raising questions about OpenAI’s revenue performance.

    Despite the setback, investor interest in artificial intelligence remains an important source of support for technology shares, although concerns about valuations and earnings expectations have increased.

    Oil prices also moved lower after geopolitical developments helped reduce fears of an immediate military escalation involving Iran.

    However, a rebound in US Treasury yields threatened to limit buying interest as traders prepared for next week’s inflation reports and the beginning of the quarterly earnings season.

    Investors Await US Inflation Figures and Major Bank Results

    The upcoming economic calendar includes reports on consumer and producer prices from the US Labor Department.

    Both releases will be closely watched for evidence of whether inflationary pressures are easing or remaining elevated.

    The figures could influence expectations for Federal Reserve interest rate policy, particularly following recent volatility in Treasury yields and energy markets.

    Attention will also turn to quarterly earnings announcements from major financial institutions.

    Citigroup (NYSE:C), JPMorgan Chase (NYSE:JPM), Wells Fargo (NYSE:WFC) and Bank of America (NYSE:BAC) are among the banks scheduled to release their results.

    Their financial performance and management forecasts will provide investors with further information about lending conditions, consumer activity and the broader economic outlook.

    Daniela Hathorn, senior market analyst at Capital.com, said the relationship between earnings growth and inflation would be important for the direction of equities.

    “Strong earnings combined with moderating inflation would offer the most supportive backdrop for equities,” Hathorn said.

    She warned that disappointing company forecasts alongside persistent inflation could increase market vulnerability.

    “Conversely, persistent price pressures alongside disappointing corporate guidance could expose the vulnerability of a market increasingly dependent on a relatively small group of technology companies to sustain its rally.”

    The remarks highlighted concerns that recent market strength has relied heavily on a limited number of major technology companies.

    Nasdaq Retreats Further From Record High

    US equities closed mostly lower on Thursday as technology stocks came under renewed selling pressure.

    The Nasdaq Composite fell 345.35 points, or 1.3%, to 27,193.34, extending its retreat from Tuesday’s record closing level.

    The S&P 500 declined 36.41 points, equivalent to 0.5%, ending the session at 7,765.36.

    The Dow Jones Industrial Average performed slightly better, adding 51.77 points, or 0.1%, to finish at 51,231.64.

    Although the Nasdaq recovered from its lowest levels of the day, technology shares remained under pressure as investors reacted to geopolitical developments and concerns surrounding artificial intelligence companies.

    The declines followed modest losses in the previous session, suggesting that market participants were becoming more cautious ahead of important economic and corporate announcements.

    Oil Market Volatility Adds to Investor Uncertainty

    Energy prices played a significant role in Thursday’s trading after crude oil futures surged on reports of possible renewed US military action against Iran.

    NBC News reported that President Donald Trump and members of his national security team had discussed options for restarting large-scale military operations in the coming weeks.

    The report cited a US official and another person familiar with the discussions, indicating that potential strikes before next month’s midterm elections were among the options considered.

    Oil prices subsequently eased after Trump denied that the United States would attack Iran before the elections.

    His comments briefly helped US stocks recover as investors reassessed the immediate risk of military escalation.

    Nevertheless, crude prices remained sharply higher during Thursday’s session.

    Continuing attacks on tankers in the Middle East and the possibility of hurricane-related disruptions to oil production in the Gulf of Mexico maintained concerns about supply.

    The developments highlighted the potential for geopolitical events and weather-related disruptions to influence inflation expectations through energy prices.

    OpenAI Revenue Concerns Trigger Technology Sector Losses

    Technology stocks faced additional pressure after the Financial Times reported that OpenAI’s annualised revenue was approximately $20 billion below the level previously indicated by the company.

    The newspaper cited financial documents shared with investors as the basis for its report.

    The information prompted renewed scrutiny of revenue expectations within the artificial intelligence sector, where investors have anticipated substantial growth from continued spending on AI infrastructure and services.

    Semiconductor shares were particularly affected.

    The Philadelphia Semiconductor Index dropped 3.4%, reflecting widespread selling among chip-related companies.

    Computer hardware stocks also declined, with the NYSE Arca Computer Hardware Index losing 2.5%.

    Networking companies and biotechnology stocks recorded notable losses, adding to the weakness across technology and growth-oriented sectors.

    Energy producers, meanwhile, benefited from the increase in crude prices, with oil-related shares moving higher despite the broader market decline.

    Treasury Yields and Earnings Outlook Remain Key Risks

    Friday’s rise in US futures indicated that investors were considering a return to technology shares after the previous day’s losses.

    Lower crude prices provided additional support, although higher Treasury yields remained a potential constraint on market gains.

    Rising bond yields can make equities less attractive relative to fixed-income investments and place particular pressure on highly valued growth companies.

    With inflation data and major bank earnings approaching, traders may remain reluctant to make substantial commitments before receiving clearer evidence about economic conditions and corporate profitability.

    The coming reports will also test whether earnings growth can support equity valuations amid concerns about inflation and the concentration of market gains.

    For now, US futures suggest a stronger start to Friday’s session, but the sustainability of any rebound will depend on developments in energy markets, interest rates and the outlook for corporate earnings.
  • European Stocks Rebound as Oil Prices Fall and French Bond Yields Ease: DAX, CAC, FTSE100

    European Stocks Rebound as Oil Prices Fall and French Bond Yields Ease: DAX, CAC, FTSE100

    European stock markets advanced sharply on Friday, recovering from two consecutive sessions of losses as declining oil prices and easing French government bond yields helped improve investor sentiment.

    The rebound followed comments from US President Donald Trump indicating that Washington would not launch military strikes against Iran before next month’s midterm elections and that discussions with Tehran remained productive.

    The remarks helped ease immediate concerns about a potential escalation in the Middle East, contributing to a decline in crude oil prices and supporting European equities.

    Investors also welcomed a retreat in French government bond yields, which had previously reached their highest levels in several decades amid concerns about the country’s fiscal outlook.

    Germany’s DAX climbed 1.3%, while the UK’s FTSE 100 gained 1.2%. France’s CAC 40 advanced 1%, reflecting broad-based gains across major European markets.

    Energy Prices and Inflation Remain in Focus

    The decline in oil prices provided some relief to European markets, where concerns about energy costs and inflation have weighed on sentiment.

    Bank of France Governor Emmanuel Moulin attributed inflationary pressures across the Eurozone entirely to energy-related shocks, describing their contribution as “100 percent”.

    Moulin also said he had not observed second-round inflationary effects, suggesting that higher energy prices had not yet triggered broader increases in wages and other prices.

    His comments highlighted the importance of energy markets in shaping the region’s inflation outlook and expectations for monetary policy.

    A sustained decline in oil prices could help reduce inflationary pressures, although the broader outlook remains sensitive to geopolitical developments and energy supply conditions.

    French Fiscal Concerns Ease but Remain a Market Risk

    French government bonds also attracted attention after yields retreated from recent multi-decade highs.

    The decline helped ease pressure on European financial markets, although concerns about France’s public finances remain unresolved.

    Speaking at a news conference on Thursday, European Economic Commissioner Valdis Domrovskis urged France to adopt a fiscally responsible budget for 2027.

    He said prudent fiscal planning would be important for reassuring financial markets ahead of the country’s presidential election next year.

    The comments underscored continued scrutiny of France’s fiscal position, particularly after the recent increase in government borrowing costs.

    While lower bond yields supported Friday’s recovery, investors remain attentive to the country’s budget negotiations and the potential implications for European debt markets.

    Porsche Shares Rise Despite Decline in Vehicle Deliveries

    Among individual stocks, German sports car manufacturer Porsche (TG:PAH3) recorded gains despite reporting weaker global vehicle deliveries.

    The company said deliveries during the first nine months of 2026 declined 16% compared with the corresponding period a year earlier.

    Although the figures pointed to weaker vehicle sales volumes, Porsche shares advanced alongside the broader recovery in European equities.

    The announcement did not provide additional details explaining the positive share price reaction.

    Hexagon Gains After $535 Million Rocscience Acquisition

    Swedish industrial technology group Hexagon AB (TG:0QJ0) also rallied after announcing an agreement to acquire Canadian software company Rocscience.

    The transaction values Rocscience at $535 million on a cash-free, debt-free basis.

    The acquisition will expand Hexagon’s portfolio of industrial technology and software capabilities.

    Investors responded positively to the announcement, with Hexagon shares advancing during Friday’s session.

    The companies did not provide additional financial details about the expected earnings contribution or integration costs in the information released.

    Sika and Tryg Advance on Corporate Developments

    Swiss specialty chemicals manufacturer Sika (TG:SIKA) posted strong gains after announcing the acquisition of British landscaping products company Azpects Group.

    The transaction adds another business to Sika’s operations, although financial terms were not disclosed in the announcement.

    Scandinavian insurer Tryg (TG:T2V1) also moved sharply higher following the release of its third-quarter financial results.

    The company reported pre-tax profit above analysts’ expectations, supporting investor confidence in its earnings performance.

    The gains across Porsche, Hexagon, Sika and Tryg contributed to the positive tone in European equity markets.

    European Markets Recover After Two-Day Decline

    Friday’s advance reflected a combination of easing geopolitical concerns, lower energy prices and reduced pressure in government bond markets.

    Comments suggesting that US-Iran discussions remain productive helped calm immediate fears of military escalation, while the pullback in French bond yields provided additional support.

    Corporate developments also influenced trading, with acquisitions and stronger-than-expected earnings attracting investor interest.

    Despite the rebound, markets remain exposed to uncertainty surrounding Middle Eastern tensions, European inflation and France’s fiscal outlook.

    Investors will continue to assess whether the improvement in sentiment can be sustained as political and economic developments unfold.