Blog

  • Greenland Mines Brings Two Major Critical Minerals Opportunities Together

    Greenland Mines Brings Two Major Critical Minerals Opportunities Together

    Greenland Mines Ltd (NASDAQ:GRML), (FSE: HK6) is bringing together two significant critical minerals opportunities in Greenland, combining its established Skaergaard palladium-gold-platinum project with the newly acquired Sarfartoq neodymium-praseodymium rare earths project.

    The combination gives the company exposure to two strategically important areas of the critical minerals market while establishing the foundations of a broader North Atlantic minerals platform.

    The strategy has moved forward significantly during 2026. Greenland Mines has advanced technical work at Skaergaard, completed the acquisition of Sarfartoq and continued to develop plans connecting Greenland’s mineral resources with potential downstream processing and industrial markets in Europe and North America.
    A Major Palladium, Gold and Platinum Opportunity

    At the heart of Greenland Mines’ portfolio is the Skaergaard Project in southeast Greenland, a large-scale mineral system containing palladium, gold and platinum, alongside potential critical-metal by-products.

    The company’s 2026 S-K 1300 Mineral Resource Estimate reported 15.0 million ounces of palladium equivalent in the Indicated category and a further 17.49 million ounces in the Inferred category. The Indicated resource includes approximately 7.57 million ounces of palladium, 3.19 million ounces of gold and 0.60 million ounces of platinum.

    These figures are from the Skaergaard Technical Report Summary prepared by SLR Consulting (Canada) Ltd., with a Mineral Resource Estimate effective July 3, 2026. Palladium-equivalent (PdEq) is a calculated measure based on the report’s metal-price and recovery assumptions; it is not a quantity of contained palladium.

    Importantly, Greenland Mines is continuing to add technical understanding to the resource rather than simply relying on its existing scale.

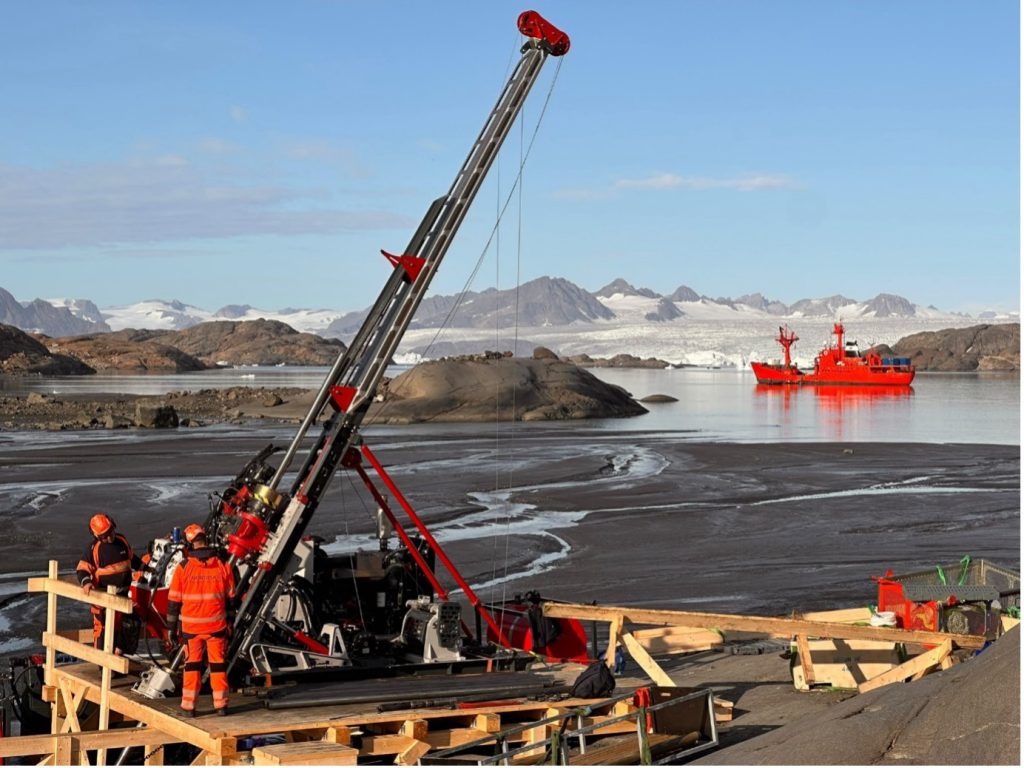
    Its 2026 field programme included drilling, geotechnical work, geophysical surveys, environmental studies and bulk sampling. The company completed 4,480 metres of diamond drilling across 17 holes, together with more than nearly 105 tonnes of bulk material, providing  materials for advanced metallurgical and process flow-sheet bench and pilot plant test-work.

    The bulk-sampling programme itself exceeded the original plan, with 104.8 tonnes of material collected from seven sites. The samples cover different mineralised horizons.

    This work represents an important step as Greenland Mines continues to evaluate and advance the Skaergaard Project towards production.

    Sarfartoq Adds a Second Critical Minerals Opportunity

    The company’s strategy became considerably broader with its acquisition of the Sarfartoq rare earth project in southwest Greenland, which closed in September 2026.

    Sarfartoq is focused particularly on neodymium and praseodymium, two magnet rare earth elements that are important components in permanent magnets used in electric vehicles, wind turbines, robotics, defence systems and other advanced technologies.

    The project has an extensive exploration history, with more than 15 years of drilling, metallurgical testing, engineering studies and environmental work.

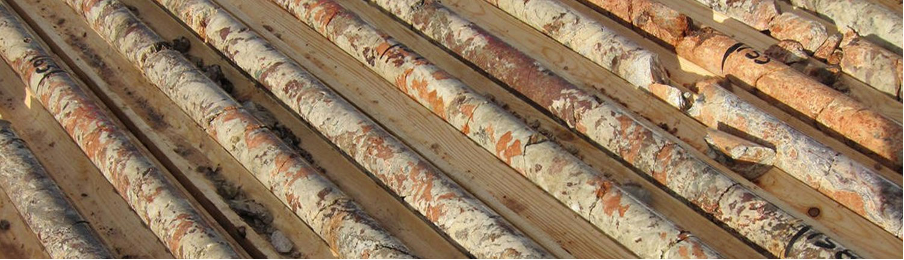
    In August, Greenland Mines announced an independently prepared S‑K 1300 Technical Report Summary for Sarfartoq, effective July 31, 2026, reporting an Indicated Mineral Resource under S‑K 1300 for the first time.

    The resource is particularly notable for its concentration of the magnet rare earth elements that are most important to today’s supply chains.
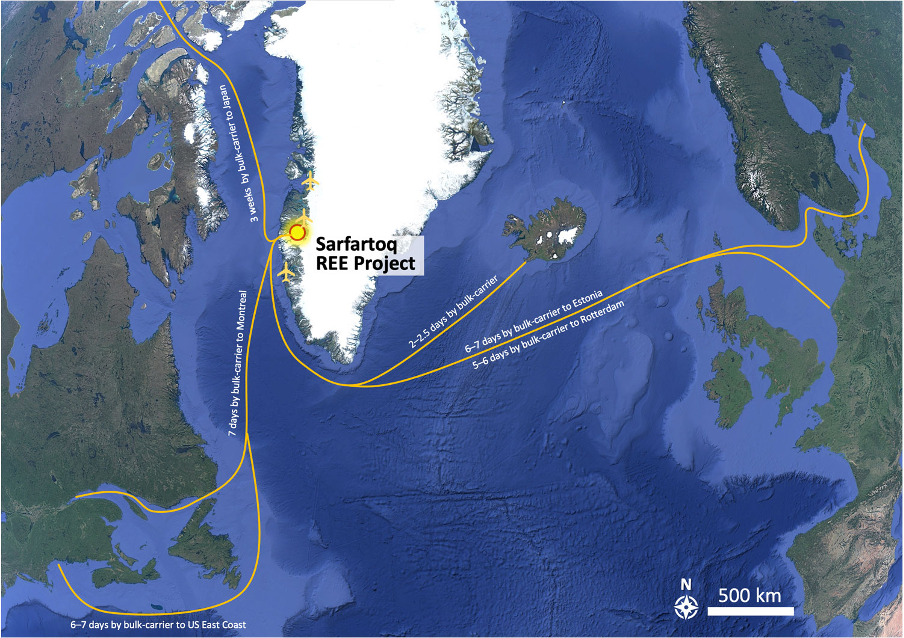
    Greenland Mines also has an important strategic relationship with Neo Performance Materials, which retains offtake rights covering up to 60% of future Sarfartoq ore or mineral concentrate production, subject to the relevant project development conditions.

    That relationship provides the project with a potential connection into Western rare earth processing and magnet supply chains.

    Two Projects, One Broader Strategy

    The combination of Skaergaard and Sarfartoq gives Greenland Mines a differentiated portfolio.

    Skaergaard provides exposure to palladium, gold and platinum, while Sarfartoq adds exposure to neodymium, praseodymium and other rare earth elements.

    This diversification is important because the company is not dependent on a single commodity or project.

    Instead, Greenland Mines is building a portfolio around minerals that are increasingly important to energy, technology, defence and advanced manufacturing.

    The company is also pursuing a broader North Atlantic critical minerals strategy, seeking to connect Greenland’s resource base with potential processing, logistics and industrial infrastructure in the wider region. Its strategy includes potential downstream opportunities in Iceland, where it has been developing relationships around industrial infrastructure.

    Moving Towards the Next Stage

    The focus now turns to advancing both projects through their next technical milestones.

    At Skaergaard, the completed 2026 field programme provides additional drilling, sampling, geological, metallurgical and engineering information that can feed into the next phase of development work.

    At Sarfartoq, Greenland Mines is progressing work around resource upgrading, engineering, infrastructure assessment and metallurgical testing, with the company targeting further advancement towards a Pre-Feasibility Study.
    The company is therefore entering the next stage with a substantially broader portfolio than it had at the beginning of 2026.

    For investors looking at the critical minerals sector, Greenland Mines offers an interesting combination: a large-scale palladium-gold-platinum resource at Skaergaard and an advanced rare earth opportunity at Sarfartoq, both located in Greenland and supported by a strategy designed to connect resources with Western supply chains.

    With the two projects now sitting within a single platform, Greenland Mines is positioning itself around some of the mineral resources that could play an increasingly important role in the future of energy, technology, defence and industrial manufacturing.

    Cautionary Note on Project Development
    Greenland Mines’ projects remain at the exploration and development stage. Neither project is in production, and their advancement depends on further technical studies, metallurgical evaluation, permitting, financing and execution. No Initial Assessment or Pre-Feasibility Study has been completed for Skaergaard. Sarfartoq has an Initial Assessment, but further studies and development work remain necessary, and there is no assurance that either project will reach production.
  • ITM Power Narrows FY2026 Adjusted EBITDA Loss Guidance to £20–21 Million

    ITM Power Narrows FY2026 Adjusted EBITDA Loss Guidance to £20–21 Million

    ITM Power (LSE:ITM) has revised its financial guidance for the year ended 30 April 2026, reducing its expected adjusted EBITDA loss to between £20 million and £21 million while maintaining its previous revenue and cash guidance.

    The hydrogen technology company said the revised loss forecast represents a 27% improvement compared with its earlier guidance and a 38% improvement year on year.

    The adjustment indicates that ITM expects to report a smaller adjusted operating loss before interest, tax, depreciation and amortisation than previously anticipated. The company has not announced any changes to its revenue or year-end cash expectations.

    ITM confirmed that it will publish its preliminary financial results for the year ended 30 April 2026 on 19 October 2026.

    The results announcement will provide further details of the company’s financial performance during the reporting period, including its revenue, operating costs and cash position.

    The company also plans to engage with analysts and investors in connection with the results publication, providing an opportunity to discuss its financial performance and operational developments.

    The revised guidance follows ITM’s ongoing activities in the development and manufacture of proton exchange membrane (PEM) electrolysers, which use electricity to separate water into hydrogen and oxygen.

    The company’s technology is designed for industrial-scale hydrogen production, with applications across industrial and energy markets seeking alternatives to conventional hydrogen production methods.

    ITM also operates through its Hydropulse business model, under which it intends to develop, own and operate hydrogen production facilities rather than solely supplying electrolyser equipment to customers.

    The forthcoming preliminary results will provide additional information on the company’s financial position and progress against its operational objectives.

    ITM Power is a UK-based manufacturer of hydrogen production equipment listed on London’s AIM market. Its operations include electrolyser manufacturing, engineering and the development of hydrogen supply solutions using proprietary PEM technology.

  • Jubilee Metals Completes Legal Due Diligence on US$35 Million Zambian Project Disposal

    Jubilee Metals Completes Legal Due Diligence on US$35 Million Zambian Project Disposal

    Jubilee Metals Group (LSE:JLP) has completed legal due diligence for the proposed sale of its Large Waste Project in Zambia, a transaction valued at approximately US$35 million, as the company continues its programme of asset disposals and investment in its Zambian copper operations.

    The company expects to receive a deposit of US$2.25 million in the coming days, coinciding with the commencement of a 45-day technical due diligence period.

    The proposed disposal remains subject to the completion of the technical review, with the transaction forming part of Jubilee’s strategy to redirect capital towards its existing copper mining, processing and refining activities in Zambia.

    Together with approximately US$65 million in remaining cash proceeds from the sale of its South African operations, Jubilee expects potential cash inflows of up to US$100 million from the two transactions.

    The anticipated proceeds would provide additional funding for the group’s Zambian copper development programme, although the Large Waste Project disposal has not yet been completed.

    Jubilee said the planned sale is intended to reduce its exposure to the development requirements of the Large Waste Project while allowing the company to allocate resources to other assets within its portfolio.

    The group is focusing on expanding its existing copper operations, including the Molefe Mine, where results from the second phase of drilling are expected shortly.

    According to management, the company’s investment priorities include projects that can utilise its established mining, processing and refining infrastructure in Zambia.

    These facilities include the Roan Concentrator, which processes copper-bearing feedstock, and the Sable Refinery, which forms part of Jubilee’s integrated copper production operations.

    The company intends to combine processing activities involving third-party feedstock with the development of its own mining and exploration assets.

    The proposed Large Waste Project disposal represents a further step in Jubilee’s restructuring of its asset portfolio following the sale of its South African operations.

    Completion of the transaction and receipt of the remaining consideration will depend on the outstanding due diligence process and applicable transaction requirements.

    Jubilee Metals Group is a copper producer and resource developer listed on London’s AIM market and the Johannesburg Stock Exchange’s AltX market. The company is focused on developing an integrated copper business in Zambia through mining, processing, refining and exploration activities.

  • MedPal AI Reports Record Daily Prescription Orders and £6.4 Million Liquidity Position

    MedPal AI Reports Record Daily Prescription Orders and £6.4 Million Liquidity Position

    MedPal AI (LSE:MPAL) has reported a record day of prescription dispensing at its New Health clinic, processing more than 2,300 private prescription orders with a combined value of approximately £300,000, as the company expands its medication inventory following a £5 million equity placing.

    The digital healthcare and pharmacy group said the placing, which was predominantly supported by existing and institutional investors, is being used primarily to increase medication stock levels to meet demand across its operations.

    As of 6 October 2026, MedPal reported approximately £6.4 million in combined cash, near-cash assets and stock. The company also identified VAT receivables, NHS prescription income and manufacturer rebates as components supporting its working capital position.

    Alongside the recent equity financing, MedPal has received an indicative £8 million working capital financing term sheet from a non-bank lender. The proposal remains indicative, and the company is continuing discussions with banking institutions regarding additional funding arrangements.

    The group has also called a general meeting to seek shareholder approval for resolutions primarily relating to its authority to issue shares and the provision of broker warrants.

    According to MedPal, the proposed resolutions are intended to restore routine corporate authorities following its recent financing activities. The company reiterated that it does not currently plan to undertake a further equity fundraising.

    The trading update follows increased prescription activity at New Health, the group’s private clinic focused on GLP-1 weight management treatments. The reported daily order volume represents a record for the business, although the company has not provided comparative figures for earlier periods in the supplied update.

    MedPal operates a range of digital healthcare and pharmacy services, including NHS Distance Selling Pharmacy hubs, private prescription services and a business-to-business pharmacy supply operation serving care homes.

    The company also provides eMARx electronic medication administration software and is developing Juno, an artificial intelligence-based health companion intended to support patient interactions and healthcare management.

    These services form part of MedPal’s planned Health OS platform, which aims to integrate prescribing, dispensing, medication delivery and AI-supported patient services.

    MedPal AI plc is a London-listed digital health and pharmacy company combining prescription dispensing, healthcare software and artificial intelligence development. Its operations span NHS and private pharmacy services, care home medication supply and digital patient support technologies.

  • Tesco First-Half Adjusted Operating Profit Rises 6.3% to £1.78 Billion as Share Buyback Target Increases

    Tesco First-Half Adjusted Operating Profit Rises 6.3% to £1.78 Billion as Share Buyback Target Increases

    Tesco (LSE:TSCO) reported a 6.3% increase in adjusted operating profit to £1.78 billion for the first half of its 2026/27 financial year, alongside higher sales, earnings and free cash flow.

    The supermarket group recorded sales excluding VAT and fuel of £33.8 billion, representing growth of 1.6% at constant exchange rates. The company attributed its performance to changes in its sales mix, cost reductions and contributions from additional revenue streams.

    Adjusted diluted earnings per share increased 12.2% compared with the corresponding period last year, while free cash flow rose 21% to £1.57 billion. Tesco also reported a reduction in net debt compared with the prior-year period.

    Following the first-half performance, the retailer increased its share repurchase target for the current financial year to £950 million and announced a higher interim dividend.

    Tesco said customer satisfaction reached a record level during the reporting period, supported by its pricing strategy, product development and expansion of digital shopping services.

    Online sales increased 8%, reflecting continued activity across the group’s grocery delivery operations. Tesco also reported growth in its Whoosh rapid delivery service and expanded its delivery arrangements through partnerships with Uber Eats and Deliveroo.

    The company continued to invest in digital capabilities, including the use of artificial intelligence for personalised customer services and product recommendations.

    Other areas of development included Tesco’s retail media activities and its range of non-food products and services, which provide additional revenue opportunities alongside its core grocery operations.

    Management identified cost savings, operational efficiency and the development of additional income streams as factors contributing to the group’s first-half financial performance.

    Tesco’s latest results also reflect its ongoing capital allocation activities, with increased shareholder distributions through the expanded buyback programme and interim dividend.

    Tesco plc is a multinational grocery and general merchandise retailer operating primarily in the UK, Ireland and Central Europe. Its activities include supermarket retailing, online grocery services, rapid delivery and wholesale distribution through Booker.

    The group also operates across clothing, pharmacy, financial services and telecommunications, alongside its principal food retailing business.

  • Intercede First-Half Revenue Rises 32.1% to £10.85 Million as New Orders Reach £3 Million

    Intercede First-Half Revenue Rises 32.1% to £10.85 Million as New Orders Reach £3 Million

    Intercede (LSE:IGP) has reported a 32.1% year-on-year increase in revenue to approximately £10.85 million for the six months ended 30 September 2026, alongside around £3.0 million in new contract orders and renewals secured since early August.

    The cybersecurity software company recorded revenue growth across its perpetual software licences, recurring support and maintenance agreements, and professional services activities.

    Intercede ended the reporting period with cash balances of £23.4 million and no debt. The company confirmed that trading remains in line with market expectations for the full financial year, supported by its existing contracts and pipeline of prospective business.

    Since the beginning of August, Intercede has secured approximately £3.0 million in additional orders and contract renewals, primarily from existing customers in the United States.

    These agreements cover US federal government, defence, aerospace and telecommunications customers, with contracts spanning subscription and perpetual software licences, maintenance and support renewals, and professional services.

    The company also received authorisation to proceed with a development project valued at approximately £520,000 relating to a major US federal government deployment.

    The project adds to Intercede’s existing activities within the US public sector, where its software is used for digital identity management and authentication services.

    According to the company, the combination of first-half revenue growth, new orders and contract renewals has improved visibility over future revenue. Management said the business remains positioned to meet market expectations for revenue and earnings in the financial year ending 2027.

    The latest trading update reflects continued demand from Intercede’s established customer base, particularly in government and other sectors requiring identity verification and secure access management.

    Intercede Group is a UK-based cybersecurity software provider specialising in digital identity, credential management and secure authentication technologies.

    Its product portfolio includes identity registration and verification, password management, one-time password authentication, FIDO-based authentication and public key infrastructure (PKI) solutions. The company serves customers across government, defence, aerospace, telecommunications and other regulated industries.

  • Imperial Brands Confirms FY2026 Outlook and Announces £1.5 Billion Share Buyback for 2027

    Imperial Brands Confirms FY2026 Outlook and Announces £1.5 Billion Share Buyback for 2027

    Imperial Brands (LSE:IMB) has confirmed that it remains on track to meet its financial guidance for the year ending 2026, supported by tobacco pricing, market share gains and increased sales of next-generation nicotine products.

    The tobacco and nicotine group reported a sixth consecutive year of growth in tobacco net revenue, alongside double-digit sales growth in its next-generation products portfolio, which includes vaping, heated tobacco and modern oral nicotine products.

    Trading in the company’s principal markets, including the United States and Germany, contributed to its performance, with pricing adjustments and market share developments supporting tobacco revenue.

    Imperial expects full-year adjusted operating profit growth to remain within its previously announced range of 3% to 5%. Adjusted earnings per share are forecast to increase by a high single-digit percentage, while free cash flow is expected to exceed £2.2 billion.

    The company said cash conversion and modest favourable foreign exchange movements have contributed to its financial performance during the period.

    Alongside its trading update, Imperial confirmed the completion of its £1.45 billion share repurchase programme for 2026 and announced plans for a further £1.5 billion buyback during the 2027 financial year.

    According to the group, approximately £13 billion has been returned to shareholders over the past six years through its capital distribution activities. During that period, the number of shares in issue has declined by more than 20%.

    Imperial said its leverage remains at the lower end of its target range, providing capacity to continue its planned shareholder distributions and operational investment.

    The company is also implementing a business transformation programme targeting annual savings of at least £320 million by 2030. The initiative includes a planned £100 million reduction in overhead costs.

    The programme focuses on changes to the group’s operating structure, use of customer data and internal processes, with the stated objective of reducing costs and improving operational efficiency.

    Imperial continues to develop its next-generation products business alongside its established tobacco operations, with activities spanning vaping devices, heated tobacco products and oral nicotine alternatives.

    The company is pursuing brand development, product innovation and selected acquisitions across its markets, including the United States and Germany.

    Imperial Brands is a London-listed multinational tobacco and nicotine company with operations across combustible tobacco and next-generation product categories. Its portfolio includes cigarettes, vaping products, heated tobacco systems and modern oral nicotine products.

  • Aberdeen Group Raises £436 Million From Sale of 5.2% Stake in Standard Life

    Aberdeen Group Raises £436 Million From Sale of 5.2% Stake in Standard Life

    Aberdeen Group plc (LSE:ABDN) has announced the sale of 52 million shares in Standard Life plc, representing approximately 5.2% of the insurer’s issued share capital, through a placing priced at 839 pence per share.

    The transaction generated gross proceeds of approximately £436 million for Aberdeen, which will retain a further 5.2% holding in Standard Life following settlement.

    Standard Life was not a party to the transaction and will not receive any proceeds from the share sale.

    Aberdeen said it intends to allocate the proceeds in accordance with its existing capital allocation framework, which prioritises maintaining balance sheet strength, reinvesting selectively in the business, managing debt and providing returns to shareholders.

    The company’s stated approach includes opportunities for investment in its operations, alongside debt reduction and optimisation where appropriate. Shareholder distributions also remain part of its capital management priorities.

    The placing was conducted with Evercore acting as lead financial adviser. Goldman Sachs International and J.P. Morgan Cazenove served as joint global coordinators and bookrunners.

    Following completion, Aberdeen’s remaining interest in Standard Life will represent approximately half of its holding before the placing, reducing its equity exposure to the insurer while providing additional cash resources.

    The company has not specified how much of the proceeds will be allocated to individual capital management priorities or provided a timetable for their deployment.

    The disposal forms part of Aberdeen’s management of its investment holdings and financial resources, with the proceeds available for use under its established capital allocation policy.

    Aberdeen Group plc is a UK-listed financial services company with activities focused on asset management and investment services. Its capital allocation framework includes maintaining financial flexibility, investing in its operations, managing debt obligations and delivering shareholder returns.

  • Unite Group Reports 95.6% Student Bed Occupancy for 2026/27 as Property Valuations Decline

    Unite Group Reports 95.6% Student Bed Occupancy for 2026/27 as Property Valuations Decline

    Unite Group (LSE:UTG) has reported that 95.6% of its student accommodation beds have been sold for the 2026/27 academic year, slightly ahead of the comparable period last year, while quarterly property valuations declined across its USAF and LSAV investment funds.

    The UK student accommodation provider recorded like-for-like rental income growth of 0.6%, despite a modest reduction in average rents. The company also maintained its earnings guidance for 2026 as it continued its asset disposal programme and efforts to reduce leverage.

    Unite is targeting property disposals of between £300 million and £400 million during 2026, focusing on assets considered to offer lower growth potential. The programme forms part of a broader strategy to concentrate its accommodation portfolio around universities with higher levels of student demand.

    The group intends to reduce its future portfolio to approximately 55,000 to 60,000 beds, compared with its current estate of more than 70,000 beds. The planned changes are intended to increase the proportion of properties associated with universities identified by the company as having more consistent accommodation demand.

    Unite also provided an update on the integration of Empiric’s Hello Student platform. The business has sold approximately 92% of its available beds for the 2026/27 academic year and is expected to deliver like-for-like rental income growth of around 5%.

    The company is pursuing cost savings through the integration of Hello Student into its wider operations, although the supplied update did not specify the financial value of the anticipated synergies.

    Separately, Unite reported declines in the quarterly valuations of properties held by its Unite UK Student Accommodation Fund (USAF) and London Student Accommodation Joint Venture (LSAV).

    The valuation reductions reflected an increase in property investment yields, alongside lower income expectations for certain assets. Higher valuation yields generally result in lower property valuations when other factors remain unchanged.

    The group said demand for purpose-built student accommodation and investor interest in the sector remained supportive, although the valuation movements reflected changes in required investment returns and income assumptions.

    Unite continues to pursue its portfolio restructuring programme while maintaining its existing 2026 earnings guidance. The planned disposals and integration activities form part of its approach to managing its property portfolio and financial position.

    Unite Group plc is a London-listed owner, manager and developer of purpose-built student accommodation, operating more than 70,000 beds across university towns and cities in the UK. Its business includes accommodation provided through university nomination agreements and properties let directly to students.

  • Tap Global Reports Tap Earn Assets Above US$9 Million and Cumulative Gross Yield of US$157,000

    Tap Global Reports Tap Earn Assets Above US$9 Million and Cumulative Gross Yield of US$157,000

    Tap Global Group (LSE:TAP) has reported that assets under management in its Tap Earn cryptocurrency yield programme have exceeded US$9 million, more than doubling since the product was launched in May 2026.

    The digital finance company said Tap Earn has generated approximately US$157,000 in cumulative gross yield since launch, including around US$32,500 during September 2026.

    The programme allows eligible customers to earn yield on supported digital assets through Tap’s financial services platform. The increase in assets under management reflects additional funds allocated to the product since its introduction earlier this year.

    Tap Global is also developing its Digital Asset Income Strategy, which involves deploying part of the company’s own digital asset reserves through Tap Earn. The initiative forms part of its activities involving cryptocurrency holdings and yield-generating products.

    Alongside these developments, the company is preparing to seek authorisation under the forthcoming UK cryptoasset regulatory regime. Tap currently operates under Gibraltar’s Distributed Ledger Technology framework and holds Mastercard approval in Europe.

    The group provides digital financial services through its Tap application and associated Mastercard payment card, enabling customers to hold, transfer and spend funds, as well as access cryptocurrency trading and other supported financial products.

    According to the company, its platform serves more than 400,000 customers across over 25 countries, with trading access to more than 70 cryptocurrencies where permitted.

    Tap Earn represents one component of the group’s digital asset services, with its reported assets and gross yield providing measures of activity since the programme began operating in May.

    The company has not disclosed net income attributable to Tap Earn in the supplied update. Gross yield figures do not necessarily represent net earnings available to the group or returns received by individual customers.

    Tap Global Group plc is a London-listed financial technology company operating a digital finance platform combining payment services, cryptocurrency trading and digital asset yield products. Its activities include customer-facing financial services and the management of its own digital asset reserves.