Author: Fiona Craig

  • Currys Like-for-Like Revenue Rises 7% in First 17 Weeks

    Currys Like-for-Like Revenue Rises 7% in First 17 Weeks

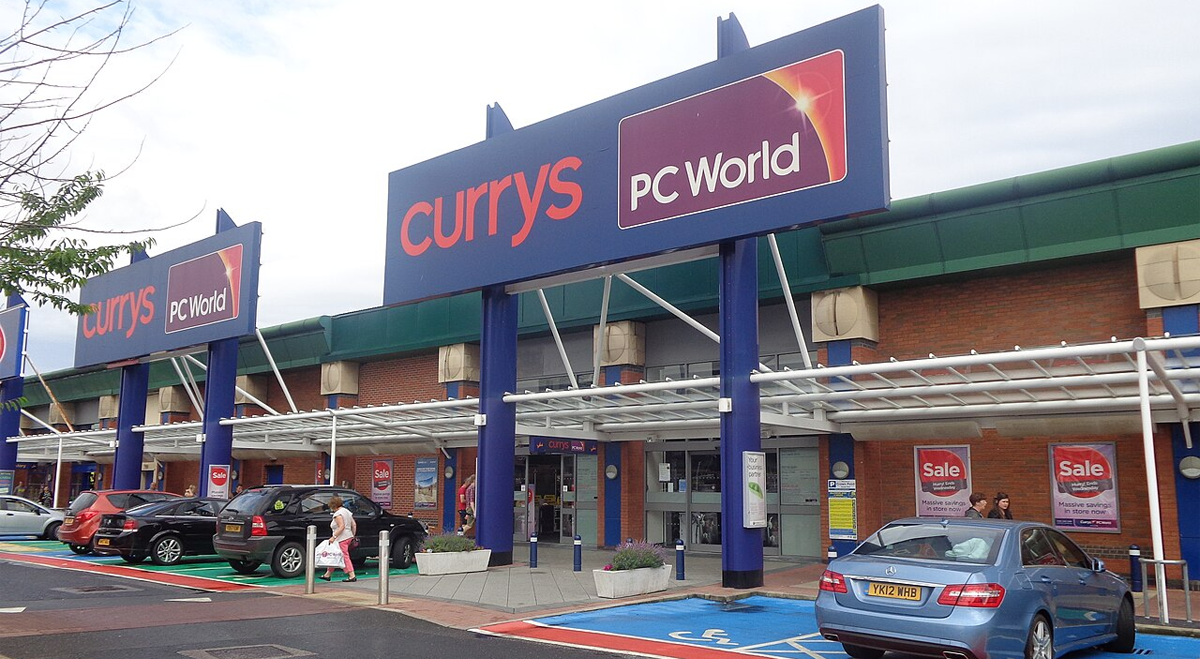
    Currys (LSE:CURY) reported a 7% increase in group like-for-like revenue for the 17 weeks ended 29 August 2026, with growth across both the UK & Ireland and Nordic businesses.

    Like-for-like revenue increased 6% in the UK & Ireland and 9% in the Nordics. The company reported higher sales through both stores and online channels during the period.

    Currys also recorded growth across newer product categories, business-to-business operations and services. The company said it increased market share across most major categories despite broadly flat market conditions in the UK.

    Gross margins remained stable during the period.

    iD Mobile Subscribers Increase 16%

    Currys reported continued growth in recurring services, with the number of iD Mobile subscribers increasing 16% to more than 2.7 million.

    The retailer also reported increased adoption of its flexpay offering.

    Currys maintained its full-year guidance and said it continues to expect year-end net cash to be well above its £100 million target.

    The company is also progressing a £50 million share buyback programme, with almost half of the programme completed at the time of the trading update.

    The update was issued by Group Chief Executive Fredrik Tønnesen.

    Currys confirmed that its 2026 annual general meeting is being held in London on 10 September 2026. Interim results covering the 26 weeks ending 31 October 2026 are scheduled to be published on 17 December 2026.

    More about Currys plc

    Currys plc is a consumer technology retailer operating through stores and online channels.

    The group trades under the Currys brand in the UK & Ireland and Elkjøp in the Nordic region, with a total of 691 stores across six countries.

    Its operations also include business-to-business services, the iD Mobile virtual mobile network, repair facilities and a European distribution network.
  • THG H1 Revenue Rises 7.2% as Adjusted EBITDA More Than Doubles

    THG H1 Revenue Rises 7.2% as Adjusted EBITDA More Than Doubles

    THG (LSE:THG) reported group revenue of £828.7 million for the six months ended 30 June 2026, an increase of 7.2% year on year and ahead of the company’s guidance.

    Adjusted EBITDA more than doubled to £42.8 million, while the group adjusted EBITDA margin increased by 210 basis points to 5.2%.

    THG also reported its highest first-half free cash flow since 2021. Cash and available facilities stood at £238.7 million at the end of the period, while net debt was £329.7 million.

    Myprotein Revenue Rises 9.2%

    THG Nutrition recorded a 9.2% increase in Myprotein revenue, while gross margin reached 44.6%.

    Adjusted EBITDA for the division more than tripled compared with the corresponding period a year earlier.

    THG cited pricing, product innovation, VAT benefits and licensing partnerships among the factors affecting the division’s results. Licensing agreements also generated royalty income and expanded the availability of Myprotein products through third-party retail channels.

    THG Beauty Revenue Increases 5.9%

    THG Beauty reported revenue growth of 5.9%, while adjusted EBITDA increased by almost 24%.

    The company said Lookfantastic and Dermstore increased their market shares during the period. Trading was also supported by the addition of prestige beauty brands and demand for Korean beauty products.

    THG continued to introduce artificial intelligence-based tools across its digital operations, including technology designed to support customer interactions and product discovery.

    More about THG

    THG PLC is a consumer brands group focused primarily on nutrition and beauty products.

    Its nutrition operations include Myprotein, which sells sports nutrition and related products through digital and third-party retail channels.

    THG Beauty operates e-commerce platforms including Lookfantastic and Dermstore, selling beauty and skincare products.

    The group also uses licensing and business-to-business partnerships to distribute its brands through channels outside its direct-to-consumer platforms.

  • Physiomics Secures Contracts Worth More Than £205,000

    Physiomics Secures Contracts Worth More Than £205,000

    Physiomics (LSE:PYC) has secured new contracts with a combined value of more than £205,000, taking the total value of awards received over the past four months to more than £750,000.

    The company said the value of contracts awarded during the four-month period is approaching its total revenue for the 2024-2025 financial year.

    The latest contracts cover multiple service areas and involve Physiomics’ mathematical modelling and data science capabilities in drug development and personalised medicine.

    Physiomics also reported international interest in its cancer treatment modelling for potential commercial and research collaborations.

    Physiomics Updates Operations and Management

    Alongside the contract awards, Physiomics has been implementing changes to its commercial and operational activities, including measures covering costs and resource allocation.

    The company has also promoted Jesse Thissen to chief operating officer.

    Physiomics said it is upgrading its IT infrastructure, quality standards and internal processes as it seeks to support larger and more complex projects.

    The board believes the recent contract awards reflect initial progress from the company’s increased commercial focus and changes to its operational structure.

    More about Physiomics

    Physiomics plc provides mathematical modelling, data science, biostatistics and bioinformatics services for drug development and personalised medicine.

    Its capabilities include modelling and simulation, biostatistics, data science and biological analysis. The company also operates its proprietary Virtual Tumour modelling technology.

    Physiomics said it has contributed to more than 140 commercial projects involving over 125 drug targets and medicines.

    Its customers have included Merck KGaA, Astellas, Bicycle Therapeutics, Numab Therapeutics and Cancer Research UK.

  • ABF Expects FY Adjusted EPS Ahead of Forecast as Primark Demerger Plans Progress

    ABF Expects FY Adjusted EPS Ahead of Forecast as Primark Demerger Plans Progress

    Associated British Foods (LSE:ABF) said group adjusted operating profit for the full year is expected to be broadly in line with its previous expectations, while adjusted earnings per share is forecast to be ahead.

    The company is continuing preparations for the planned separation of its Primark retail business from its food operations. ABF is targeting completion of the demerger in December 2027.

    Primark sales are expected to increase by approximately 2% in both the fourth quarter and the full year, supported by new store openings and franchise expansion. Like-for-like sales are expected to decline, while ABF reported challenging trading conditions in continental Europe.

    The retailer has continued its ‘Iconic Value’ pricing campaign, expanded its womenswear ranges and increased marketing activity.

    Primark Prepares for Great Britain Home Delivery

    Primark has acquired a highly automated fulfilment centre in Sheffield as part of preparations to introduce home delivery in Great Britain.

    The retailer is also continuing to expand its Click & Collect service as it develops its digital sales operations alongside its store network.

    Grocery Profit Expected Below Previous Forecast

    ABF reported sales growth across its grocery and ingredients divisions during the fourth quarter.

    Within grocery, hot weather affected Twinings tea volumes in the UK and continental Europe, while changes to distribution affected Ovaltine sales. As a result, full-year grocery profit is now expected to be slightly below the company’s previous forecast.

    ABF is also integrating Hovis following its acquisition. The company expects cost synergies from the integration to support investment in product development and its bakery operations.

    ABF to End Beet Processing at Cantley

    The sugar division reported lower sales and profitability in the UK and Spain, reflecting lower European sugar prices, higher gas costs and reduced sugar beet crop yields.

    ABF has recognised onerous contract provisions associated with conditions in the sugar business.

    The company plans to reduce its UK sugar processing footprint from four sites to three, with beet processing at Cantley scheduled to cease in 2027.

    ABF said the restructuring is intended to allow its remaining facilities to serve existing customers more efficiently.

    The group continues to invest across its retail, food and ingredients businesses while progressing preparations for the planned separation of Primark and its food operations.

    More about Associated British Foods

    Associated British Foods is an international food, ingredients and retail group.

    Its retail operations are centred on Primark, while its food businesses include brands such as Twinings, Ovaltine and Hovis alongside ingredients and sugar operations.

    Primark operates primarily through physical stores and is expanding digital services including Click & Collect and planned home delivery in Great Britain.

    ABF is also integrating Hovis into its bakery operations and restructuring its UK sugar processing network as it prepares for the planned demerger of its retail and food businesses.

  • Sunda Energy Advances New Zealand Acquisition as Chuditch PSC Enters Remedy Period

    Sunda Energy Advances New Zealand Acquisition as Chuditch PSC Enters Remedy Period

    Sunda Energy (LSE:SNDA) reported progress on its proposed acquisition of Matahio Energy NZ’s onshore Taranaki oil and gas portfolio during the first half of 2026, while its Chuditch production sharing contract in Timor-Leste entered a 120-day remedy period following a regulatory notice.

    The proposed New Zealand transaction remains conditional and would add assets producing approximately 1,000 barrels of oil equivalent per day, alongside proven and contingent reserves and exploration prospects.

    Sunda said financing for the acquisition has been secured, including funding backed by directors. Government approval for the change of control is expected in late September or early October 2026.

    Operational preparations for the acquired portfolio are already under way, including planning for the Oru-2 exploration well and the proposed restart of production from the Puka field.

    Chuditch PSC Faces Termination Notice

    In Timor-Leste, Sunda’s subsidiary continued work on the Chuditch gas discovery and secured an environmental licence as part of preparations for the proposed Chuditch-2 appraisal well.

    The company has also been pursuing a rig-sharing arrangement for the planned well.

    However, the regulator issued a notice of intention to terminate the Chuditch production sharing contract after drilling commitments were not met.

    The notice triggered a 120-day period during which the matter can be remedied. The future of the PSC therefore remains subject to the outcome of that process.

    Technical Work Begins in the Philippines

    Sunda also commenced detailed technical studies and seismic reprocessing across its licences in the Philippines during the period.

    The company completed a capital reorganisation as it continued work across its New Zealand, Timor-Leste and Philippine portfolio.

    Completion of the Matahio Energy NZ acquisition remains subject to the applicable conditions and government approval, while further activity at Chuditch depends on the outcome of the PSC remedy process and arrangements for the proposed appraisal well.

    More about Sunda Energy Plc

    Sunda Energy Plc is an AIM-quoted upstream oil and gas company with activities across the Asia-Pacific region.

    Its portfolio includes the Chuditch gas discovery in Timor-Leste and exploration licences in the Philippines. The company has also agreed to acquire producing and exploration assets in New Zealand, subject to completion of the transaction.

    Its activities include oil and gas production, appraisal and exploration, as well as technical studies, seismic reprocessing and preparations for drilling programmes.

  • Fevertree H1 Brand Revenue Rises 8% as Adjusted EBITDA Reaches £20.1 Million

    Fevertree H1 Brand Revenue Rises 8% as Adjusted EBITDA Reaches £20.1 Million

    Fevertree Drinks (LSE:FEVR) reported Fever-Tree brand revenue of £183.6 million for the six months ended 30 June 2026, an increase of 8% at constant currency, with growth recorded across all regions.

    The company said the brand achieved record retail market shares in ginger beer and tonic during the period.

    In the U.S., Fevertree reported increased activity under its partnership with Molson Coors. The UK business returned to revenue growth, with the company citing higher off-trade sales and favourable summer weather during the period.

    Products outside the group’s tonic range continued to account for a greater proportion of sales, with the wider portfolio representing almost half of group revenue.

    Adjusted EBITDA Rises 9%

    Adjusted EBITDA increased 9% to £20.1 million, while the adjusted EBITDA margin rose to 10.9%.

    Diluted earnings per share increased 38% compared with the corresponding period a year earlier.

    Fevertree also announced a new £60 million share buyback programme following the completion of a £100 million programme in 2025.

    The company maintained its full-year guidance.

    More about Fevertree Drinks

    Fevertree Drinks plc produces mixers and soft drinks, including tonic waters, ginger beer and flavoured sodas.

    The company operates across markets including the UK, U.S., Europe and other international regions, selling products for use in both alcoholic and non-alcoholic drinks.

    Its product portfolio has expanded beyond tonic water to include ginger beer, sodas and other mixer categories.

  • United Oil & Gas Appoints NRG for Jamaica Drilling Study

    United Oil & Gas Appoints NRG for Jamaica Drilling Study

    United Oil & Gas (LSE:UOG) has appointed NRG Well Management to conduct a drilling rig and long-lead availability study for its Walton-Morant exploration licence offshore Jamaica.

    The study will assess available drilling rigs, indicative day rates, procurement timelines and regional logistics as United continues its farm-out process for the licence.

    NRG will engage with international drilling contractors and supply-chain providers to gather current market information for potential future drilling operations.

    The work will support planning for possible exploration wells targeting the Colibri and Thunderball prospects. United said the two prospects have combined mean prospective resources of more than 1 billion barrels within a wider portfolio containing approximately 7 billion barrels of mean prospective resources.

    Prospective resources represent estimated quantities associated with undiscovered accumulations and are not reserves.

    Study Does Not Commit United to Drilling

    United said the study is intended to develop its operational planning and does not represent a commitment to drill an exploration well.

    Any future drilling programme would remain subject to factors including regulatory approvals in Jamaica and the completion of commercial agreements.

    The company expects the information gathered by NRG to support discussions with potential farm-out partners by providing updated estimates covering rig availability, costs, procurement requirements and potential drilling schedules.

    More about United Oil & Gas Plc

    United Oil & Gas Plc is an AIM-listed oil and gas company with assets in the UK and Jamaica.

    Its portfolio includes the Walton-Morant offshore exploration licence in Jamaica, where the company is progressing technical and operational work alongside a farm-out process.

    The company also holds a development asset in the UK and focuses on upstream oil and gas exploration and development.

  • System1 Revenue Rises 11% in First Five Months of FY2027

    System1 Revenue Rises 11% in First Five Months of FY2027

    System1 Group PLC (LSE:SYS1) reported an 11% year-on-year increase in total revenue for the first five months of its 2027 financial year, while platform revenue increased 12%.

    The company said growth reflected increased activity from existing customers alongside new client wins. Revenue from new platform customers was approximately 20% higher than in the comparable period a year earlier.

    System1 reported new contracts with customers including a major U.S. automotive manufacturer, a global food group and a luxury retailer.

    The U.S. became System1’s largest market during the period, while revenue from Continental Europe increased 56% year on year.

    Revenue from both advertising testing and innovation testing increased 12%, while brand-related revenue declined.

    Net platform revenue retention improved to 80%. System1 reported cash of £11.2 million at the end of August and said trading remained consistent with current market expectations.

    System1 Launches Test Your Ad Screen

    System1 also launched Test Your Ad Screen, an artificial intelligence-based tool designed to provide rapid screening of advertising effectiveness.

    The company said the tool was trained using a dataset containing 18 million human emotional responses.

    System1 has demonstrated the product to a range of prospective customers, including global companies and smaller brands. The supplied information does not provide revenue or customer adoption figures for the new product.

    More about System1

    System1 Group PLC provides a marketing decision-making platform covering advertising, product innovation and brand testing.

    The company’s services use a database of human emotional responses to assess marketing materials and product concepts. Its operations combine predictive research, digital testing tools and consultancy services.

    System1’s platform serves more than 600 clients across 81 markets, with operations including the U.S., UK and Continental Europe.

  • UK Oil & Gas Renames as UK Energy Group Following Strategy Shift

    UK Oil & Gas Renames as UK Energy Group Following Strategy Shift

    UK Oil & Gas PLC has changed its name to UK Energy Group PLC (LSE:UKOG) as the company shifts its focus from UK onshore oil and gas towards geological hydrogen storage and related clean power activities.

    The company’s strategy is centred on hydrogen storage projects being progressed through its subsidiary, UK Energy Storage Ltd. UK Energy Group also said its strategy allows for potential expansion into international energy ventures.

    The name change is being reflected on the London Stock Exchange through a new ticker and corporate website. The company’s ISIN remains unchanged.

    UK Energy Group said the rebranding does not affect existing shareholder rights, while current share certificates remain valid.

    The change follows the company’s exit from the UK onshore oil and gas segment and is intended to align its corporate and market identity with its current energy activities.

    More about UK Energy Group PLC

    UK Energy Group PLC, formerly UK Oil & Gas PLC, is an energy company focused on geological hydrogen storage and associated clean power projects.

    Its hydrogen storage activities are being developed through UK Energy Storage Ltd.

    Following its move away from UK onshore oil and gas, the company is concentrating on hydrogen storage infrastructure while retaining the option to pursue energy projects internationally.

  • INPP H1 NAV Per Share Rises 1.3% to 153.4p

    INPP H1 NAV Per Share Rises 1.3% to 153.4p

    International Public Partnerships (LSE:INPP) reported a 1.3% increase in net asset value per share to 153.4p for the six months ended 30 June 2026.

    The infrastructure investment company reported an annualised total NAV return of 8.2%, while portfolio cash flows covered dividends 1.3 times during the period.

    INPP said 99% of portfolio revenues are supported by long-term contracted or regulated arrangements. The company also reported inflation linkage across its portfolio.

    The board reaffirmed its progressive dividend targets for 2026 and 2027.

    Capital Recycling Exceeds £440 Million Since Mid-2023

    INPP has realised more than £440 million from asset disposals at or above their respective net asset values since mid-2023.

    Over the same period, the company has invested or committed approximately £480 million to assets with expected returns above 11%.

    Planned deployments include investments in Sizewell C, BeNEX and the Moray West offshore transmission owner project.

    The company has also extended its share buyback programme to £225 million. INPP said shares repurchased under the programme have contributed to an increase in NAV per share.

    Across the existing portfolio, the company reported asset availability above its targets. Its Tideway investment also reached project milestones during the period.

    INPP decided not to provide further equity funding to fibre network operator toob, citing conditions in the UK digital infrastructure market.

    More about International Public Partnerships

    International Public Partnerships Limited is a FTSE 250-listed infrastructure investment company.

    Its portfolio includes regulated utilities, public-private partnerships and operating infrastructure businesses across sectors including energy, transport, education and digital networks.

    The company invests primarily in infrastructure assets with long operating lives and contracted or regulated revenue arrangements. Its investment approach also includes capital recycling through asset disposals and subsequent deployment into existing or new infrastructure investments.