Author: Fiona Craig

  • Wall Street Futures Mixed as Investors Await Fed Announcement and Major AI Earnings: Dow Jones, S&P, Nasdaq

    Wall Street Futures Mixed as Investors Await Fed Announcement and Major AI Earnings: Dow Jones, S&P, Nasdaq

    US stock index futures were mixed on Wednesday ahead of the Federal Reserve’s monetary policy announcement and quarterly results from Alphabet and Microsoft. Investors were weighing the outlook for artificial intelligence investment against the possibility of higher borrowing costs, while a sharp increase in earnings at SK Hynix highlighted continued demand for advanced semiconductor technology.

    The upcoming financial reports from major technology companies are expected to provide further evidence of whether substantial spending on AI infrastructure is translating into stronger revenue and profitability.

    US Futures Trade Unevenly After Technology-Led Gains

    At 04:02 ET (08:02 GMT), futures on the S&P 500 were 10 points higher, representing a gain of 0.1%. Nasdaq 100 futures advanced 173 points, or 0.6%, while Dow Jones futures fell 117 points, equivalent to 0.2%.

    The moves followed a positive session for US equities, with the Nasdaq Composite rising 1.18% as technology stocks led gains.

    Recent announcements involving financing for artificial intelligence companies helped support sentiment, alongside Anthropic’s filing for an initial public offering earlier in the week.

    The developments provided some reassurance to investors concerned about the funding requirements associated with expanding data centre capacity and AI computing infrastructure.

    Vital Knowledge analysts said the latest financing activity demonstrated continued investor willingness to support the sector.

    “[I]nvestors continue to celebrate the AI funding announcements that hit the tape over the last 36 hours […] as these demonstrate that plenty of money still exists to underwrite the data center bonanza,” the analysts wrote.

    The firm also described the corporate earnings season as broadly “decent” so far, citing resilient demand, cost management and higher selling prices. Approximately one-third of US quarterly reports have been published.

    Alphabet and Microsoft Set to Provide AI Spending Updates

    Alphabet (NASDAQ:GOOG) and Microsoft (NASDAQ:MSFT) are due to release their quarterly results after Wednesday’s closing bell.

    Both companies have committed substantial resources to artificial intelligence, cloud computing and the infrastructure required to operate increasingly complex computing systems.

    Their financial reports will be closely examined for evidence that this investment is supporting revenue growth, particularly within cloud services.

    Investors will also monitor management commentary on future capital expenditure, including spending on data centres and specialised semiconductor equipment.

    Alphabet, Microsoft and Amazon (NASDAQ:AMZN), which reports on Thursday, are collectively planning capital expenditure of up to $600 billion this year.

    The scale of the spending has made returns on investment an increasingly important issue for shareholders.

    While continued investment may indicate expectations of future demand, higher spending also increases the financial returns needed to justify the projects.

    Meta’s Market Reaction Illustrates Capital Expenditure Concerns

    Meta Platforms (NASDAQ:META) provided a recent example of investor sensitivity to rising AI infrastructure costs.

    The company reported strong underlying business performance earlier in October but faced selling pressure after increasing its spending plans.

    Meta shares declined following the announcement and were more than 4% lower for the year at the time of the report.

    Its capital expenditure approached $34 billion during a single quarter.

    Jake Behan, Head of Capital Markets at Direxion, said the market is placing greater emphasis on the relationship between AI spending and financial returns.

    “The more skeptical the market gets about AI returns, the harder it becomes to justify today’s pace of spending. Meta is a good example: the core business was shown to be strong, but with capex hitting nearly $34 billion in a single quarter, the market increasingly needs to see the ROI from that investment,” Behan said.

    The forthcoming results from Alphabet and Microsoft could help investors assess whether similar concerns apply across the wider technology sector.

    SK Hynix Reports 632% Increase in Operating Profit

    South Korean semiconductor manufacturer SK Hynix (NASDAQ:SKHY) reported quarterly earnings ahead of expectations on Wednesday.

    Operating profit for the three months ended September 30 increased 632% year-on-year to 83.33 trillion won, compared with a Bloomberg consensus estimate of 77.5 trillion won.

    Quarterly revenue rose 328% to a record 104.615 trillion won, while net income increased 216% to 39.78 trillion won.

    The results were accompanied by a rise of more than 10% in the company’s shares during trading in Seoul.

    SK Hynix also announced plans to return 100 trillion won, approximately $75.5 billion, to shareholders during the year.

    The company is a major supplier of memory semiconductors used in high-performance computing and artificial intelligence systems.

    Its results provided evidence of continued demand for components used in expanding AI infrastructure.

    AI Hardware Growth Raises Questions About Future Returns

    The performance of SK Hynix highlighted the financial benefits that some semiconductor suppliers are receiving from investment in artificial intelligence.

    Expanding AI systems requires substantial computing resources, including advanced memory, processors and data centre infrastructure.

    Companies supplying these technologies can benefit directly from increased spending by cloud service providers and other technology groups.

    For investors, however, strong demand for hardware represents only one part of the financial outlook for artificial intelligence.

    The companies purchasing and deploying this equipment must also demonstrate that their investments can generate sufficient revenue and profitability over time.

    This issue is expected to feature prominently in the latest earnings reports from major US technology companies.

    Federal Reserve Rate Decision Takes Centre Stage

    The Federal Reserve is expected to keep interest rates unchanged at its Wednesday meeting.

    The anticipated pause follows a rate increase in September, the first since 2023.

    Although markets expect no immediate adjustment, interest rate futures indicate an approximately 75% probability of another increase at the December meeting.

    Investors will examine comments from Fed Chair Kevin Warsh for indications of how the central bank is assessing persistent inflation and the possibility of additional monetary tightening.

    Warsh has generally avoided providing detailed forward guidance, potentially limiting the clarity of any signals concerning the next policy decision.

    Some Federal Reserve officials have nevertheless suggested that further increases may be necessary to address inflationary pressures.

    Monetary Tightening Could Influence Technology Valuations

    Higher interest rates have implications for companies undertaking large investment programmes.

    Borrowing costs can affect the economics of financing data centres, semiconductor facilities and other infrastructure supporting artificial intelligence.

    They also influence the returns investors require when evaluating long-term projects.

    Direxion’s Jake Behan said additional monetary tightening could “raise the cost of funding the AI buildout while simultaneously raising the hurdle for the returns needed to justify it.”

    This creates a potential challenge for technology companies committing large amounts of capital before the full financial benefits of their investments become clear.

    The Federal Reserve’s policy outlook could therefore influence investor reactions to upcoming technology earnings, particularly if companies announce further increases in capital expenditure.

    Higher Oil Prices Complicate the Inflation Outlook

    Energy prices remain an important consideration for US monetary policy.

    Crude oil has risen substantially since the conflict involving Iran began in late February, with disruptions to Middle Eastern energy supplies affecting international markets.

    Higher oil prices have increased gasoline and diesel costs, creating the possibility of additional inflationary pressures through transportation and distribution expenses.

    Economists are monitoring whether the increase in energy costs is spreading to other areas of the economy.

    Brent crude futures were up 1.2% at $115.29 per barrel in the latest figures reported.

    Persistent energy-related inflation could influence the Federal Reserve’s assessment of whether further interest rate increases are required.

    US Report Raises Further Middle East Concerns

    Diplomatic efforts aimed at reducing tensions involving Iran have been accompanied by continued uncertainty about the regional security situation.

    The Wall Street Journal reported that US officials had warned Gulf Arab countries to prepare for the possibility of a short, intensive military campaign after the November US midterm elections.

    The report added to concerns about potential further disruption to Middle Eastern energy production and transportation.

    The conflict has already contributed to higher oil prices, which remain relevant to inflation expectations and central bank policy decisions.

    Additional disruptions could increase uncertainty for energy markets and businesses exposed to fuel costs.

    Market Outlook

    US equity futures were mixed ahead of a series of announcements likely to influence expectations for technology spending and interest rates.

    Alphabet and Microsoft will report after Wednesday’s market close, followed by Amazon on Thursday, with investors focused on cloud growth and the returns generated by substantial AI infrastructure investments.

    SK Hynix’s results demonstrated strong demand for advanced memory semiconductors, with operating profit rising 632% and revenue increasing 328%.

    The Federal Reserve is expected to maintain interest rates, although markets continue to price the possibility of another increase in December.

    The interaction between technology capital expenditure, financing costs and energy-related inflation will remain important as investors assess the outlook for US equities.
  • Market Open: Unilever Sales Growth, Aston Martin Revenue Rises

    Market Open: Unilever Sales Growth, Aston Martin Revenue Rises

    FTSE 100 falls as Unilever raises its sales outlook and Aston Martin reports higher revenue. Brent crude gains amid Middle East supply concerns.

    Market Overview

    The FTSE 100 declined 0.31 per cent to 10,652.96 in early trading on Wednesday, as investors assessed corporate earnings and awaited the UK Budget. Unilever and GSK weighed on sentiment despite reporting quarterly growth. European markets were mixed, with the Euronext 100 down 0.24 per cent from its opening level to 1,871.79, while Germany’s DAX fell 0.13 per cent to 25,556.82. Wall Street closed higher on Tuesday, with the Nasdaq rising to 26,477.81 and the S&P 500 advancing to 7,722.60. Investors remained cautious ahead of the Federal Reserve’s interest rate decision and earnings from major US technology companies.

    Commodity markets were mixed, with copper and gold declining slightly, while Brent crude advanced amid renewed Middle Eastern supply concerns following a reported attack on a Saudi Arabian refinery. Natural gas remained unchanged. Bitcoin strengthened against sterling, while the pound weakened against the US dollar, euro, Japanese yen and Australian dollar but gained against the Swiss franc. Attention remained focused on the Federal Reserve’s policy outlook, UK fiscal developments and geopolitical risks affecting energy markets.


    Market Numbers

    FTSE 100: Down (-0.31%), 10,652.96
    Euronext 100: Down (-0.24%), 1,871.79
    DAX: Down (-0.13%), 25,556.82
    NASDAQ: Up, 26,477.81
    S&P 500: Up, 7,722.60


    In the Headlines

    Sales Growth – Unilever (LSE:ULVR)
    Consumer goods group Unilever reported 5.2 per cent underlying sales growth in the third quarter, supported by higher volumes across its Beauty & Wellbeing, Personal Care and Home Care divisions. The company raised its full-year underlying volume growth outlook to at least 3 per cent, although its shares came under pressure in early trading.

    Revenue Growth – Aston Martin (LSE:AML)
    Luxury carmaker Aston Martin reported a 36 per cent increase in third-quarter revenue to £388.7 million, supported by deliveries of its Valhalla supercar and higher average selling prices. The company maintained its 2026 financial guidance, with Valhalla deliveries contributing to its revenue mix and margins.


    Currencies (vs GBP)

    USD: Up (+0.09%), $1.3294
    CHF: Down (-0.06%), Fr.1.1037
    EUR: Up (+0.08%), €1.1949
    JPY: Up (+0.28%), ¥209.69
    AUD: Up (+0.12%), $1.8901
    Bitcoin (BTC/GBP): Up (+2.19%), £61,315.10


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Up
    Natural Gas: Unchanged

  • European Stocks Trade Lower as Bank Earnings Provide Support Ahead of Fed Decision and US Technology Results: DAX, CAC, FTSE100

    European Stocks Trade Lower as Bank Earnings Provide Support Ahead of Fed Decision and US Technology Results: DAX, CAC, FTSE100

    European stock markets traded cautiously on Wednesday as investors awaited the Federal Reserve’s interest rate decision and quarterly earnings from major US technology companies. Stronger-than-expected results from several leading European banks provided some support, although the broader market struggled to establish a clear direction.

    The pan-European STOXX 600 index declined 0.1%, while Germany’s DAX, France’s CAC 40 and Italy’s FTSE MIB remained broadly unchanged.

    London’s FTSE 100 fell 0.2%, while Spain’s IBEX 35 recorded a larger decline of 1%.

    Investors were also preparing for quarterly results from Alphabet (NASDAQ:GOOG) and Microsoft (NASDAQ:MSFT), with particular attention on cloud computing revenue, artificial intelligence investment and the outlook for technology infrastructure spending.

    European Equity Markets Show Limited Movement

    European equities remained close to unchanged levels as investors assessed corporate earnings alongside the outlook for monetary policy.

    The STOXX 600 slipped 0.1%, reflecting modest weakness across the broader European market.

    Germany’s DAX, France’s CAC 40 and Italy’s FTSE MIB traded broadly flat, while the FTSE 100 declined 0.2%.

    Spain’s IBEX 35 underperformed, falling 1%.

    The mixed performance reflected caution ahead of the Federal Reserve’s announcement later in the session.

    Investors were also awaiting financial results from major US technology companies, which could influence sentiment towards European semiconductor and technology shares.

    BNP Paribas Shares Rise Following Stronger-Than-Expected Profit

    BNP Paribas (EU:BNP) gained 1% after reporting third-quarter earnings that exceeded market expectations.

    France’s largest banking group recorded an increase in quarterly profit, supported by activity in its corporate and investment banking operations.

    The performance reflected contributions from businesses serving corporate and institutional clients.

    The results provided support for the bank’s shares during a session characterised by limited movement in the broader European market.

    The supplied earnings update did not specify the bank’s quarterly profit figure or the extent to which results exceeded analysts’ forecasts.

    Standard Chartered Advances 4.4% After Earnings Beat

    Standard Chartered (LSE:STAN) rose 4.4% after reporting quarterly results ahead of consensus expectations.

    The banking group benefited from strong trading revenues within its global markets division.

    Its wealth management business also recorded accelerating inflows, contributing to the overall performance.

    The combination of trading activity and wealth management growth supported investor interest in the shares.

    Standard Chartered was among the stronger performers highlighted in the European banking sector during Wednesday’s session.

    The reported results demonstrated continued contributions from the group’s financial markets and wealth management operations.

    UBS Reports $2.69 Billion Quarterly Net Profit

    Swiss banking group UBS (NYSE:UBS) reported third-quarter net profit of $2.69 billion.

    The result represented an increase of 8% compared with the corresponding period of the previous year.

    Quarterly profit was broadly in line with the company-compiled consensus estimate of $2.71 billion.

    The figures indicated year-on-year earnings growth, although the result was slightly below the reported consensus forecast.

    UBS joined BNP Paribas and Standard Chartered in publishing quarterly financial results that contributed to investor assessments of the European banking sector.

    The banking updates helped limit broader market weakness, but did not produce a sustained advance across European equity indices.

    Dassault Systèmes Raises Full-Year Revenue Growth Outlook

    Outside the financial sector, Dassault Systèmes (EU:DSY) increased its revenue growth guidance for 2026.

    The French enterprise software company now expects full-year revenue growth of between 4% and 5%.

    The revised outlook provided an additional corporate development for investors assessing European technology shares.

    Dassault Systèmes operates in the enterprise software market, supplying technology used in product design, engineering and industrial applications.

    The updated forecast came ahead of quarterly earnings announcements from major US technology companies, which were expected to influence sentiment across the global sector.

    Federal Reserve Expected to Leave Interest Rates Unchanged

    The Federal Open Market Committee is expected to maintain its benchmark interest rate range at 3.75% to 4.00% when it announces its decision on Wednesday.

    Although no immediate change is anticipated, investors remain focused on the possibility of further monetary tightening before the end of the year.

    According to the interest rate futures pricing cited in the market report, traders assigned an implied probability of approximately 80% to a 25-basis-point increase at the Federal Reserve’s December meeting.

    Elevated crude oil prices and resilient US economic indicators have contributed to concerns about persistent inflation.

    Higher energy costs can influence consumer prices and business expenses, potentially complicating the central bank’s efforts to control inflation.

    The Federal Reserve’s assessment of these developments will therefore be important for expectations surrounding future interest rate decisions.

    Investors Await Kevin Warsh’s Monetary Policy Comments

    Federal Reserve Chair Kevin Warsh’s press conference following the interest rate announcement will be closely monitored.

    Investors will look for indications of how policymakers are assessing inflation risks associated with higher energy prices.

    Attention will also focus on whether the central bank believes current interest rates are sufficient to contain inflationary pressures.

    The possibility of a December rate increase remains a significant consideration for financial markets.

    Any changes in expectations for US interest rates could influence bond yields, currencies and equity valuations internationally.

    The announcement will also provide a reference point for European investors ahead of the European Central Bank’s policy decision on Thursday.

    ECB Decision Adds to European Market Caution

    The European Central Bank is scheduled to announce its latest monetary policy decision on Thursday.

    Investors are assessing the outlook for eurozone interest rates amid persistent inflation and fiscal uncertainty in France.

    The ECB faces the challenge of balancing inflation control against the effects of borrowing costs on economic activity.

    Developments in French public finances have also contributed to scrutiny of sovereign debt markets.

    The Federal Reserve’s decision and accompanying commentary could influence broader financial market expectations ahead of the ECB announcement.

    Together, the two central bank meetings represent important events for European equities, bonds and currencies.

    Alphabet and Microsoft Earnings in Focus

    Alphabet (NASDAQ:GOOG) and Microsoft (NASDAQ:MSFT) are scheduled to report quarterly results after the US stock market closes on Wednesday.

    The announcements are expected to provide further information about demand for cloud computing services and the financial effects of investment in artificial intelligence.

    Both companies have committed substantial resources to expanding data centres, computing infrastructure and specialised semiconductor technology.

    Investors will examine whether this spending is contributing to stronger cloud revenue growth.

    The relationship between infrastructure investment and revenue generation remains an important consideration for technology sector valuations.

    The results could also influence expectations for future capital expenditure across the global technology industry.

    AI Infrastructure Spending Remains Important for European Semiconductor Stocks

    European semiconductor companies remain closely linked to investment decisions made by major US technology groups.

    ASML (EU:ASML), ASM International (EU:ASM) and BE Semiconductor Industries (EU:BESI) are among the European companies exposed to demand for semiconductor manufacturing equipment and related technologies.

    Investment in data centres, high-performance computing and artificial intelligence infrastructure can influence demand throughout the semiconductor supply chain.

    Strong cloud computing growth and sustained infrastructure spending could support expectations for equipment demand.

    Conversely, weaker-than-expected results or indications of reduced capital expenditure could lead investors to reassess growth expectations for semiconductor suppliers.

    The forthcoming Alphabet and Microsoft announcements are therefore relevant beyond the US technology sector.

    Outlook for European Equity Markets

    European stocks traded with limited direction on Wednesday as investors balanced encouraging banking results against uncertainty surrounding monetary policy and US technology earnings.

    The STOXX 600 declined 0.1%, while major continental European indices remained broadly unchanged.

    BNP Paribas gained 1% and Standard Chartered advanced 4.4% following stronger-than-expected quarterly results, while UBS reported an 8% increase in net profit to $2.69 billion.

    Dassault Systèmes also raised its full-year revenue growth guidance to between 4% and 5%.

    The Federal Reserve is expected to maintain interest rates at 3.75% to 4.00%, although markets are pricing the possibility of a further increase in December.

    Attention will subsequently turn to Alphabet and Microsoft earnings and the European Central Bank’s policy announcement.

    These developments will help shape expectations for interest rates, corporate profitability and technology investment across European financial markets.

  • European Gas Prices Reach Highest Levels Since 2022 as Houthi Attacks Raise Supply Concerns

    European Gas Prices Reach Highest Levels Since 2022 as Houthi Attacks Raise Supply Concerns

    European natural gas prices climbed to their highest levels since 2022 on Wednesday as renewed attacks on Saudi Arabian energy infrastructure increased concerns about global fuel supplies. The latest developments in the Middle East added pressure to European energy markets ahead of the winter heating season, while disruptions to liquefied natural gas shipments continued to affect supply availability.

    The benchmark Dutch TTF front-month natural gas contract rose 1.2% to €97.35 per megawatt-hour (MWh), its highest level in approximately four years.

    In the United Kingdom, NBP natural gas futures advanced 1.5% to 241.00 pence per therm, extending their gains for a sixth consecutive trading session.

    The price increases followed reports of further missile and drone attacks by Yemen’s Iran-aligned Houthi movement against Saudi Arabian energy facilities and transport infrastructure.

    Dutch TTF and UK Natural Gas Prices Continue Rising

    European wholesale gas markets recorded further gains as traders assessed the potential consequences of escalating tensions in the Middle East.

    The Dutch TTF contract, widely used as the reference price for continental European natural gas, increased 1.2% to €97.35/MWh.

    The British NBP benchmark rose 1.5% to 241.00 pence per therm, marking its sixth successive session of gains.

    Both benchmarks reached levels last recorded in 2022, when European energy markets experienced substantial price volatility.

    The latest increases reflect concerns about the availability of imported fuel, particularly liquefied natural gas, as Europe approaches a period of higher seasonal demand.

    Houthi Attacks Target Saudi Energy Infrastructure

    The latest rise in natural gas prices followed renewed attacks on Saudi Arabian energy facilities attributed to Yemen’s Houthi movement.

    On Tuesday, the group announced that it had targeted the Ras Tanura oil refinery with a ballistic missile.

    Ras Tanura is one of Saudi Arabia’s principal refining and crude oil export facilities, making it an important component of the country’s energy infrastructure.

    The reported attack followed earlier strikes during the week against pumping stations along Saudi Arabia’s East-West Crude Oil Pipeline.

    Riyadh’s King Khalid International Airport was also identified among the targets.

    The developments increased concerns about the security of energy infrastructure and transport networks across the region.

    The reported attacks came amid continuing military tensions involving Iran and other countries in the Middle East.

    Diplomatic Talks Face Renewed Challenges

    The escalation followed diplomatic discussions in Tehran earlier in the week.

    On Monday, delegations from Saudi Arabia, Turkey and Pakistan met senior Iranian officials to discuss efforts aimed at reducing regional tensions.

    Joint statements following the discussions confirmed an agreement to continue dialogue focused on restoring peace and security.

    The meetings had raised expectations that diplomatic engagement could help reduce the risks affecting regional energy production and transportation.

    However, the subsequent announcement of attacks on Saudi infrastructure renewed concerns about the prospects for a sustained reduction in hostilities.

    Energy markets responded by reassessing the risks associated with continued disruptions to production facilities, pipelines and shipping routes.

    Saudi East-West Pipeline Remains Important Alternative Route

    Saudi Arabia’s East-West Crude Oil Pipeline has become particularly important amid disruption to commercial shipping through the Strait of Hormuz.

    The pipeline extends approximately 1,200 kilometres across Saudi Arabia, transporting crude oil from eastern production areas towards export facilities on the Red Sea.

    This infrastructure allows some Saudi oil exports to avoid the Strait of Hormuz, a major shipping route connecting the Persian Gulf with international markets.

    Disruption to maritime traffic through the strait has increased the importance of alternative transportation corridors.

    Attacks on pumping stations serving the East-West Pipeline therefore raise concerns about the reliability of routes intended to reduce dependence on the waterway.

    Although the pipeline primarily transports crude oil rather than natural gas, disruptions to regional energy infrastructure can influence wider fuel markets by increasing uncertainty over supply and transportation.

    Strait of Hormuz Disruption Affects LNG Shipments

    The continuing conflict involving Iran has severely disrupted commercial navigation through the Strait of Hormuz.

    The waterway is an important route for international energy shipments, including liquefied natural gas exports from the Persian Gulf.

    Restrictions and security concerns affecting maritime traffic have complicated the movement of LNG cargoes towards international markets.

    Some LNG carriers have been forced to use longer alternative shipping routes around Africa via the Cape of Good Hope.

    According to the reported market conditions, these diversions have extended transit times by approximately 10 to 14 days.

    Longer journeys increase shipping requirements and freight costs, while delaying the arrival of cargoes at their destinations.

    For European energy buyers, the disruption has created additional difficulties in securing replacement supplies ahead of winter.

    European LNG Deliveries Reportedly Fall Sharply

    The disruption to established shipping routes has contributed to a substantial reduction in LNG deliveries to European import terminals.

    According to the figures cited in the market report, spot LNG deliveries to European regasification facilities were nearly 80% below their levels a year earlier.

    The decline reflects the combined effects of shipping disruptions, longer transportation routes and constraints on available cargoes.

    European utilities rely on LNG imports as an important source of natural gas, particularly when pipeline supplies are insufficient to meet demand.

    Reduced deliveries can increase competition for available shipments and place upward pressure on wholesale gas prices.

    The reported reduction in spot cargoes is particularly relevant as European energy demand begins to increase during the colder months.

    EU Gas Storage Falls Below Seasonal Average

    European underground natural gas inventories are also below their typical levels for late October.

    Data attributed to Gas Infrastructure Europe indicates that storage facilities across the European Union were approximately 74.6% full.

    This compares with a five-year seasonal average of around 86%.

    During the comparable period in the previous year, storage levels exceeded 95%.

    The reported October 2026 inventory level represents the lowest regional storage position for that point in the year in records dating back to 2009.

    The difference between current inventories and historical levels indicates that Europe is entering the winter heating period with a smaller stored gas reserve than usual.

    Lower storage levels can increase sensitivity to supply interruptions, particularly when imported LNG volumes are constrained.

    Colder Weather Could Increase Early Winter Demand

    Weather forecasts have added to concerns about European gas availability.

    Meteorological services have indicated the possibility of below-seasonal-average temperatures across parts of Northern and Central Europe in early November.

    Colder conditions would increase demand for natural gas used in residential and commercial heating.

    Utilities could therefore begin withdrawing gas from underground storage facilities earlier or at a faster rate than under milder weather conditions.

    With EU storage already below its five-year seasonal average, stronger heating demand could place additional pressure on inventories.

    The extent of that pressure will depend on actual temperatures, industrial gas consumption and the availability of additional imports.

    Energy Security Remains a Focus for European Markets

    The combination of geopolitical tensions, shipping disruptions and lower storage inventories has increased uncertainty in European natural gas markets.

    Continued attacks on Middle Eastern energy infrastructure could complicate efforts to restore confidence in regional supply routes.

    At the same time, longer LNG shipping journeys may affect the timing and cost of deliveries to European import terminals.

    The situation highlights Europe’s continuing exposure to developments in international energy markets, particularly during periods of elevated winter demand.

    Wholesale gas prices will remain sensitive to changes in Middle Eastern security conditions, LNG availability and European weather forecasts.

    Outlook for European Natural Gas Prices

    European gas benchmarks reached their highest levels since 2022 as traders assessed renewed threats to Saudi Arabian energy infrastructure and continued disruption to LNG shipments.

    The Dutch TTF contract advanced to €97.35/MWh, while UK NBP futures rose to 241.00 pence per therm.

    Supply concerns have been compounded by EU underground gas storage levels of approximately 74.6%, substantially below the five-year seasonal average of 86%.

    Forecasts of colder weather in early November could further increase demand for heating fuel and accelerate withdrawals from storage.

    The direction of European gas prices will depend on developments in Middle Eastern hostilities, the restoration of shipping routes, LNG import availability and the severity of winter weather.

  • Eurozone Bond Yields Rise as French Debt Comes Under Pressure Ahead of Fed and ECB Decisions

    Eurozone Bond Yields Rise as French Debt Comes Under Pressure Ahead of Fed and ECB Decisions

    Eurozone government bond yields moved higher on Wednesday as French sovereign debt resumed its decline in price following a brief recovery prompted by Moody’s credit rating decision. German bond yields also increased modestly after consumer confidence data pointed to continued pressure on household finances, while investors awaited monetary policy announcements from the Federal Reserve and European Central Bank.

    France’s benchmark 10-year government bond yield rose to 4.965%, reversing part of the improvement recorded on Monday after Moody’s affirmed the country’s Aa3 sovereign credit rating. The two-year French yield also increased, reaching 3.768%.

    German government bonds weakened slightly, with the two-year Bund yield advancing to 3.082% and the 10-year yield reaching 3.382%.

    The movements came amid continuing concerns about government borrowing requirements, inflation and the outlook for interest rates in major economies.

    French Bond Yields Rise Despite Moody’s Rating Confirmation

    French government bonds came under renewed pressure after a short-lived recovery earlier in the week.

    The yield on France’s benchmark 10-year OAT rose to 4.965%, while the two-year yield climbed to 3.768%.

    Bond yields move inversely to prices, meaning the increases reflected renewed selling pressure on French sovereign debt.

    The movement followed Moody’s decision to maintain France’s sovereign credit rating at Aa3, which had initially supported demand for the country’s bonds.

    However, investors continued to assess the fiscal challenges facing the French government.

    France’s budget deficit stands at approximately 5.4% of gross domestic product, while President Emmanuel Macron’s administration faces parliamentary difficulties in securing support for fiscal consolidation measures.

    Continuing public demonstrations have added to the political challenges surrounding proposed budget adjustments.

    These developments have contributed to investor scrutiny of France’s borrowing requirements and longer-term debt sustainability.

    Investors Focus on Government Debt Sustainability

    The renewed increase in French bond yields reflects broader concerns about fiscal conditions across sovereign debt markets.

    Investors are assessing whether governments can maintain access to financing at manageable costs while addressing budget deficits and existing debt obligations.

    Louis Gargour, Chief Investment Officer at Market Securities Wealth, highlighted the growing importance of fiscal considerations.

    “Long-term fiscal sustainability is becoming an increasingly important consideration for investors,” Gargour said.

    He added: “High debt burdens, budgetary pressures, and growing social tensions raise legitimate questions about the long-term trajectory of government finances. Markets are increasingly focused on fiscal discipline and governments’ ability to refinance large debt stocks without materially higher borrowing costs.”

    Higher government bond yields can increase the cost of issuing new debt and refinancing existing obligations as they mature.

    For France, the combination of a substantial fiscal deficit and political disagreements over budget measures remains an important consideration for bond investors.

    German Bund Yields Increase as Consumer Confidence Weakens

    German government bond yields also moved higher during Wednesday’s trading session.

    The yield on the two-year Bund increased to 3.082%, while the benchmark 10-year yield edged up to 3.382%.

    The movements followed consumer confidence figures indicating that German households remain cautious about their financial outlook.

    The forward-looking consumer climate index, compiled by the Nuremberg Institute for Market Decisions and GfK, declined to -30.8 points for November from -30.6 in October.

    The reading was slightly stronger than the -30.9 forecast in a Reuters survey, but still indicated weak consumer sentiment.

    The survey pointed to continued concerns about household purchasing power and elevated energy costs ahead of the winter period.

    These pressures remain relevant to expectations for German consumer spending and economic growth.

    Energy Costs Continue to Affect German Households

    The German consumer confidence figures highlighted the continuing impact of elevated prices on household finances.

    Energy expenses remain a particular concern as the winter period approaches and demand for heating increases.

    Persistent price pressures have limited expectations for improvements in real household income.

    The decline in the consumer climate index suggests that consumers remain reluctant to adopt a more positive assessment of their financial circumstances.

    Weak consumer confidence can affect household expenditure and, consequently, broader economic activity.

    The latest survey therefore adds to the economic information being considered by investors ahead of the European Central Bank’s monetary policy decision.

    Federal Reserve Expected to Maintain Interest Rates

    The Federal Open Market Committee is expected to leave its benchmark interest rate range unchanged at 3.75% to 4.00% when it announces its decision later on Wednesday.

    Despite expectations for no immediate change, short-term interest rate markets are pricing an implied probability of approximately 80% for a 25-basis-point increase at the December meeting.

    Investors will focus on Federal Reserve Chair Kevin Warsh’s press conference for indications of how policymakers are assessing inflation and the economic effects of higher energy prices.

    Particular attention will be paid to the potential for energy costs to influence prices across other sectors of the economy.

    The central bank’s assessment of these secondary inflation effects could influence expectations for future monetary policy.

    The decision will also provide an important reference point for global bond markets ahead of the ECB’s announcement.

    ECB Expected to Hold Deposit Rate at 2.50%

    The European Central Bank is expected to maintain its deposit facility rate at 2.50% when its Governing Council meets on Thursday.

    The anticipated decision follows interest rate increases in June and September.

    Eurozone headline inflation remains at 3.8%, presenting a challenge for policymakers seeking to contain price pressures without placing additional strain on economic activity.

    Government borrowing costs have also remained elevated in several eurozone countries.

    These conditions require the ECB to consider the effects of monetary tightening on inflation, economic growth and financial markets.

    Investors will examine President Christine Lagarde’s comments for indications of whether the central bank believes current financial conditions are restrictive enough to delay another interest rate increase.

    Market attention is particularly focused on the possibility of a further 25-basis-point rise in December.

    Monetary Policy Outlook Influences European Bond Markets

    The Federal Reserve and ECB decisions are taking place against a backdrop of persistent inflation concerns and elevated sovereign borrowing costs.

    In the United States, investors are assessing whether energy-related price pressures could lead to additional monetary tightening.

    In the eurozone, the ECB faces similar questions while also considering the financial conditions of member states with substantial government borrowing requirements.

    Higher interest rates generally increase the cost of financing for governments, businesses and households.

    They can also affect the market value of existing fixed-income securities.

    The outlook for monetary policy therefore remains an important factor influencing bond yields across European markets.

    Israeli Government Bond Yield Rises Following Election

    Outside the eurozone, Israeli government bond yields increased sharply following Tuesday’s parliamentary election.

    Exit polls indicated that neither Prime Minister Benjamin Netanyahu’s coalition nor the opposition bloc associated with former military chief Gadi Eisenkot had secured a clear majority in the 120-member Knesset.

    The results pointed to the possibility of extended negotiations over the formation of a governing coalition.

    The political uncertainty comes amid an ongoing regional military conflict.

    Israel’s benchmark 10-year government bond yield rose to 4.067%, recording its largest single-session increase in nearly a month.

    The yield had previously reached a one-month low earlier in the week.

    The increase reflected renewed pressure on Israeli sovereign bonds as investors assessed the implications of the election outcome and the wider security environment.

    Outlook for Sovereign Bond Markets

    Eurozone government bond yields moved higher as investors reassessed fiscal risks and awaited monetary policy decisions from the Federal Reserve and ECB.

    French bonds remained under pressure despite Moody’s decision to maintain the country’s Aa3 rating, with the 10-year yield reaching 4.965%.

    German yields also increased as consumer confidence data indicated continuing pressure from energy costs and weak household income expectations.

    The Federal Reserve is expected to maintain rates at 3.75% to 4.00%, while the ECB is anticipated to hold its deposit rate at 2.50%.

    Investors will monitor central bank communications for indications of whether further tightening may be required to address persistent inflation.

    Fiscal developments in France, economic data from Germany and political uncertainty affecting Israeli debt will also remain relevant to sovereign bond markets.

  • TotalEnergies Acquires 25% Interest in 26 Chevron-Operated Offshore Exploration Blocks in the United States

    TotalEnergies Acquires 25% Interest in 26 Chevron-Operated Offshore Exploration Blocks in the United States

    TotalEnergies (LSE:TTE) has acquired a 25% working interest in 26 offshore exploration leases operated by Chevron in the US Gulf of Mexico, expanding its exploration portfolio through an agreement that also involves the exchange of interests in two additional leases.

    Under the transaction, Chevron will receive a 75% operated interest in two exploration leases previously held by TotalEnergies. These leases are located adjacent to areas where the two energy companies already hold joint exploration interests.

    The agreement covers offshore acreage located between 150 and 250 kilometres from the US coastline, with most of the leases situated in the Green Canyon area.

    The transaction follows an earlier agreement in June 2025, when TotalEnergies acquired interests in 40 Chevron-operated exploration blocks in the region.

    TotalEnergies Expands Gulf of Mexico Exploration Portfolio

    The agreement gives TotalEnergies a 25% working interest in 26 exploration leases operated by Chevron.

    A working interest represents a company’s ownership share in an oil and gas licence, including its entitlement to future production and its responsibility for a corresponding proportion of exploration and development costs.

    Chevron will remain the operator of the 26 leases, retaining responsibility for managing exploration activities.

    The agreement expands TotalEnergies’ participation in offshore exploration opportunities in the United States while maintaining Chevron’s operational role.

    Financial terms of the transaction, including any cash consideration, were not disclosed in the information provided.

    Exploration Acreage Concentrated in Green Canyon and Walker Ridge

    The 26 exploration leases are situated approximately 150 to 250 kilometres offshore in the Gulf of Mexico.

    Twenty-four leases are located in the Green Canyon area, while the remaining two are in Walker Ridge.

    Both areas are established offshore exploration regions containing geological formations associated with oil and gas resources.

    TotalEnergies stated that the leases target proven geological plays, providing access to exploration opportunities within established petroleum systems.

    However, the agreement relates to exploration acreage rather than confirmed producing assets.

    No resource estimates, drilling commitments or exploration schedules were disclosed as part of the announcement.

    Chevron Receives 75% Interest in Two TotalEnergies Leases

    As part of the agreement, Chevron will acquire a 75% operated interest in two exploration leases held by TotalEnergies.

    These leases are located next to exploration acreage already held jointly by the companies.

    The arrangement involves an exchange of exploration interests, allowing both companies to adjust their positions within neighbouring offshore areas.

    Chevron will assume the operating role in the two additional leases under the terms of the transaction.

    The companies did not disclose the valuation assigned to the exchanged interests or any associated financial payments.

    Agreement Builds on June 2025 Exploration Transaction

    The latest transaction follows TotalEnergies’ entry into 40 Chevron-operated exploration blocks in June 2025.

    That earlier agreement expanded the French energy company’s participation in US offshore exploration.

    The addition of interests in another 26 leases further extends the relationship between TotalEnergies and Chevron in the Gulf of Mexico.

    The transactions provide TotalEnergies with access to additional exploration acreage while allowing Chevron to continue managing operations.

    The companies have not announced drilling dates or production targets for the newly acquired interests.

    TotalEnergies Targets Additional Exploration Opportunities

    Nicola Mavilla, Senior Vice President for Exploration at TotalEnergies, said the agreement provides access to further exploration prospects.

    Mavilla described the transaction as giving the company access to “a new set of high-impact opportunities.”

    The statement reflects TotalEnergies’ objective of expanding its exploration portfolio in offshore areas with established oil and gas activity.

    Exploration leases provide the right to assess potential hydrocarbon resources, but commercial production depends on successful discoveries, technical evaluations and subsequent investment decisions.

    The company did not provide an estimate of the potential resources associated with the 26 leases.

    Existing Gulf of Mexico Production Interests

    TotalEnergies already holds interests in several producing offshore oil and gas assets in the Gulf of Mexico.

    These include Ballymore, Anchor, Jack and Tahiti.

    The producing assets form part of the company’s existing upstream operations in the United States.

    The newly acquired exploration interests will complement this established presence, although they are at a different stage of development.

    Unlike producing fields, exploration leases do not generate production revenue unless commercially viable discoveries are made and developed.

    The announcement did not indicate whether the new acreage would be developed in connection with any of the company’s existing producing assets.

    US Investment Reaches Nearly $12 Billion Since 2022

    TotalEnergies has operated in the United States since 1957 and maintains activities across oil, natural gas and electricity.

    The company reported that it has invested nearly $12 billion in the country since 2022.

    These investments cover oil operations, liquefied natural gas and electricity generation.

    The latest offshore exploration agreement adds to the company’s existing US energy portfolio.

    TotalEnergies did not disclose the investment value associated specifically with the newly acquired exploration interests.

    LNG Exports Total 19 Million Tonnes in 2025

    TotalEnergies reported exports of 19 million tonnes of liquefied natural gas from the United States in 2025.

    The company described itself as the largest exporter of US LNG during that year.

    LNG forms an important part of TotalEnergies’ US operations alongside offshore oil and gas exploration and production.

    The company’s activities include participation in the supply and international marketing of natural gas.

    The offshore exploration transaction does not directly change the company’s reported LNG export volumes.

    US Electricity Capacity Reaches 10 Gigawatts

    In addition to its oil and gas operations, TotalEnergies reported installed electricity generation capacity of 10 gigawatts in the United States.

    The electricity business forms part of the company’s broader activities in the American energy market.

    Together with its LNG operations and offshore assets, this capacity illustrates the range of energy activities maintained by TotalEnergies in the country.

    The announcement did not provide a breakdown of the electricity capacity by generation technology.

    Outlook for US Offshore Exploration

    The acquisition of a 25% interest in 26 Chevron-operated exploration leases expands TotalEnergies’ offshore exploration position in the Gulf of Mexico.

    The transaction follows the company’s June 2025 entry into 40 Chevron-operated blocks and adds acreage in the Green Canyon and Walker Ridge areas.

    Chevron will also acquire a 75% operated interest in two neighbouring TotalEnergies leases under the agreement.

    The additional exploration interests provide opportunities for future resource evaluation, although no drilling programme or development timetable has been announced.

    Exploration results and subsequent investment decisions will determine whether the acreage contributes to TotalEnergies’ future oil and gas production.

    More About TotalEnergies

    TotalEnergies is a French integrated energy company operating internationally across oil, natural gas, liquefied natural gas and electricity.

    Its activities include hydrocarbon exploration and production, energy trading, refining, distribution and power generation.

    The company has maintained operations in the United States since 1957, with investments across offshore oil and gas, LNG and electricity.

  • Rémy Cointreau Reports 4.2% Organic Sales Growth in Q2 as Cognac Demand Exceeds Expectations

    Rémy Cointreau Reports 4.2% Organic Sales Growth in Q2 as Cognac Demand Exceeds Expectations

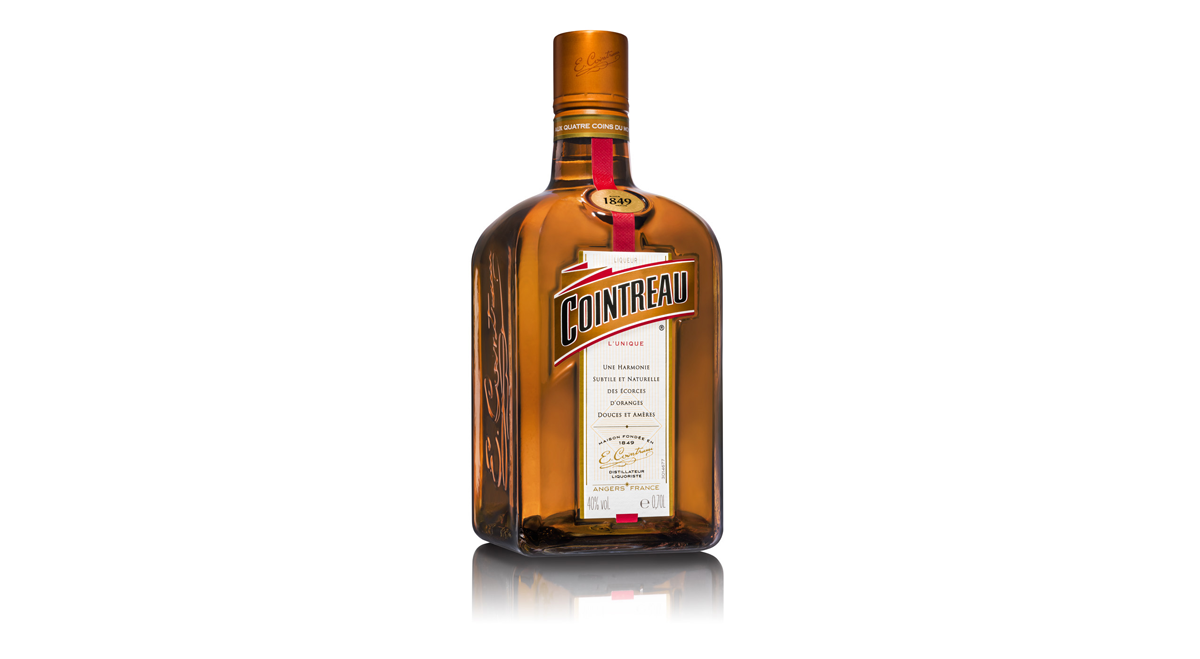
    Rémy Cointreau (EU:RCO) reported stronger-than-expected sales for the second quarter of its 2026-27 financial year, supported by growth in its cognac business across Asia-Pacific, particularly China, while its liqueurs and spirits division continued to face pressure from distribution changes in the United States.

    The French spirits producer recorded organic sales growth of 4.2% for the quarter ended September 2026, exceeding analysts’ expectations of 3.6%. Revenue reached €287.7 million, compared with the consensus forecast of €280.8 million.

    The cognac division recorded organic growth of 12.4%, exceeding market expectations, while liqueurs and spirits revenue declined 7.4% on an organic basis.

    Rémy Cointreau maintained its full-year outlook for a return to sustainable organic sales growth and reaffirmed its objective of achieving a slight improvement in current operating margin.

    Second-Quarter Revenue Exceeds Analyst Forecasts

    Rémy Cointreau generated revenue of €287.7 million during the second quarter, approximately €6.9 million above the analyst consensus.

    Organic revenue growth reached 4.2%, compared with the 3.6% increase anticipated by the market.

    For the first six months of the financial year, revenue totalled €510.9 million, compared with €489.6 million in the corresponding period a year earlier.

    This represented reported revenue growth of 4.4%, while organic growth reached 2.9%.

    The difference between reported and organic growth reflects factors such as currency movements and changes in the reporting perimeter.

    The first-half performance was supported by higher cognac sales, although trading conditions remained uneven across the company’s product categories and geographic markets.

    Cognac Sales Rise 12.4% on Asian Demand

    Rémy Cointreau’s cognac division reported organic revenue growth of 12.4% in the second quarter, ahead of analysts’ expectations of 8.9%.

    The performance was primarily supported by increased shipments to China ahead of the Mid-Autumn Festival.

    The company also reported continued sales momentum across other Asia-Pacific markets.

    The acceleration in shipments contributed to the division’s quarterly performance and helped offset weaker results elsewhere in the business.

    However, the timing of shipments ahead of a major seasonal event is relevant when assessing the sustainability of quarterly growth.

    Rémy Cointreau continues to monitor demand conditions across its principal cognac markets as it progresses through the second half of the financial year.

    Liqueurs and Spirits Revenue Declines 7.4%

    The liqueurs and spirits division reported a 7.4% organic revenue decline during the second quarter.

    The result was weaker than the analyst consensus, which had anticipated a contraction of 4.7%.

    Rémy Cointreau attributed the decline partly to inventory reductions by US distributors following changes to its distribution arrangements.

    These destocking activities affected shipments during the quarter and contributed to the difference between the division’s performance and market expectations.

    The company did not specify when the inventory adjustment process is expected to conclude.

    The contrasting results between cognac and liqueurs and spirits highlight differences in trading conditions across the group’s businesses.

    Tariff Impact Forecast Reduced to €5 Million

    Rémy Cointreau revised its estimate of the impact of tariffs on current operating profit for the 2026-27 financial year.

    The company now expects a negative impact of approximately €5 million, compared with its previous estimate of €20 million.

    The €15 million reduction reflects changes in US import tariffs on European products and refunds relating to the previous financial year.

    US tariffs on European imports declined from 15% to 10%, reducing the expected cost of importing the company’s products into the American market.

    Rémy Cointreau also recognised €6.4 million in tariff refunds relating to the 2025-26 financial year during the first half.

    The company intends to reinvest the approximately €15 million in tariff-related savings into initiatives designed to support future growth.

    As a result, the lower estimated tariff burden does not translate directly into an equivalent improvement in the company’s operating profit outlook.

    Currency Forecast Revised to Positive Contribution

    Rémy Cointreau also updated its expectations for the financial impact of currency movements.

    The company now anticipates a positive currency effect of approximately €15 million on full-year revenue.

    This compares with its previous forecast of a negative impact of €15 million.

    The revised estimate therefore represents a €30 million change in the expected revenue effect of foreign exchange movements.

    For current operating profit, Rémy Cointreau now expects a positive currency contribution of between €3 million and €5 million.

    Previously, the company had anticipated a negative impact of between €5 million and €8 million.

    The revisions reflect updated exchange rate assumptions and their expected effects on the translation of international revenue and earnings.

    Operating Margin Objective Maintained

    Despite changes to its tariff and currency assumptions, Rémy Cointreau maintained its objective of achieving a slight organic improvement in current operating margin during the 2026-27 financial year.

    The company stated:

    “The Group’s objective of achieving a slight organic improvement in Current Operating Margin is thus unchanged.”

    The margin objective remains in place even though the company plans to reinvest approximately €15 million in tariff savings to support growth.

    The decision indicates that management is prioritising expenditure on commercial development while maintaining its underlying profitability target.

    Actual margin performance will depend on sales volumes, product mix, operating expenditure and market conditions during the remainder of the financial year.

    Full-Year Organic Sales Growth Guidance Reaffirmed

    Rémy Cointreau confirmed its guidance for a return to sustainable organic revenue growth during the financial year ending 31 March 2027.

    The company expects sales momentum to improve progressively as the year advances.

    Its outlook reflects the contribution from cognac sales, alongside continuing challenges in liqueurs and spirits.

    The group has not provided a specific numerical organic sales growth target in the reported update.

    Management’s expectations remain dependent on demand across major markets, distribution activity and the timing of customer orders.

    The company also maintained its objective of achieving a slight organic improvement in current operating margin.

    €250 Million Hybrid Bond Issue Completed

    On 30 September 2026, Rémy Cointreau completed its inaugural hybrid bond issuance, raising €250 million.

    The securities carry a fixed coupon of 6.75%.

    The company stated that the entire amount will be recognised as equity for accounting purposes.

    Hybrid bonds combine characteristics of debt and equity financing, with their accounting treatment depending on the contractual terms.

    The transaction forms part of the company’s financing arrangements as it manages its capital structure and financial commitments.

    Rémy Cointreau did not specify the intended allocation of the proceeds in the information provided.

    Leverage Target Remains Below 3.5 Times EBITDA

    Rémy Cointreau reaffirmed its objective of maintaining leverage below 3.5 times net debt to EBITDA at 31 March 2027.

    The ratio measures net borrowing relative to earnings before interest, tax, depreciation and amortisation.

    The target provides a measure of the company’s intended financial position at the end of the current financial year.

    The €250 million hybrid bond issuance is also relevant to the group’s capital structure, given its planned classification as equity.

    The company did not provide an updated net debt figure or current leverage ratio in the reported trading update.

    Outlook for the Remainder of 2026-27

    Rémy Cointreau enters the second half of its financial year with organic sales growth ahead of expectations in the September quarter.

    Cognac demand in Asia-Pacific, particularly China, supported the performance, while inventory adjustments in the United States continued to affect the liqueurs and spirits division.

    The company has reduced its expected tariff-related profit impact and revised its currency assumptions to reflect a positive contribution to revenue and operating profit.

    It continues to target sustainable organic sales growth, a slight improvement in current operating margin and leverage below 3.5 times net debt to EBITDA by the end of March 2027.

    The pace of sales growth, developments in US distribution and demand in Asian markets will remain important factors in the company’s performance during the second half.

    More About Rémy Cointreau

    Rémy Cointreau is a French spirits group specialising in premium alcoholic beverages, including cognac, liqueurs and other spirits.

    Its portfolio includes internationally distributed brands such as Rémy Martin, Cointreau and Mount Gay.

    The company operates across Europe, the Americas and Asia-Pacific, supplying products through distribution networks serving retail, hospitality and other markets.

  • FTSE 100 Falls Ahead of UK Budget as GSK and Unilever Shares Decline Despite Earnings Beats

    FTSE 100 Falls Ahead of UK Budget as GSK and Unilever Shares Decline Despite Earnings Beats

    The FTSE 100 declined on Wednesday as investors assessed corporate earnings from major UK companies and awaited the government’s Budget announcement, with losses in GSK (LSE:GSK) and Unilever (LSE:ULVR) weighing on the benchmark index.

    At 08:18 GMT, the FTSE 100 was down 0.30%, extending its decline from the previous session. European markets also traded lower, with Germany’s DAX falling 0.12% and France’s CAC 40 slipping 0.06%.

    Sterling weakened 0.14% against the US dollar to $1.3288 as market participants considered the potential implications of the Budget for public finances, government borrowing and interest rates.

    Elsewhere, oil prices advanced amid continuing uncertainty surrounding the conflict involving Iran, while gold prices declined.

    GSK Shares Fall Despite Third-Quarter Earnings Beat

    GSK (LSE:GSK) was the FTSE 100’s largest decliner during early trading, with its shares falling 4.3% despite reporting third-quarter results ahead of market expectations.

    The pharmaceutical group reported core earnings per share of 54.6 pence, compared with the analyst consensus of 50.4 pence.

    Quarterly revenue reached £8.89 billion, exceeding expectations of £8.84 billion.

    The figures represented an earnings beat on both measures, although the company’s shares declined following the announcement.

    The market reaction indicated that the better-than-expected results were insufficient to prevent selling pressure during the session.

    The reported figures did not identify a specific factor behind the share price decline.

    Unilever Declines 3.38% After Raising Volume Growth Outlook

    Unilever (LSE:ULVR) also traded lower following its quarterly results, with shares falling 3.38%.

    The consumer goods group reported underlying sales growth of 5.2%, exceeding the 4.8% anticipated by analysts.

    Unilever also raised its volume growth forecast to at least 3%, reflecting an improvement in its expectations for underlying sales volumes.

    Despite the stronger-than-expected sales performance and revised guidance, the company’s shares declined in early trading.

    The falls in GSK and Unilever contributed to weakness in the FTSE 100, given their positions among the index’s major constituents.

    UK Budget in Focus as Sterling Weakens

    Investors were awaiting the UK Budget, with attention directed towards government spending, taxation and the outlook for public borrowing.

    Sterling declined 0.14% against the dollar to $1.3288 during early trading.

    Government bond markets were also in focus as investors assessed the potential implications of fiscal policy for borrowing costs.

    ING analysts suggested that UK government bonds, known as gilts, could experience a “relief rally” if the Budget proved less disruptive than some market participants anticipated.

    The bank referred to the possibility of a Budget “more boring than Burnham’s ambitions would imply.”

    The comments reflected expectations surrounding the fiscal announcement rather than a confirmed market outcome.

    Government Announces Changes to Gas Standing Charges

    Finance Minister John Healey announced plans to remove standing charges on household gas bills, transferring the associated costs into usage-based charges.

    According to the Treasury statement, the standing charges currently cost a typical household approximately £108 annually.

    The proposed change would alter the structure of gas bills by shifting costs away from fixed daily charges and towards consumption.

    Healey said:

    “Gas standing charges are unfair and outdated so I am scrapping them to give millions of households a bit of breathing space.”

    The announcement did not establish the overall financial impact on individual households, which would depend on gas consumption and the final structure of the revised charges.

    The policy formed part of the domestic economic developments being assessed by investors ahead of the Budget.

    Federal Reserve Decision Adds to Market Focus

    Investors were also awaiting the US Federal Reserve’s monetary policy announcement, scheduled for 18:00 GMT.

    The decision was another consideration for financial markets alongside the UK Budget and corporate earnings announcements.

    US interest rate policy can influence global bond yields, currency markets and equity valuations.

    Market participants were monitoring the Fed’s decision and any accompanying commentary for indications about the direction of monetary policy.

    The combination of UK fiscal developments and US monetary policy contributed to the economic calendar facing investors on Wednesday.

    Oil Prices Rise Amid Continuing Middle East Tensions

    Oil prices advanced as markets assessed developments in the conflict involving Iran and the potential consequences for regional energy supplies.

    Brent crude futures increased 1.4% to $110.91 per barrel, while US West Texas Intermediate futures gained 1.41% to $101.30 per barrel.

    US President Donald Trump indicated that further military action against Iran remained possible when questioned by reporters about developments following the upcoming US midterm elections.

    Asked whether the United States could attack Iran again, Trump said:

    “I can’t tell you that, but anything is possible.”

    He also described the timing of the conflict’s conclusion as “simply a question of when I want to end it.”

    The remarks came as diplomatic activity continued across the region.

    Saudi Arabian, Pakistani and Turkish officials met Iranian counterparts in Tehran on Monday as efforts to address the conflict continued.

    Separately, Houthi forces claimed responsibility for a missile attack on Saudi Arabia’s Ras Tanura refinery on Tuesday.

    Saudi authorities had not confirmed the reported attack at the time of the market update.

    The unconfirmed claim added to uncertainty surrounding energy infrastructure and potential supply disruptions.

    Israeli Political Developments Remain in Focus

    Political developments in Israel also formed part of the broader regional situation.

    Prime Minister Benjamin Netanyahu said the threat from Iran “is not over as long as the regime is still here.”

    His comments came as Israeli election exit polls indicated a close contest between Netanyahu’s political bloc and that of opposition leader Gadi Eisenkot.

    The election outcome remained uncertain on the basis of the reported exit polls.

    Developments in Israel, Iran and neighbouring countries continued to influence assessments of regional security and energy supply risks.

    Gold Prices Decline as Oil Advances

    Gold prices moved lower during Wednesday’s trading session.

    Gold futures declined 0.28% to $4,063.15 per ounce, while spot gold fell 0.25% to $4,050.41.

    The declines contrasted with gains in crude oil prices.

    Commodity markets were responding to a combination of geopolitical developments and the approaching US monetary policy decision.

    The reported price movements reflected trading levels at the time of the market update and may have changed subsequently.

    Standard Chartered Raises Full-Year Financial Targets

    Among other UK-listed companies, Standard Chartered (LSE:STAN) raised its full-year income growth and profitability targets following better-than-expected third-quarter results.

    The international banking group reported a 27% increase in pretax profit to $2.25 billion, exceeding analysts’ forecasts.

    Growth in wealth management and trading income contributed to the quarterly performance.

    Standard Chartered now expects full-year income growth to exceed its previous guidance range of 5% to 7%.

    The bank also increased its return on tangible equity target to approximately 14%, compared with its previous objective of more than 12%.

    The revised guidance followed growth across several business divisions, including wealth management.

    Hunting Reduces 2026 Profit Forecast

    Hunting (LSE:HTG) lowered its 2026 core profit forecast for the second time this year.

    The energy services group cited the conflict in the Middle East, attacks in Saudi Arabia and a weaker near-term trading outlook.

    The revised expectations reflected operating conditions affecting its markets and customers.

    The company did not provide a revised numerical profit forecast in the reported market summary.

    Hunting’s announcement added to the corporate developments being assessed by UK investors alongside earnings reports from larger FTSE-listed companies.

    Outlook for UK Equities

    The FTSE 100’s early decline reflected weakness in major index constituents as investors awaited the UK Budget and the Federal Reserve’s interest rate decision.

    GSK and Unilever both reported quarterly results above market expectations, but their shares declined during the session.

    Elsewhere, Standard Chartered raised its annual financial targets, while Hunting reduced its profit outlook.

    Sterling weakened against the dollar, European equity markets edged lower and crude oil prices advanced amid continuing Middle East tensions.

    The Budget announcement, Federal Reserve decision and subsequent developments in corporate earnings and energy markets remained the principal events being monitored during Wednesday’s trading session.

  • Intertek Reports 6.4% Organic Revenue Growth in Q3 and Maintains 2026 Outlook

    Intertek Reports 6.4% Organic Revenue Growth in Q3 and Maintains 2026 Outlook

    Intertek Group plc (LSE:ITRK) reported organic revenue growth of 6.4% in the third quarter of 2026, accelerating from 4.4% in the preceding quarter, supported by stronger performances in Consumer Products, Health & Safety, and Industry and Infrastructure.

    The testing, inspection and certification group recorded reported revenue growth of 7.0%, compared with 8.0% in the second quarter.

    Intertek maintained its full-year guidance for mid-single-digit organic revenue growth, margin progression and strong free cash flow generation.

    The company also confirmed that its acquisition by private equity group EQT is progressing, with completion expected during the fourth quarter of 2026 or the first quarter of 2027.

    Organic Revenue Growth Accelerates in Third Quarter

    Intertek reported third-quarter organic revenue growth of 6.4%, representing an improvement of two percentage points from the 4.4% recorded in the second quarter.

    Organic revenue growth measures changes in underlying business activity, excluding the effects of acquisitions, disposals and currency movements.

    Reported revenue growth was 7.0%, compared with 8.0% in the previous quarter.

    The results reflected differing performances across Intertek’s five operating divisions, with four recording positive organic revenue growth and one reporting a modest decline.

    Consumer Products and Industry and Infrastructure recorded the highest organic growth rates, while Health & Safety also improved compared with the second quarter.

    Corporate Assurance remained in positive territory but experienced slower growth, and World of Energy reported a small contraction.

    Consumer Products Revenue Growth Reaches 9.8%

    Intertek’s Consumer Products division recorded organic revenue growth of 9.8% during the third quarter, compared with 4.3% in the preceding three months.

    The increase of 5.5 percentage points made Consumer Products the company’s fastest-growing division during the period.

    The division provides testing, inspection and assurance services for consumer goods, helping manufacturers and retailers assess products against applicable quality, safety and regulatory requirements.

    Despite the acceleration in quarterly growth, Intertek maintained its full-year outlook for mid-single-digit organic revenue growth in Consumer Products.

    The unchanged guidance indicates that the company has not revised its annual expectations following the third-quarter performance.

    Corporate Assurance Growth Moderates to 4.3%

    Corporate Assurance reported organic revenue growth of 4.3% in the third quarter, compared with 9.3% in the second quarter.

    The five-percentage-point reduction represented the largest sequential slowdown among Intertek’s divisions.

    Corporate Assurance provides services that support businesses in assessing operational standards, management systems, supply chains and compliance requirements.

    Although quarterly growth moderated, Intertek retained its full-year guidance for high-single-digit organic revenue growth in the division.

    The company did not provide additional details in the reported update explaining the difference between second- and third-quarter growth rates.

    Health & Safety Outlook Raised Following 7.5% Growth

    Intertek’s Health & Safety division recorded organic revenue growth of 7.5% during the third quarter, compared with 6.7% in the preceding quarter.

    The improvement prompted the company to raise its full-year outlook for the division.

    Intertek now expects mid-single-digit organic revenue growth in Health & Safety for 2026, compared with its previous forecast of low-single-digit growth.

    The revised guidance reflects the division’s performance during the year and management’s expectations for the remaining months.

    Health & Safety provides testing and assurance services associated with product safety, regulatory compliance and related technical requirements.

    The division was one of two business areas for which Intertek changed its annual outlook in the third-quarter update.

    Industry and Infrastructure Growth Accelerates to 9.2%

    Industry and Infrastructure reported organic revenue growth of 9.2% in the third quarter, compared with 3.6% in the second quarter.

    The increase of 5.6 percentage points represented the largest sequential improvement across Intertek’s operating divisions.

    The business provides inspection, testing and assurance services associated with industrial operations, construction and infrastructure assets.

    Despite the stronger quarterly performance, Intertek maintained its full-year outlook for mid-single-digit organic revenue growth.

    The division’s third-quarter performance contributed to the acceleration in organic growth across the group.

    World of Energy Revenue Declines 0.6%

    Intertek’s World of Energy division recorded a 0.6% decline in organic revenue during the third quarter, compared with growth of 0.4% in the second quarter.

    The division was the only one of Intertek’s five operating segments to report negative organic growth during the period.

    Following the result, Intertek lowered its full-year outlook for World of Energy.

    The company now expects stable like-for-like revenue for 2026, compared with its previous expectation of low-single-digit growth.

    World of Energy provides testing, inspection and assurance services to businesses operating across energy markets.

    The revised forecast reflects a more cautious revenue expectation for the division over the full financial year.

    Full-Year 2026 Guidance Remains Unchanged

    Intertek reaffirmed its group-level financial guidance for 2026 despite adjustments to the outlook for individual divisions.

    The company continues to expect mid-single-digit organic revenue growth for the full year.

    It also anticipates margin progression and strong free cash flow generation.

    The guidance follows third-quarter organic revenue growth of 6.4%, with improved performances in several business areas offsetting slower growth in Corporate Assurance and the decline in World of Energy.

    The company did not announce revised numerical targets for operating margins or free cash flow in the information provided.

    Intertek’s performance during the final quarter will determine the extent to which the group achieves its annual financial objectives.

    EQT Acquisition Expected to Complete by Early 2027

    Intertek also provided an update on its proposed acquisition by private equity group EQT.

    The company said the transaction is progressing and remains expected to complete during the fourth quarter of 2026 or the first quarter of 2027.

    The update did not provide additional information on the transaction’s outstanding conditions, regulatory approvals or other completion requirements.

    The proposed acquisition represents a separate corporate development alongside Intertek’s ongoing trading activities.

    Until the transaction is completed, Intertek continues to report its operating performance and financial outlook as a listed company.

    Outlook for the Remainder of 2026

    Intertek enters the final quarter of 2026 with its overall financial guidance unchanged.

    The group expects mid-single-digit organic revenue growth, margin progression and strong free cash flow.

    Consumer Products and Industry and Infrastructure recorded substantial sequential improvements in third-quarter growth, while Health & Safety also reported an increase.

    Corporate Assurance growth moderated, and World of Energy experienced a slight decline, resulting in a reduction to the latter division’s annual outlook.

    Alongside trading performance, the expected completion of the EQT acquisition remains a significant corporate development for the company.

    More About Intertek

    Intertek Group plc is an international provider of assurance, testing, inspection and certification services.

    The company works with businesses across consumer products, corporate assurance, health and safety, industry and infrastructure, and energy markets.

    Its services help customers assess product quality, regulatory compliance, operational performance and safety standards.

  • Banco Santander Reports 19% Rise in Q3 Underlying Profit to €3.85 Billion and Maintains 2026 Targets

    Banco Santander Reports 19% Rise in Q3 Underlying Profit to €3.85 Billion and Maintains 2026 Targets

    Banco Santander (LSE:BNC) reported a 19% increase in third-quarter underlying profit to €3.85 billion ($4.28 billion), supported by higher customer activity and revenue growth, while reaffirming its financial targets for 2026.

    Spain’s largest bank reported attributable profit of €3.43 billion for the July-to-September period, representing a 2% decline from the previous year. The decrease reflected integration costs associated with its acquisition of US lender Webster.

    Net loan-loss provisions increased 22% to €3.49 billion, partly offsetting the contribution from higher revenues.

    For the first nine months of 2026, Santander reported underlying profit of €11.18 billion, an increase of 16%, while revenue rose 8% to €46.81 billion.

    The bank maintained its expectations for full-year revenue growth, operating costs and profitability, alongside its longer-term financial objectives for 2028.

    Third-Quarter Underlying Profit Increases 19%

    Santander recorded underlying profit of €3.85 billion during the third quarter, compared with the corresponding period in 2025.

    The 19% year-on-year increase reflected higher customer activity and revenue growth across the banking group.

    Underlying profit excludes certain items to provide a measure of operating performance separate from their accounting impact.

    However, attributable profit declined 2% to €3.43 billion.

    The difference between underlying and attributable profit reflected costs associated with the integration of Webster, the US banking business acquired by Santander.

    The company did not specify the total integration expenses recognised during the quarter in the information provided.

    The results indicate that growth in underlying earnings was accompanied by acquisition-related costs and higher provisions for potential credit losses.

    Loan-Loss Provisions Rise 22% to €3.49 Billion

    Santander reported net loan-loss provisions of €3.49 billion for the third quarter, an increase of 22% compared with the previous year.

    Loan-loss provisions represent charges recognised by banks to account for expected losses on lending exposures.

    The increase reduced the contribution of revenue growth to reported profitability.

    Santander’s results reflected the impact of higher provisions alongside increased customer activity and income generation.

    The bank did not provide a breakdown of the provision increase by geography or lending category in the reported figures.

    Future credit costs will depend on borrower performance, economic conditions and developments across the bank’s lending portfolios.

    Nine-Month Underlying Profit Reaches €11.18 Billion

    For the nine months ended September 2026, Santander reported underlying profit of €11.18 billion.

    The figure represented a 16% increase compared with the corresponding period in 2025.

    Revenue increased 8% to €46.81 billion over the same period.

    The bank attributed its performance to revenue growth and cost management under its ONE Transformation programme.

    The programme is intended to improve operating efficiency and support the group’s financial performance.

    Santander’s nine-month results provide the basis for its reaffirmed full-year targets, including its expectation that annual profit will exceed the €14.1 billion recorded in 2025.

    Santander Reaffirms 2026 Revenue and Profit Guidance

    Santander maintained its financial targets for the year ending December 2026.

    The bank continues to expect mid-single-digit revenue growth for the full year.

    It also anticipates a reduction in operating costs when measured in constant euros, excluding the effects of currency movements.

    Santander expects annual profit to exceed the €14.1 billion reported in 2025.

    The company did not announce a revised numerical profit target beyond that threshold.

    The reaffirmed guidance follows the increase in underlying earnings during the first nine months, although higher loan-loss provisions and acquisition-related expenses remain relevant to the final reported results.

    ONE Transformation Programme Supports Cost Targets

    Santander identified cost discipline under its ONE Transformation programme as a contributor to its nine-month financial performance.

    The initiative forms part of the bank’s operating strategy and is intended to support efficiency across its businesses.

    The bank’s full-year target includes lower costs in constant euros, indicating an objective to reduce expenditure independently of foreign exchange movements.

    Revenue growth and cost management contributed to the 16% increase in underlying profit during the first nine months.

    The figures provided did not include a separate breakdown of savings attributable to the transformation programme.

    Santander continues to incorporate the programme into its financial objectives for 2026 and beyond.

    CET1 Capital Ratio Expected to Reach 12.8%–13%

    Santander reported a Common Equity Tier 1 (CET1) capital ratio of 12.7% at the end of September 2026.

    The bank expects the ratio to reach between 12.8% and 13% by the end of the year.

    The CET1 ratio measures a bank’s core regulatory capital relative to its risk-weighted assets.

    It is used to assess capital adequacy and the bank’s capacity to absorb losses.

    Santander’s year-end target implies an increase of between 10 and 30 basis points from the September level.

    The bank reaffirmed this objective alongside its income, cost and profitability guidance.

    Webster Acquisition Affects Reported Earnings

    Integration costs associated with Santander’s acquisition of US lender Webster contributed to the decline in third-quarter attributable profit.

    While underlying profit increased 19%, attributable profit fell 2% to €3.43 billion.

    The difference highlights the effect of acquisition-related expenses on the group’s reported earnings.

    Santander did not provide a detailed timetable for completing the integration or quantify the expected future financial contribution from Webster in the information supplied.

    The integration process remains a factor in the distinction between the bank’s underlying performance and attributable profit.

    Santander Maintains 2028 Profitability Objectives

    Beyond its 2026 financial targets, Santander reiterated its longer-term objectives for 2028.

    The bank aims to achieve a return on tangible equity exceeding 20%.

    It also targets annual profit of more than €20 billion by that year.

    Return on tangible equity measures profitability relative to shareholders’ tangible equity and provides an indication of the returns generated from the bank’s capital base.

    The 2028 objectives imply further earnings growth from the levels reported in 2025 and expected for 2026.

    Achieving these targets will depend on revenue development, operating costs, credit performance, capital requirements and the contribution of the bank’s businesses.

    The company did not announce changes to either target.

    Outlook for the Remainder of 2026

    Santander enters the final quarter of 2026 with its full-year financial guidance unchanged.

    The bank continues to target mid-single-digit revenue growth, lower operating costs in constant euros and profit above the €14.1 billion recorded in 2025.

    It also expects its CET1 capital ratio to finish the year between 12.8% and 13%.

    The third-quarter results showed higher underlying earnings and revenue growth, alongside increased loan-loss provisions and costs associated with the Webster acquisition.

    The group’s fourth-quarter performance will determine whether the annual targets are achieved.

    More About Banco Santander

    Banco Santander is a Spanish multinational banking group providing retail, commercial, corporate and investment banking services.

    The company operates across Europe and the Americas, offering lending, deposit, payment, investment and other financial services to individuals and businesses.

    Santander’s operations include consumer finance, wealth management and corporate banking activities.