Author: Fiona Craig

  • Wizz Air Reports Strong July Traffic Growth as Network Expansion Continues

    Wizz Air Reports Strong July Traffic Growth as Network Expansion Continues

    Wizz Air (LSE:WIZZ) recorded strong passenger growth in July, carrying 8.36 million travellers, an increase of 31.6% compared with the same month last year. The airline also expanded capacity by 30.4% to 8.91 million seats, while its load factor improved to 93.7%, reflecting resilient summer travel demand and continued improvements in operational performance.

    The airline continued to strengthen its European network during the month by announcing new operating bases in Madrid and Valencia. These additions will support the launch of 10 domestic routes and three international services within Spain. Wizz Air also confirmed plans to establish a new base in Prishtina, Kosovo, which is expected to add around 500,000 seats to its network next year.

    Alongside its route expansion, the company introduced Wizz Holidays, a new travel platform offering customers package holidays that combine flights with selected accommodation and ground transfers. Wizz Air also reported further progress in improving environmental performance, reducing carbon dioxide emissions per passenger kilometre compared with the previous year.

    The company’s investment outlook remains affected by relatively weak recent profitability and a highly leveraged balance sheet, factors that can increase financial risk in the cyclical airline industry. However, these concerns are partly balanced by improving cash generation, a comparatively low price-to-earnings valuation and technical indicators that continue to point towards a broadly positive share price trend without suggesting excessive market optimism.

    More about Wizz Air Holdings

    Wizz Air Holdings is one of Europe’s leading ultra-low-cost airlines, operating short- and medium-haul flights across Central, Eastern and Western Europe. The carrier follows a point-to-point operating model and serves both leisure travellers and passengers visiting friends and relatives through an extensive network of affordable routes.

    The airline operates a modern single-aisle aircraft fleet and continues to pursue capacity expansion across key European markets. Its strategy focuses on maintaining low operating costs while growing market share through network expansion, competitive pricing and operational efficiency.
  • XP Power Reports Strong Order Growth as Market Recovery Supports Outlook

    XP Power Reports Strong Order Growth as Market Recovery Supports Outlook

    XP Power (LSE:XPP) delivered first-half 2026 results broadly in line with expectations, with a significant increase in order intake providing confidence for the remainder of the year. Orders rose to £167.2 million, resulting in a book-to-bill ratio of 1.53 times, the highest level recorded since early 2022. Revenue remained broadly stable at £109.1 million on a constant currency basis, while adjusted operating profit almost doubled, reflecting stronger margins and disciplined cost management.

    Gross margin improved by 450 basis points during the period, helping to strengthen profitability despite relatively flat sales. The company said its restructuring initiatives and tighter control of operating costs contributed to the improved financial performance.

    XP Power ended the first half with an order book valued at £173.9 million, including £135 million of firm orders scheduled for delivery during the second half of the year. This provides a solid foundation for stronger revenue generation in the coming months, and management maintained its full-year guidance unchanged.

    The company said demand improved across all major regions and end markets, with particularly strong momentum in semiconductor manufacturing equipment and higher-margin technology applications. Recent investments in manufacturing capacity in Vietnam and Malaysia, together with the optimisation of its production footprint, are expected to support future growth as market conditions continue to recover.

    XP Power’s investment outlook remains influenced by losses reported over recent years and lower trailing revenue, although improving cash generation and reduced leverage provide encouraging signs. Technical indicators remain supportive, reflecting a strong upward trend in the share price, although overbought conditions could increase the risk of short-term volatility. Valuation continues to be constrained by negative earnings and the absence of a dividend yield.

    More about XP Power

    XP Power is a FTSE 250-listed designer and manufacturer of power conversion solutions used in a wide range of electronic equipment. Its products convert electricity from the power grid into the regulated power required by industrial, semiconductor and healthcare applications.

    Headquartered in Singapore, the company operates manufacturing facilities in Vietnam, Malaysia, North America and Germany, supplying major global original equipment manufacturers. XP Power specialises in serving customers with long product lifecycles, particularly within semiconductor manufacturing, industrial technology and medical equipment markets.

  • Fresnillo Delivers Record Interim Earnings as Gold and Silver Prices Boost Results

    Fresnillo Delivers Record Interim Earnings as Gold and Silver Prices Boost Results

    Fresnillo (LSE:FRES) reported a substantial improvement in its financial performance for the six months ended 30 June 2026, benefiting from exceptionally strong gold and silver prices that more than compensated for lower production volumes. Revenue increased 74.7% to US$3.38 billion, while gross profit rose 130.7% to US$2.36 billion. EBITDA also more than doubled, supporting robust operating cash flow and lifting the company’s cash balance to US$2.50 billion.

    The stronger financial position enabled Fresnillo to complete the acquisition of Probe Gold, continue investing in exploration activities and maintain capital expenditure across its operations. The Board also increased the interim dividend to 43.4 US cents per share, reflecting confidence in the group’s financial strength. Although silver production declined by 11.4% and gold output fell 7.3% due to lower ore grades, adverse weather conditions and minor project delays, the company left its full-year production guidance unchanged and highlighted ongoing cost management initiatives and infrastructure investment as key priorities.

    Adjusted production costs increased during the period, primarily due to the appreciation of the Mexican peso, inflationary pressures and higher maintenance and contractor expenses at certain operations. However, these higher costs were more than offset by favourable commodity prices. Profit for the period more than tripled to US$1.46 billion, while earnings per share increased by almost 228%, providing additional capacity to invest in future growth while maintaining a strong balance sheet and supporting its safety and community programmes.

    The company’s outlook is supported by significantly improved profitability, stronger cash flow generation and low leverage, together with a solid pipeline of development and exploration projects. However, near-term technical indicators remain mixed, with the shares trading below their 20-day and 50-day moving averages. Valuation also appears relatively full, while management highlighted higher capital expenditure and tax payments during 2026 as potential headwinds.

    More about Fresnillo

    Fresnillo plc is a London-listed precious metals mining company with operations centred on large-scale silver and gold production in Mexico. The group owns a portfolio of high-quality mining assets and focuses on operational efficiency, disciplined cost management and targeted acquisitions to support long-term growth.

    In addition to silver and gold, Fresnillo produces lead and zinc as by-products and continues to invest in exploration and infrastructure to replenish reserves and extend mine life. Its principal operations include the Saucito, Herradura, Fresnillo, Juanicipio, San Julián and Ciénega mines, providing diversified exposure to precious metals production while positioning the company to benefit from favourable commodity price trends.

  • Synthomer Raises 2026 Guidance Following Strong First-Half Performance

    Synthomer Raises 2026 Guidance Following Strong First-Half Performance

    Synthomer (LSE:SYNT) delivered a stronger first half of 2026 than expected, with revenue from continuing operations increasing 5.1% at constant currency and sales volumes rising 2.3%. Growth was recorded across all three business divisions, supported by solid demand in a range of end markets. Coatings & Construction Solutions benefited from industrial coatings used in data centres, energy projects and an improving construction sector, while Adhesive Solutions expanded through stronger sales in China and medical applications. Health & Protection achieved double-digit volume growth, supported by its strong market position and resilient supply chain.

    Underlying EBITDA from continuing operations increased 16.4% to £96.7 million, with margins improving by 80 basis points. Higher profitability reflected continued innovation, cost-saving initiatives, geographic expansion and effective pricing. Underlying profit before tax also improved to £12.7 million despite higher financing costs. Management said approximately £8 million of the EBITDA improvement came from recurring strategic initiatives, while around £6 million reflected temporary benefits linked to supply disruptions caused by geopolitical conflict.

    Following the stronger-than-expected first-half performance, Synthomer upgraded its outlook for 2026 and now expects full-year results to come in slightly ahead of current market forecasts. The company also anticipates generating positive free cash flow during the second half of the year and expects leverage to continue improving.

    The group remains focused on increasing its exposure to higher-margin speciality products, delivering a 190-basis-point improvement in gross margin over the past year and a 600-basis-point increase over the last four years. New product development has centred on areas including intumescent coatings for data centres, drilling additives and medical adhesives. At the same time, Synthomer is continuing to simplify its portfolio through the planned sale of its Acrylate Monomers business and three additional divestments, with the aim of reducing debt, improving earnings quality and concentrating on its core speciality operations.

    The company’s investment outlook continues to be influenced by a history of losses and inconsistent revenue growth, together with weak short-term technical indicators, including trading below key moving averages and a negative MACD. However, improving cash flow generation and ongoing debt reduction provide positive support. Valuation remains difficult to assess due to negative earnings and the absence of dividend yield data.

    More about Synthomer

    Synthomer is a London-listed manufacturer of speciality polymers and chemical ingredients used across the coatings, construction, adhesives, health and protection industries. The company operates three core business divisions, serving more than 6,000 customers through 29 manufacturing sites and five innovation centres located across Europe, North America, the Middle East and Asia.

    Its portfolio focuses on high-performance polymer technologies designed to improve product performance and sustainability in applications ranging from architectural coatings and construction materials to medical products and industrial adhesives. Through its emphasis on speciality chemicals and ongoing portfolio optimisation, Synthomer aims to strengthen profitability and deliver long-term growth.

  • CT Automotive Expects Stronger Second Half Following Revenue Growth and Mexico Expansion

    CT Automotive Expects Stronger Second Half Following Revenue Growth and Mexico Expansion

    CT Automotive (LSE:CTA) reported first-half 2026 revenue of $62.1 million, an increase of 15% compared with the same period last year, driven by strong customer demand and the successful launch of new production programmes at its expanded manufacturing facility in Mexico. However, underlying profit before tax declined significantly as the business absorbed start-up costs at the new site and faced disruption linked to geopolitical factors.

    The company said operations in China and Türkiye continued to perform in line with expectations, while the new paint facility in Mexico is expected to improve production efficiency by reducing inventory requirements and lowering dependence on imported components with long lead times.

    Although profitability came under pressure during the first half, the Board expects a much stronger performance in the second half of the year. Management believes contract cost-recovery mechanisms, improved operational efficiency and the ongoing rollout of its proprietary factory operating system will support higher margins. The platform uses agentic artificial intelligence to provide real-time oversight of production, supply chain management and quality control, helping to improve productivity across manufacturing operations.

    CT Automotive said these initiatives should offset the higher costs experienced earlier in the year and allow the company to meet current market expectations for full-year 2026. The business continues to position itself as a competitive supplier of complex automotive interior components to global vehicle manufacturers.

    The company’s investment outlook is supported by improving profitability, a stronger balance sheet, favourable technical indicators and a relatively low price-to-earnings valuation. However, weaker free cash flow generation and softer revenue trends during 2024 and 2025 continue to weigh on the overall outlook.

    More about CT Automotive Group Plc

    CT Automotive Group plc is a UK-based designer and manufacturer of customised automotive interior components and kinematic assemblies for leading global vehicle manufacturers and Tier One suppliers. The company operates manufacturing facilities in China, Mexico and Türkiye, supported by distribution networks across Europe, Asia and North America.

    Its product range includes dashboard panels, fascia trims, air vents, armrests, cup holders, storage systems and related tooling for more than 64 vehicle models produced by 21 original equipment manufacturers. Customers include Nissan, Ford, General Motors, Volkswagen Audi Group, Bentley, Lamborghini and electric vehicle manufacturers such as Rivian, reflecting the company’s broad exposure across both traditional and electric automotive markets.

  • Gulf Marine Services Refinances Vessel Loan and Increases Working Capital Capacity

    Gulf Marine Services Refinances Vessel Loan and Increases Working Capital Capacity

    Gulf Marine Services (LSE:GMS) has converted a US$37.4 million bridge loan into a five-year term loan under its existing syndicated financing facilities, strengthening the group’s long-term funding position. The bridge loan, originally arranged in January 2026 to finance the acquisition of a new vessel, has been incorporated into lending agreements with HSBC, First Abu Dhabi Bank and Commercial Bank of Dubai without any changes to margins, covenants or security arrangements. The refinancing also does not increase the company’s overall debt and better aligns the financing with the operational life of the vessel.

    The company has also secured an additional working capital facility equivalent to US$7.5 million from Commercial Bank of Dubai. Up to 40% of the facility can be drawn in cash, with pricing set at 2.25% above EIBOR, consistent with Gulf Marine Services’ existing working capital facilities.

    Management said the additional liquidity will support the company’s expansion into new markets and strengthen its ability to secure and deliver offshore energy contracts. The facility is expected to be used primarily for bonds and bank guarantees, providing greater financial flexibility while avoiding a significant increase in financing costs.

    Gulf Marine Services’ investment outlook continues to benefit from improving financial fundamentals, including lower leverage, sustained profitability and generally positive free cash flow generation. However, these positives are partly offset by a decline in net income during 2025 and a notable reduction in free cash flow over the same period. Technical indicators remain mixed, while valuation appears broadly in line with the market, offering limited additional upside.

    More about Gulf Marine Services

    Gulf Marine Services is a London-listed offshore support vessel operator established in Abu Dhabi in 1977. The company owns and operates a fleet of 15 self-propelled self-elevating support vessels, providing services to the offshore energy industry across the Middle East, Europe, the Americas and other international markets.

    Its vessels support a wide range of offshore activities, including platform maintenance, well intervention, offshore wind turbine servicing, installation projects and decommissioning work. The group’s modern fleet and diversified geographic presence position it to serve both traditional oil and gas operators and the growing offshore renewable energy sector.

  • MedPal AI Reaches £8.6 Million Annualised Revenue Run Rate Following Record July

    MedPal AI Reaches £8.6 Million Annualised Revenue Run Rate Following Record July

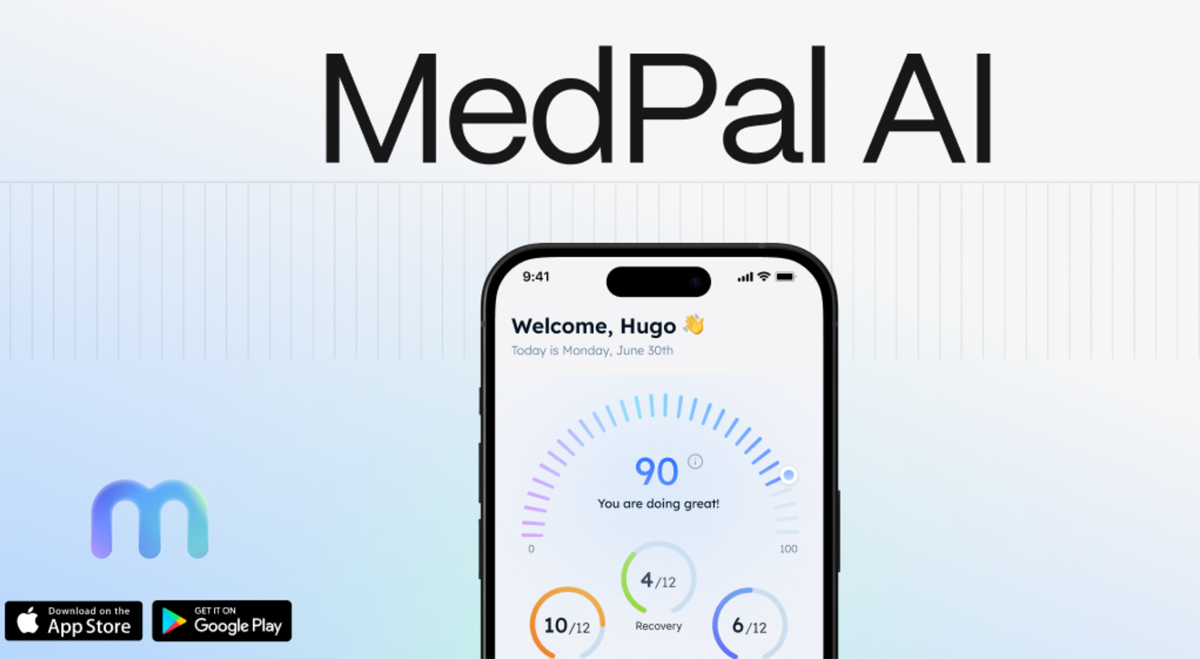
    MedPal AI (LSE:MPAL) has reported a significant expansion in its business, with annualised recurring revenue increasing to approximately £8.6 million only nine months after launching its dispensing operations in October 2025. July 2026 marked the first month in which all three of the group’s core revenue streams were fully operational, resulting in its strongest monthly trading performance to date. Income was generated from NHS prescription dispensing, private GLP-1 weight management services under the New Health brand and recurring software subscriptions through the recently acquired eMARx platform.

    Prescription volumes within the NHS business reached a new monthly high, supporting an annualised revenue run rate of more than £5.5 million. Meanwhile, the New Health division generated annualised private prescription revenue exceeding £2.2 million after only three weeks of marketing activity, demonstrating early demand for its weight management services.

    The acquisition of eMARx has added approximately £843,000 in annualised recurring software revenue, providing MedPal AI with a high-margin SaaS income stream. Management intends to expand revenue opportunities by cross-selling products and services across its growing customer base, allowing multiple offerings to be delivered through a single client relationship.

    The company also completed the acquisition of eMARx using a combination of cash and newly issued shares. In addition, advisory fees were settled through the issue of 928,570 new ordinary shares, bringing the total number of voting rights to 778,042,430. MedPal AI said these transactions strengthen its platform as it continues to build an integrated AI-driven healthcare ecosystem spanning pharmacy services, digital health and care-home technology.

    More about MedPal AI Plc

    MedPal AI plc is an AI-focused digital healthcare company operating across pharmacy, healthcare software and patient services. Its business includes NHS Distance Selling Pharmacy hubs, the New Health GLP-1 weight management clinic, a business-to-business pharmacy supply operation for care homes and the eMARx electronic medication administration platform.

    The company is also developing Juno, an AI-powered healthcare assistant built using Anthropic’s Claude model, as part of its wider vision to create an integrated Health OS platform connecting prescribing, dispensing, medication management, delivery and patient support. Listed on both AIM and the Frankfurt Stock Exchange, MedPal AI generates recurring revenue from NHS and private prescriptions, software subscriptions and digital healthcare services.

  • Travis Perkins Improves Profitability and Balance Sheet Despite Soft Construction Demand

    Travis Perkins Improves Profitability and Balance Sheet Despite Soft Construction Demand

    Travis Perkins (LSE:TPK) reported revenue of £2.26 billion for the first half of 2026, a decline of 1.8% from the previous year as UK construction activity remained subdued and following the earlier disposal of its Staircraft business. Despite lower sales, adjusted operating profit increased to £67 million, supported by an £11 million improvement in gross margin and higher gains from property transactions.

    Performance varied across the group’s divisions during the period. General Merchant delivered stronger margins through improved pricing discipline and procurement efficiencies, while Toolstation UK achieved growth in both revenue and profitability. Trading conditions in the Benelux remained challenging, although the group’s specialist businesses proved resilient as infrastructure-related demand helped offset weakness in residential new-build markets.

    Travis Perkins also strengthened its financial position, ending the period with net cash of £55 million before lease liabilities. Leverage fell to 1.9 times adjusted EBITDA, returning to the company’s target range of 1.5 to 2.0 times and supporting its investment-grade financial profile. The improvement reflected disciplined capital expenditure, effective working capital management and continued optimisation of the property portfolio.

    Although operational performance continued to improve, the Board reduced the interim dividend to 4.0 pence per share in line with its policy of distributing between 30% and 40% of earnings. Management expects market conditions to remain broadly unchanged during the second half of the year as the construction sector continues to face weak demand and fluctuating building material costs.

    Chief Executive Gavin Slark said the group’s turnaround programme is making encouraging progress, citing greater stability within the senior leadership team and a renewed emphasis on customer service. He added that the stronger balance sheet provides the flexibility to invest selectively while positioning the business to benefit when construction markets recover.

    The company’s investment outlook remains constrained by the weaker profitability recorded during 2024 and 2025, together with negative technical indicators, including trading below key moving averages and a bearish MACD. However, stronger operating cash flow, improved free cash flow and moderate leverage provide some support. Valuation remains mixed, with the absence of positive earnings offset in part by a dividend yield of around 2.3%.

    More about Travis Perkins

    Travis Perkins plc is the UK’s largest distributor of building materials, supplying professional tradespeople and construction businesses through its General Merchant network, Toolstation stores and specialist operations. The company serves a broad range of residential, commercial and infrastructure markets across the UK, with a smaller presence in the Benelux region.

    Its business combines traditional builders’ merchanting with trade-focused retail and specialist distribution, making the group an important indicator of activity across the UK construction sector. Alongside its nationwide branch network, Travis Perkins manages an extensive property portfolio and vehicle fleet, using disciplined capital allocation and operational efficiency to support long-term financial performance.

  • Sabre Insurance Reports Strong Premium Growth as Ambition 2030 Strategy Progresses

    Sabre Insurance Reports Strong Premium Growth as Ambition 2030 Strategy Progresses

    Sabre Insurance Group (LSE:SBRE) delivered a strong performance during the first half of 2026, with gross written premiums increasing by more than 15% compared with the same period last year. Premiums from its core motor vehicle business rose by more than 18%, reflecting continued growth despite challenging conditions across the UK motor insurance market.

    The group’s interim net insurance margin was 15.7%, below its long-term target, while the expense ratio remained elevated due to the impact of higher business volumes written in previous periods. However, management said new business continues to be priced at margins that fully account for claims inflation, providing confidence in future profitability.

    Sabre expects the strong premium growth recorded in the first half to contribute more significantly to earnings during the second half of the year, supporting an improvement in the expense ratio and a return to its target net insurance margin range of 18% to 22%. The company also continued to reward shareholders through a 4.1 pence interim dividend and a £5 million share buyback programme.

    Growth initiatives remain centred on the Ambition 2030 strategy, including the expansion of the Sabre Direct motorcycle insurance offering and the wider use of artificial intelligence across pricing and operational processes. Management believes these investments will help drive profitable growth as market conditions continue to stabilise, despite ongoing claims inflation.

    Sabre’s outlook is supported by a strong financial position, including low leverage, improving earnings momentum and an attractive valuation underpinned by a relatively high dividend yield. However, historical fluctuations in profitability and cash flow, together with technical indicators suggesting the shares may be overbought, could create some short-term risks.

    More about Sabre Insurance Group plc

    Sabre Insurance Group plc is a UK motor insurance specialist focused on providing cover for private motor vehicles and motorcycles. The company operates with a disciplined underwriting approach, aiming to maintain net insurance margins of between 18% and 22% while carefully managing the impact of claims inflation.

    Through its Ambition 2030 strategy, Sabre is investing in product expansion, including its direct motorcycle insurance business, while introducing artificial intelligence to improve pricing accuracy and operational efficiency. The group also maintains a strong capital position to support long-term growth and shareholder returns.

  • Seraphim Space Trust Deploys C Share Capital into Pixxel and Zeno Power

    Seraphim Space Trust Deploys C Share Capital into Pixxel and Zeno Power

    Seraphim Space Investment Trust Plc (LSE:SSIT) has started investing the £137 million raised through its recent C Share issue, committing $25 million to hyperspectral imaging company Pixxel and a further $3.6 million to nuclear power technology developer Zeno Power. Both businesses are existing portfolio holdings, reflecting the trust’s strategy of increasing investment in established SpaceTech companies with strong growth potential rather than adding new investments.

    Pixxel is continuing to expand its high-resolution hyperspectral Earth observation satellite constellation alongside its AI-powered analytics platform. The company also benefits from in-house satellite manufacturing capabilities and a number of significant contracts with the Indian government, strengthening its position across both commercial and sovereign markets.

    Meanwhile, Zeno Power is developing radioisotope power systems designed for applications in lunar exploration, maritime operations and defence. The business is supported by contracts with organisations including NASA, the US Navy and the US Space Force. Seraphim Space Investment Trust said the deployment of proceeds from the C Share fundraising remains on schedule and is focused on long-term investment themes such as Earth observation, advanced energy technologies and the emerging lunar economy.

    The trust’s investment outlook is moderated by consistently negative operating cash flow and earnings that are heavily influenced by changes in portfolio valuations. However, its debt-free balance sheet provides financial stability. Technical indicators point to weak short-term momentum, with the shares trading below key moving averages, while a relatively low price-to-earnings ratio offers only limited support.

    More about Seraphim Space Investment Trust Plc

    Seraphim Space Investment Trust Plc is the world’s first publicly listed investment company dedicated exclusively to the SpaceTech sector. Listed on the London Stock Exchange under the ticker SSIT, the trust invests in innovative businesses developing technologies for commercial and government applications across the global space industry.

    Its portfolio includes companies focused on satellite infrastructure, Earth observation, artificial intelligence, defence technologies and advanced energy systems. By investing in businesses positioned to benefit from long-term trends such as sovereign space capability, national security and lunar exploration, the trust aims to capture growth across the rapidly evolving space economy.