Author: Fiona Craig

  • Renew Acquires PBU for Up to £50 Million to Expand UK Electricity Network Engineering Services

    Renew Acquires PBU for Up to £50 Million to Expand UK Electricity Network Engineering Services

    Renew Holdings plc (LSE:RNWH) has agreed to acquire Porter Brothers Holdings Limited, the parent company of PBU (UK) Ltd, for total consideration of up to £50 million, expanding its engineering capabilities in the UK’s electricity transmission and distribution market.

    The infrastructure engineering group said the acquisition is being undertaken through its wholly owned subsidiary, Excalon Holdings Limited, and will add specialist extra high voltage cabling and directional drilling services to its existing operations.

    Renew will pay initial cash consideration of £31.1 million, funded through its existing banking facilities, with a further £18.9 million potentially payable depending on the achievement of specified profit targets over three years.

    The company expects the transaction to be immediately earnings enhancing and said it will continue to evaluate further acquisition opportunities.

    Initial Acquisition Consideration Set at £31.1 Million

    Renew has structured the acquisition with an initial cash payment of £31.1 million and additional contingent consideration of up to £18.9 million.

    The transaction has been agreed on a cash-free, debt-free basis.

    The initial consideration is based on PBU’s sustainable earnings before interest and tax (EBIT) of £3.9 million and earnings before interest, tax, depreciation and amortisation (EBITDA) of £5.5 million.

    Based on these figures, the initial purchase price represents approximately 8.0 times sustainable EBIT and 5.7 times sustainable EBITDA.

    If the full £50 million consideration becomes payable, the equivalent multiples would be approximately 12.8 times EBIT and 9.1 times EBITDA, using the disclosed sustainable earnings figures.

    The additional consideration is conditional on the vendors meeting specified profit targets during the three-year period following the acquisition.

    Renew did not disclose the individual performance thresholds or the expected timing of contingent payments.

    The initial purchase price will be financed using the group’s existing banking facilities.

    PBU Adds Extra High Voltage Cabling Expertise

    PBU provides specialist engineering services to the electricity distribution sector, with particular expertise in extra high voltage cabling and directional drilling.

    These services support the installation and development of electricity network infrastructure.

    Extra high voltage cabling is used in electricity networks requiring the transmission or distribution of power at higher voltage levels.

    Directional drilling enables underground infrastructure to be installed along planned routes, including where conventional excavation methods may be less suitable.

    The acquisition expands the technical services available through Renew’s Excalon Holdings subsidiary.

    Renew said the additional capabilities will allow the group to undertake a broader range of electricity transmission and distribution projects.

    The company did not disclose PBU’s annual revenue, workforce size or current order book in the announcement.

    Excalon Expands Turnkey Electricity Network Services

    The acquisition forms part of Renew’s strategy to develop a wider range of engineering services within Excalon Holdings.

    The group has previously acquired Emerald Power, Electricity Distribution Engineering Services and PWR-X.

    Together with PBU, these businesses provide capabilities covering different stages of electricity network projects.

    Renew said Excalon can now offer a turnkey service extending from initial design through to engineering delivery.

    The expanded operating structure is intended to allow the group to undertake projects requiring several specialist disciplines under a single delivery arrangement.

    The company expects the additional services to increase the range of contracts for which Excalon can compete.

    The announcement did not specify any new contracts awarded as a direct result of the acquisition.

    Acquisition Targets UK Electricity Transmission and Distribution Investment

    Renew identified planned investment in the UK’s electricity networks as a principal reason for expanding its specialist engineering capabilities.

    The company referred to approximately £50 billion to £60 billion of committed investment across the RIIO-ED2 and ET3 regulatory control periods and beyond.

    These investment programmes relate to the development, maintenance and upgrading of electricity distribution and transmission infrastructure.

    Renew said the acquisition will increase its ability to participate in projects associated with this expenditure.

    The company’s engineering services support infrastructure maintenance, renewal and development across regulated markets.

    By adding PBU’s cabling and drilling capabilities, Renew intends to address a wider range of project requirements within the electricity network sector.

    The £50 billion to £60 billion figure represents broader industry investment rather than revenue contracted to Renew.

    Transaction Expected to Be Immediately Earnings Enhancing

    Renew stated that the PBU acquisition is expected to be immediately earnings enhancing.

    The company based the initial purchase consideration on sustainable EBIT of £3.9 million and EBITDA of £5.5 million.

    These earnings measures provide an indication of PBU’s existing operating profitability.

    Renew did not quantify the anticipated contribution to group earnings per share or provide revised full-year financial guidance following the transaction.

    The acquisition is expected to contribute to the group’s Engineering Services operations.

    The financial impact will depend on PBU’s performance following integration, the cost of acquisition financing and the achievement of any contingent consideration targets.

    Existing Banking Facilities Fund Initial Payment

    Renew confirmed that the £31.1 million initial cash consideration has been funded through its existing banking facilities.

    The company said it retains the financial capacity to continue pursuing its acquisition strategy following the transaction.

    However, Renew did not provide an updated net debt figure, borrowing balance or liquidity position in the announcement.

    The potential additional payment of £18.9 million will depend on PBU meeting agreed profit targets over the next three years.

    The deferred structure links part of the acquisition cost to the financial performance of the acquired business.

    Renew has not disclosed whether the contingent payments will be made annually or at the end of the performance period.

    Renew Continues Acquisition-Led Expansion

    Renew said it remains engaged in evaluating additional acquisition opportunities within its specialist engineering markets.

    The group has expanded its electricity transmission and distribution activities through a series of transactions involving businesses with complementary technical capabilities.

    The PBU acquisition follows the additions of Emerald Power, Electricity Distribution Engineering Services and PWR-X.

    Renew’s strategy involves combining specialist engineering businesses to broaden its service offering and increase its participation in infrastructure investment programmes.

    The company described its acquisition approach as focused on businesses capable of contributing to earnings.

    No further acquisition targets, transaction values or completion timetables were announced.

    CEO Paul Scott Comments on Acquisition

    Paul Scott, Chief Executive Officer of Renew, commented on the acquisition and its role in the group’s electricity network operations.

    “This acquisition represents an excellent strategic fit for the Group, adding complementary specialist capabilities to our already well-established position in the regulated energy market. Our enhanced capabilities leave us strongly positioned to capitalise on the significant growth opportunities presented by the unprecedented levels of investment in the UK’s electricity transmission and distribution networks.

    “PBU is a company we already know very well, I am delighted to welcome their highly regarded teams into the Renew family and I look forward to updating the market on their integration into the Group in due course.”

    Integration of PBU Into Excalon Holdings

    PBU will become part of Renew’s Excalon Holdings operations, bringing additional engineering expertise to the group’s electricity network activities.

    The acquisition is intended to complement the services provided by Excalon’s existing businesses.

    Renew expects the combined operations to provide clients with a broader range of engineering services, including project design, extra high voltage cabling, directional drilling and associated infrastructure delivery.

    Management said further information about PBU’s integration will be provided in due course.

    The company has not disclosed specific integration costs, restructuring plans or expected operational savings.

    Outlook for Renew’s Electricity Network Operations

    Renew expects the acquisition to increase its ability to participate in UK electricity transmission and distribution investment programmes.

    The addition of PBU expands the range of specialist services available through Excalon Holdings and supports the group’s objective of delivering projects from design through to completion.

    The transaction is expected to contribute immediately to earnings, with further consideration dependent on PBU’s financial performance over three years.

    Renew also intends to continue reviewing potential acquisitions that complement its existing engineering activities.

    The company has not announced changes to its financial guidance or provided a revised earnings forecast following the acquisition.

    More About Renew Holdings

    Renew Holdings plc is a London-listed engineering services group focused on the maintenance and renewal of critical infrastructure in the United Kingdom.

    The company provides specialist engineering services across infrastructure markets, including electricity transmission and distribution.

    Its wholly owned subsidiary Excalon Holdings operates in the electricity network sector and has expanded through acquisitions of complementary engineering businesses.

    The acquisition of PBU adds extra high voltage cabling and directional drilling capabilities to the group’s existing operations.

    Renew continues to pursue organic development and acquisitions within its specialist engineering markets.
  • Unilever Reports 5.2% Q3 Underlying Sales Growth and Raises Full-Year Volume Outlook

    Unilever Reports 5.2% Q3 Underlying Sales Growth and Raises Full-Year Volume Outlook

    Unilever PLC (LSE:ULVR) reported underlying sales growth of 5.2% in the third quarter of 2026, supported by higher volumes across its Beauty & Wellbeing, Personal Care and Home Care businesses, while raising its full-year underlying volume growth forecast to at least 3%.

    The consumer goods group recorded quarterly turnover of €13.3 billion, an increase of 6.7% compared with the corresponding period of 2025. Underlying volume growth contributed 2.9 percentage points, while price growth contributed 2.3 percentage points.

    Unilever’s Home Care division recorded the highest underlying sales growth at 9.1%, followed by Personal Care at 6.3% and Beauty & Wellbeing at 5.7%. Foods reported broadly unchanged underlying sales, with a 0.1% increase.

    The company maintained its full-year underlying sales growth guidance of 4% to 6% and expects a modest improvement in its underlying operating margin compared with the 20.0% recorded in 2025.

    Unilever also confirmed that its proposed combination of its Foods business with McCormick remains on schedule, subject to regulatory and shareholder approvals.

    Third-Quarter Turnover Increases 6.7% to €13.3 Billion

    Unilever reported turnover of €13.3 billion for the three months ended 30 September 2026, compared with €12.4 billion in the corresponding period last year.

    The 6.7% reported increase reflected underlying sales growth of 5.2%, a net contribution of 0.8% from acquisitions and disposals, and a positive currency-related impact of 0.6%.

    Underlying sales growth comprised 2.9% volume growth and 2.3% price growth.

    The company said pricing increased during the quarter in response to higher commodity costs, particularly within Home Care and Personal Care.

    Unilever’s Power Brands recorded underlying sales growth of 5.8%, including volume growth of 3.3%.

    Performance varied across geographic markets, with emerging markets contributing most of the group’s underlying sales growth.

    Nine-Month Turnover Reaches €38.9 Billion

    For the first nine months of 2026, Unilever reported turnover of €38.9 billion, representing an increase of 2.7% from €37.9 billion in the corresponding period of 2025.

    Underlying sales growth for the nine-month period was 4.9%, comprising volume growth of 3.8% and price growth of 1.1%.

    Acquisitions contributed 1.3% to reported turnover growth, while disposals reduced it by 0.6%.

    Currency-related movements had a negative impact of 2.9%.

    The group reported a two-year compound annual growth rate of 4.1% for underlying sales and 2.5% for underlying volume.

    The nine-month performance was supported by growth in Home Care, Personal Care and Beauty & Wellbeing, while Foods recorded lower reported turnover.

    Full-Year Volume Growth Forecast Raised to at Least 3%

    Following its third-quarter performance, Unilever increased its underlying volume growth expectation for 2026.

    The company now forecasts volume growth of at least 3% for the full year.

    It also expects underlying sales growth of approximately 5% during the second half.

    Unilever maintained its multi-year underlying sales growth guidance range of 4% to 6% for 2026.

    The group continues to anticipate a modest improvement in its underlying operating margin compared with the 20.0% achieved in 2025.

    The revised volume outlook reflects performance during the first nine months and management’s expectations for the remainder of the year.

    Beauty & Wellbeing Sales Rise 9.5% to €3.5 Billion

    Unilever’s Beauty & Wellbeing division reported third-quarter turnover of €3.5 billion, an increase of 9.5% compared with the previous year.

    Underlying sales grew 5.7%, comprising volume growth of 3.6% and price growth of 2.1%.

    For the first nine months, turnover reached €10.0 billion, up 3.4%, while underlying sales increased 5.8%.

    Hair Care recorded double-digit growth during the quarter, supported by higher volumes and demand across several brands.

    Dove, Sunsilk, Clear and K18 each reported double-digit growth.

    Dove benefited from product developments in serums, masks and scalp care, alongside sales growth in India and the United States.

    Sunsilk and Clear recorded growth across Latin America and South East Asia.

    The prestige hair care brand K18 also delivered double-digit growth.

    Skin Care Growth Offsets Decline in Wellbeing

    Within Beauty & Wellbeing, Skin Care recorded mid-single-digit underlying sales growth.

    Vaseline reported double-digit growth, supported by performance across several markets, particularly in Asia Pacific Africa.

    The company’s prestige skin care portfolio also contributed, including Hourglass, Paula’s Choice and Dermalogica.

    However, Wellbeing sales declined by a high-single-digit percentage during the quarter.

    Unilever attributed part of the reduction to shipment timing associated with Amazon Prime Day, which had benefited second-quarter sales.

    For the first nine months, Wellbeing underlying sales declined 1.0%.

    The company also reported changes in channel distribution and pricing arrangements, including reduced distribution and private-label competition affecting Liquid I.V. in the club retail channel.

    Management said measures to improve customer acquisition for Nutrafol remained at an early stage.

    Grüns recorded growth during its first full quarter under Unilever ownership but will not be included in underlying sales growth calculations until June 2027.

    Unilever expects Wellbeing performance to improve sequentially from the third quarter.

    Personal Care Underlying Sales Increase 6.3%

    Unilever’s Personal Care division reported third-quarter turnover of €3.6 billion, up 9.7% from the previous year.

    Underlying sales growth was 6.3%, consisting of 3.8% volume growth and 2.4% price growth.

    For the first nine months, turnover increased 6.2% to €10.5 billion, while underlying sales grew 5.3%.

    Skin cleansing products recorded high-single-digit growth, while deodorants increased by a mid-single-digit percentage.

    Dove, the group’s largest brand, reported double-digit growth, including mid-single-digit volume growth.

    Unilever said growth was recorded across emerging markets and the United States.

    The company also increased prices during the quarter to reflect higher commodity costs.

    Deodorants and Skin Cleansing Contribute to Personal Care Growth

    Deodorants recorded mid-single-digit growth during the quarter, supported by higher sales volumes.

    Emerging markets reported double-digit growth, including double-digit increases in Latin America and high-single-digit growth in Asia Pacific Africa.

    US deodorant sales increased by a mid-single-digit percentage.

    Unilever said its FIFA World Cup 2026 sponsorship contributed to brand activity during the period.

    Dove deodorants recorded double-digit growth.

    Skin cleansing also increased by a high-single-digit percentage, supported by both volume and pricing.

    The company reported double-digit growth in emerging markets and mid-single-digit increases in North America and Europe.

    Dove’s body serum product ranges contributed to the category’s performance.

    Wild and Dr. Squatch also recorded double-digit growth, with Dr. Squatch included in underlying sales calculations from September.

    Oral Care declined by a low-single-digit percentage, as growth in India and South East Asia was offset by lower sales in Europe.

    Home Care Reports 9.1% Underlying Sales Growth

    Home Care generated third-quarter turnover of €3.1 billion, an increase of 7.5% compared with the previous year.

    Underlying sales growth reached 9.1%, comprising volume growth of 5.4% and price growth of 3.6%.

    For the first nine months, Home Care turnover totalled €9.0 billion, up 3.6%, while underlying sales increased 8.1%.

    Growth was led by emerging markets, particularly India and Brazil.

    Unilever reported double-digit growth in Asia Pacific Africa and Latin America.

    Higher commodity costs contributed to increased pricing during the quarter, and the company expects further pricing effects during the remainder of the year.

    Fabric Cleaning and Household Products Support Home Care Performance

    Fabric Cleaning recorded double-digit underlying sales growth, supported by high-single-digit volume growth.

    Price increases also contributed, with category pricing growth reaching a mid-single-digit percentage.

    Unilever reported double-digit Fabric Cleaning growth in India and Brazil.

    The company said its market share in India reached record levels during the quarter.

    Home & Hygiene products recorded mid-single-digit growth, with contributions from volume and pricing.

    Cif delivered double-digit growth, supported by its Infinite Clean product range and expansion into additional markets.

    Fabric Enhancers also grew by a mid-single-digit percentage, led by Comfort and demand across Asia Pacific Africa.

    Foods Sales Remain Broadly Unchanged at €3.1 Billion

    Unilever’s Foods division reported third-quarter turnover of €3.1 billion, unchanged on a reported basis from the previous year.

    Underlying sales increased 0.1%, with price growth of 1.3% offsetting a volume decline of 1.1%.

    For the first nine months, Foods turnover declined 2.6% to €9.4 billion.

    Underlying sales growth for the nine-month period was 0.8%.

    The company reported growth in emerging markets and its Unilever Food Solutions business, offset by lower retail sales in developed markets.

    Unilever cited subdued market conditions and increased competition in US condiments.

    Management is implementing product innovation and pricing measures intended to improve the performance of its US Foods business.

    Condiments and Cooking Aids Record Flat Sales

    Underlying sales in Cooking Aids remained broadly unchanged, as price increases offset lower volumes.

    Growth in South East Asia, Brazil and Africa was balanced by declines in developed markets.

    Condiments also recorded broadly flat underlying sales.

    Unilever said its US portfolio had lower exposure to some faster-growing segments, including premium and avocado mayonnaise.

    The company is introducing products and adjusting pricing to address these competitive conditions.

    Unilever Food Solutions recorded low-single-digit growth, supported by a mid-single-digit increase in North America.

    China also contributed low-single-digit growth.

    In India, Foods recorded high-single-digit growth, supported by double-digit growth in Horlicks.

    Emerging Markets Deliver 9.5% Underlying Sales Growth

    Unilever reported third-quarter emerging market turnover of €8.0 billion, with underlying sales growth of 9.5%.

    Volume increased 6.0%, while pricing contributed 3.3%.

    For the first nine months, emerging market turnover reached €23.5 billion, with underlying sales growth of 7.9%.

    Growth was recorded across several major markets, including India, Turkey, Vietnam, Pakistan, Latin America, Indonesia and South East Asia.

    India, Turkey, Vietnam and Pakistan each recorded double-digit underlying sales growth.

    Latin America, Indonesia and South East Asia reported high-single-digit increases.

    The company said emerging market performance contributed to group volume growth during the quarter.

    India Records 15% Underlying Sales Growth

    Unilever reported underlying sales growth of 15% in India during the third quarter, including volume growth of 7%.

    The company said the performance reflected growth across its principal business groups and a lower comparative base from the previous year.

    Home Care and Beauty & Wellbeing recorded double-digit increases.

    Personal Care and Foods grew by high-single-digit percentages.

    Hair Care was a contributor, supported by demand for Dove and TRESemmé products.

    India remained one of the principal contributors to the group’s emerging market performance.

    Asia Pacific Africa Sales Increase 10.1%

    The Asia Pacific Africa region generated turnover of €6.0 billion during the third quarter.

    Underlying sales growth was 10.1%, comprising volume growth of 5.8% and price growth of 4.1%.

    For the first nine months, regional turnover reached €17.3 billion, with underlying sales growth of 8.3%.

    Indonesia recorded 7% growth, supported by volume increases across Home Care, Personal Care and Beauty & Wellbeing.

    China reported low-single-digit growth, with mid-single-digit volume increases and contributions from all business groups.

    Unilever said social commerce activity supported performance in China, alongside new products within its Beauty & Wellbeing and Personal Care portfolios.

    Africa recorded mid-single-digit growth, supported by Vaseline, Home Care and Foods.

    Americas Revenue Reaches €5.0 Billion

    Unilever’s Americas business reported third-quarter turnover of €5.0 billion.

    Underlying sales growth was 2.8%, comprising volume growth of 0.9% and price growth of 1.8%.

    For the first nine months, turnover reached €14.7 billion, with underlying sales growth of 4.0%.

    Performance differed between North America and Latin America.

    North American underlying sales declined 0.7% during the quarter, although the company reported continued volume market share gains.

    Growth in Personal Care and Beauty was offset by lower sales in Wellbeing and Foods.

    Latin America recorded underlying sales growth of 8.5%, including volume growth of 6.5%.

    Brazil reported high-single-digit growth, supported by double-digit volume increases.

    Mexico recorded low-single-digit growth, while Argentina reported double-digit growth.

    European Underlying Sales Decline 1.7%

    Unilever reported third-quarter turnover of €2.3 billion in Europe.

    Underlying sales declined 1.7%, comprising a 0.4% reduction in volume and a 1.3% decline in pricing.

    For the first nine months, European turnover reached €6.9 billion, with underlying sales down 1.2%.

    Beauty & Wellbeing recorded mid-single-digit growth, while Personal Care increased by a low-single-digit percentage.

    The company reported growth in Dove products and deodorants.

    However, these increases were offset by lower sales in Home Care and Foods.

    Unilever attributed the declines to subdued market conditions in the region.

    Unilever Foods Combination With McCormick Remains on Schedule

    Unilever confirmed that preparations for the proposed combination of its Foods business with McCormick are progressing.

    The transaction was announced in March 2026 and is intended to separate Unilever’s Foods operations from its remaining consumer goods businesses.

    The company said more than 200 employees are working across 20 cross-functional teams on separation and integration activities.

    Regulatory filings have been submitted according to the planned timetable.

    The transaction remains subject to approval from McCormick shareholders, receipt of required regulatory approvals and satisfaction of other customary closing conditions.

    Consultation with relevant works councils is also underway.

    Unilever said it expects the consultation process to be completed before the transaction closes.

    The company did not announce a revised completion date.

    Portfolio Restructuring Continues Following Ice Cream Demerger

    The proposed Foods combination follows the December 2025 demerger of The Magnum Ice Cream Company.

    Together, these transactions form part of Unilever’s programme to reshape its business portfolio.

    Following the proposed Foods separation, the remaining business would be more concentrated on Beauty & Wellbeing, Personal Care and Home Care.

    Unilever said it continues to prioritise investment in growth and productivity, alongside selective acquisitions and disposals.

    No bolt-on acquisitions were completed during the third quarter.

    In August 2026, the company completed the disposal of its Home Care businesses in Colombia.

    The group also intends to continue returning capital to shareholders through dividends and potential share repurchases.

    Quarterly Dividend Increases 3% Year-on-Year

    Unilever declared a third-quarter interim dividend of €0.4664 per ordinary share.

    The payment is unchanged from the second-quarter 2026 dividend and represents an increase of 3.0% compared with the third quarter of 2025.

    For ordinary shares traded on the London Stock Exchange, the dividend is equivalent to £0.3907 per share.

    For shares traded on Euronext Amsterdam, the payment is €0.4664 per share.

    American Depositary Receipt holders will receive US$0.5219 per ADR.

    The currency conversions were determined using applicable exchange rates dated 26 October 2026.

    The shares are scheduled to trade ex-dividend on 12 November 2026, while the ex-dividend date for ADRs is 13 November.

    The record date is 13 November, with the deadline for dividend reinvestment elections set for 27 November.

    Payment is scheduled for 18 December 2026.

    CEO Fernando Fernandez Comments on Quarterly Performance

    Fernando Fernandez, Chief Executive Officer of Unilever, commented on the company’s sales performance and revised volume expectations.

    “We have delivered another quarter of competitive growth, led by continued strong volume delivery and a step up in price to offset the impact of higher commodity costs. Our Power Brands continued to lead performance, with strong growth across Home Care, Personal Care and Beauty & Wellbeing. Emerging markets were again a key driver, with broad-based growth across markets, led by India and continued strength in Latin America and South East Asia. Developed market performance reflected tougher prior year comparators and softer performance in Foods.

    We are performing while transforming Unilever. We are becoming simpler and sharper, with greater focus and stronger execution as we drive Desire at Scale across our brands. This progress gives us confidence that we will now deliver at least 3% volume growth for the full year.

    At our Investor Event next week we will set out how this transformation is creating a stronger, more focused Unilever capable of delivering sustained, competitive performance.”

    Investor Event Scheduled for November

    Unilever is scheduled to hold an investor event in New York on 4 November 2026.

    The company intends to provide further information about its business transformation, portfolio strategy and operational priorities.

    The event follows the third-quarter trading statement and the revision to the group’s full-year volume growth outlook.

    Unilever’s fourth-quarter and full-year 2026 results are scheduled for publication on 11 February 2027.

    Outlook for the Remainder of 2026

    Unilever expects underlying sales growth of between 4% and 6% for the full year, with underlying volume growth of at least 3%.

    The company anticipates second-half underlying sales growth of approximately 5% and a modest improvement in underlying operating margin compared with 2025.

    Performance during the third quarter was supported by growth in Home Care, Personal Care and Beauty & Wellbeing, particularly across emerging markets.

    Foods remained broadly unchanged on an underlying sales basis, while developed markets recorded lower sales.

    Unilever continues to implement pricing changes in response to commodity costs and is progressing its proposed Foods combination with McCormick.

    Further information about its business strategy is expected at the November investor event.

    More About Unilever

    Unilever PLC is a London-listed multinational consumer goods company operating across Beauty & Wellbeing, Personal Care, Home Care and Foods.

    Its portfolio includes brands such as Dove, Vaseline, Sunsilk, Clear, TRESemmé, Cif, Comfort, Hellmann’s and Horlicks.

    The company sells products across developed and emerging markets, with operations spanning Asia Pacific Africa, the Americas and Europe.

    Unilever completed the demerger of The Magnum Ice Cream Company in December 2025 and announced an agreement in March 2026 to combine its Foods business with McCormick.

    The group continues to develop its consumer goods portfolio while investing in product innovation, distribution and operational efficiency.

  • GSK Reports 4% Rise in Q3 Sales to £8.9 Billion, Beats Earnings Forecasts and Maintains Full-Year Guidance

    GSK Reports 4% Rise in Q3 Sales to £8.9 Billion, Beats Earnings Forecasts and Maintains Full-Year Guidance

    GSK plc (LSE:GSK) reported a 4% increase in third-quarter sales to £8.9 billion, supported by growth in its Specialty Medicines business, while core earnings per share exceeded analysts’ expectations.

    The British pharmaceutical company recorded core earnings per share of 54.6 pence for the three months ended 30 September 2026, compared with a company-compiled analyst consensus of 50.4 pence.

    Revenue increased 5% at constant exchange rates, with demand for HIV, respiratory, immunology and oncology medicines contributing to the quarterly performance.

    GSK maintained its full-year and longer-term financial targets despite reporting declines in total operating profit and statutory earnings per share, partly reflecting restructuring charges associated with its Accelerate Growth programme.

    The company also generated £3.1 billion in operating cash flow and £2.1 billion in free cash flow during the quarter.

    Third-Quarter Revenue Increases to £8.9 Billion

    GSK reported total sales of £8.9 billion for the third quarter of 2026, representing growth of 4% at actual exchange rates and 5% at constant exchange rates.

    The increase was primarily supported by the Specialty Medicines division, where sales rose across HIV, respiratory, immunology and inflammation, and oncology treatments.

    General Medicines revenue remained broadly unchanged, while Vaccines recorded a decline.

    The company attributed its core earnings performance to higher revenue, changes in its product and geographic sales mix, and increased royalty income.

    These factors were partly offset by higher research and development expenditure, investment in new product launches and increased financing costs.

    Core Earnings Per Share Exceed Analyst Expectations

    GSK reported core earnings per share of 54.6 pence, exceeding the company-compiled analyst consensus of 50.4 pence.

    The result was approximately 8.3% above the consensus estimate.

    Core earnings per share increased 1% compared with the corresponding period last year.

    Core operating profit rose 5%, reflecting revenue growth and the contribution from higher-margin products and royalty income.

    The increase was partly offset by additional spending on research and development, commercial investment associated with new medicines and higher finance costs.

    Core financial measures exclude certain items included in statutory results, including specified restructuring and other adjustments.

    Specialty Medicines Sales Rise 15% to £3.9 Billion

    GSK’s Specialty Medicines division reported third-quarter sales of £3.9 billion, representing growth of 15%.

    The division accounted for approximately 44% of total group revenue during the period.

    Growth was recorded across its principal therapeutic categories, including HIV, respiratory, immunology and inflammation, and oncology.

    The performance reflected continued demand for the company’s specialty treatments.

    Specialty Medicines was the main contributor to group revenue growth during the quarter, offsetting the decline in Vaccines sales and relatively unchanged revenue in General Medicines.

    HIV Medicines Revenue Increases 10%

    GSK reported HIV medicines sales of £2.1 billion during the third quarter, an increase of 10%.

    The HIV portfolio represented the largest component of Specialty Medicines revenue.

    The company continues to develop and commercialise treatments in this therapeutic area as part of its broader specialty pharmaceuticals business.

    The quarterly figures indicate that HIV medicines remained a contributor to group sales growth.

    GSK did not provide individual HIV product sales figures in the supplied quarterly summary.

    Respiratory, Immunology and Inflammation Sales Grow 21%

    Sales from respiratory, immunology and inflammation medicines increased 21% to £1.1 billion.

    The category contributed to the overall growth of Specialty Medicines during the quarter.

    GSK’s investment in these therapeutic areas forms part of its strategy to expand its portfolio of specialty treatments.

    The company has also continued to allocate research and development resources towards new medicines and potential product launches.

    The supplied results did not specify the contribution of individual products within this category.

    Oncology Revenue Advances 23%

    GSK’s oncology business reported third-quarter revenue of £0.6 billion, an increase of 23%.

    The category recorded the highest percentage sales growth among the Specialty Medicines areas disclosed in the update.

    Oncology remains part of GSK’s strategy to expand its portfolio of specialist medicines.

    The company’s investment in research, development and new product launches contributed to higher operating expenditure during the period.

    The quarterly summary did not provide a breakdown of sales by individual oncology treatment.

    Vaccines Revenue Declines 2% to £2.6 Billion

    GSK reported Vaccines sales of £2.6 billion for the third quarter, representing a decline of 2%.

    Performance varied across the company’s vaccine portfolio.

    Sales of Shingrix, the company’s shingles vaccine, decreased 5% to £0.8 billion.

    Meningitis vaccine revenue increased 12% to £0.6 billion, partially offsetting declines elsewhere in the division.

    Arexvy, GSK’s respiratory syncytial virus vaccine, recorded sales of £0.2 billion, down 24%.

    The differences in performance across these products contributed to the overall reduction in Vaccines revenue.

    The company did not provide detailed explanations for the individual vaccine sales movements in the supplied summary.

    General Medicines Revenue Remains Stable at £2.4 Billion

    GSK’s General Medicines division recorded third-quarter sales of £2.4 billion, broadly unchanged from the corresponding period last year.

    Within the division, Trelegy generated revenue of £0.8 billion, an increase of 8%.

    The product’s growth contributed to the performance of the General Medicines portfolio.

    However, the division’s overall revenue remained stable, indicating that growth in Trelegy was offset by movements elsewhere in the business.

    General Medicines accounted for approximately 27% of group sales during the quarter.

    Statutory Operating Profit Falls 16% Following Restructuring Charges

    Although core operating profit increased, GSK reported a 16% decline in total operating profit.

    Total earnings per share fell 21%.

    The statutory results were affected by £328 million in restructuring charges associated with the company’s Accelerate Growth programme.

    Lower other net operating income also contributed to the decline.

    These effects were partly offset by growth in core operating profit.

    The difference between statutory and core earnings reflects the impact of items excluded from the company’s adjusted performance measures.

    The Accelerate Growth programme forms part of management’s efforts to adjust the group’s operating structure and cost base.

    The supplied results did not specify the total expected savings or implementation timetable for the programme.

    Operating Cash Flow Reaches £3.1 Billion

    GSK reported cash generated from operations of £3.1 billion during the third quarter.

    Free cash flow totalled £2.1 billion.

    The cash flow figures provide a separate measure of the company’s financial performance alongside reported and core earnings.

    Cash generation remains relevant to GSK’s ability to fund research and development, commercial investment, restructuring activities and other corporate requirements.

    The supplied quarterly summary did not include comparative cash flow figures for the corresponding period of 2025.

    Full-Year and Long-Term Financial Targets Maintained

    GSK reaffirmed its annual and longer-term financial targets following the third-quarter results.

    The decision came despite restructuring charges affecting statutory profitability and mixed performance across the company’s operating divisions.

    Specialty Medicines continued to support group revenue growth, while General Medicines sales remained stable and Vaccines revenue declined.

    The company is also continuing its Accelerate Growth programme and investing in research, development and new product launches.

    GSK did not revise its financial guidance in the supplied announcement.

    The specific numerical ranges for its full-year and longer-term targets were not included in the source material.

    CEO Luke Miels Continues Focus on Growth and Portfolio Development

    The results come as Chief Executive Officer Luke Miels oversees initiatives intended to accelerate growth and prepare GSK for future patent expiries.

    The company’s strategy includes investment in specialty medicines, research and development, product launches and changes to its operating cost structure.

    During the third quarter, sales growth in HIV, respiratory, immunology and oncology medicines contributed to the group’s overall financial performance.

    At the same time, the company continued to incur restructuring costs associated with its Accelerate Growth programme.

    GSK’s ability to maintain revenue growth over the longer term will depend partly on the commercial performance of existing products, new medicine launches and the impact of patent expiries.

    Outlook for the Remainder of 2026

    GSK enters the final quarter of 2026 having reported nine-month progress that allowed it to maintain its annual financial targets.

    Third-quarter sales growth was led by Specialty Medicines, with HIV, respiratory, immunology and oncology products recording increases.

    The Vaccines division reported lower revenue, reflecting declines in Shingrix and Arexvy sales, while General Medicines remained broadly stable.

    Core operating profit and core earnings per share increased, although statutory profitability was affected by restructuring charges and lower other net operating income.

    The company continues to invest in its product portfolio and implement its Accelerate Growth programme.

    GSK has not announced changes to its full-year or longer-term financial objectives.

    More About GSK

    GSK plc is a London-listed global biopharmaceutical company focused on the research, development, manufacture and commercialisation of medicines and vaccines.

    The company operates across three principal commercial divisions: Specialty Medicines, Vaccines and General Medicines.

    Its therapeutic areas include HIV, respiratory diseases, immunology, inflammation, oncology and infectious diseases.

    GSK’s product portfolio includes Shingrix, Arexvy and Trelegy, alongside a range of specialist medicines and vaccines.

    The company continues to invest in research and development while implementing operational initiatives intended to support its longer-term business objectives.

  • S4Capital Reports 6.4% Decline in Q3 Net Revenue to £156.3 Million, Maintains £85 Million EBITDA Target

    S4Capital Reports 6.4% Decline in Q3 Net Revenue to £156.3 Million, Maintains £85 Million EBITDA Target

    S4Capital plc (LSE:SFOR) reported a 6.4% decline in third-quarter net revenue to £156.3 million, compared with £167.0 million a year earlier, as reduced spending by technology clients and broader economic uncertainty continued to affect demand for digital advertising and marketing services.

    The digital marketing and technology group recorded a 7.3% decline in net revenue on a like-for-like basis for the three months ended 30 September 2026.

    For the first nine months of the year, reported net revenue fell 6.2% to £464.3 million, while like-for-like net revenue declined 5.6%.

    S4Capital now expects full-year like-for-like net revenue to be marginally below its previous guidance for a high-single-digit percentage decline. However, the company maintained its operational EBITDA target at the current analyst consensus level of £85 million.

    The group also reported a reduction in net debt to £76.0 million at the end of September, compared with £151.1 million a year earlier, supported by working capital management and cash generation.

    Third-Quarter Net Revenue Declines 6.4%

    S4Capital reported third-quarter net revenue of £156.3 million, down from £167.0 million in the corresponding period of 2025.

    The reported decline of 6.4% compared with a 7.3% reduction on a like-for-like basis.

    Total revenue, before deducting direct costs, fell 9.5% to £173.5 million from £191.7 million.

    On a like-for-like basis, total revenue declined 10.3%.

    Gross billings decreased 12.4% to £430.0 million, compared with £490.9 million a year earlier, representing a 13.0% decline on a like-for-like basis.

    The company attributed the trading performance to cautious customer spending, geopolitical uncertainty and changes in investment priorities among major technology clients.

    S4Capital said some customers continued to allocate more expenditure towards artificial intelligence infrastructure rather than operational marketing budgets.

    Nine-Month Net Revenue Falls to £464.3 Million

    For the nine months ended 30 September 2026, S4Capital recorded net revenue of £464.3 million, compared with £495.2 million in the previous year.

    This represented a reported decline of 6.2% and a like-for-like reduction of 5.6%.

    Total revenue decreased 6.3% to £517.5 million from £552.1 million, while like-for-like revenue fell 5.7%.

    Billings for the nine-month period totalled £1.322 billion, compared with £1.417 billion in the corresponding period of 2025.

    The reported reduction in billings was 6.7%, while the like-for-like decline was 5.6%.

    The company said trading conditions during the third quarter remained consistent with the challenges experienced during the first half of the year.

    Full-Year Revenue Outlook Revised

    S4Capital has revised its expectations for full-year 2026 net revenue.

    The company now anticipates that like-for-like net revenue will be marginally below its previous guidance, which had indicated a high-single-digit percentage decline.

    Despite the revised revenue outlook, management maintained its operational EBITDA target at £85 million, in line with current analyst consensus.

    The company expects its operational EBITDA margin to increase by at least 160 basis points to 13.7%.

    This reflects the impact of cost reduction measures introduced during the second half of 2025, alongside continued expenditure management.

    S4Capital also expects adjusted basic earnings per share to exceed the current analyst consensus of 6.1 pence per share.

    The operational EBITDA figure represents a management target rather than a formal profit forecast.

    Marketing Services Net Revenue Declines 6.2% Like-for-Like

    The Marketing Services division reported third-quarter net revenue of £142.7 million, compared with £150.8 million a year earlier.

    This represented a reported decline of 5.4% and a like-for-like reduction of 6.2%.

    For the first nine months of 2026, Marketing Services generated net revenue of £424.6 million, down from £449.8 million in the corresponding period last year.

    The nine-month decline was 5.6% on a reported basis and 5.0% like-for-like.

    S4Capital said the division continued to experience reduced spending from technology clients, particularly those prioritising capital expenditure on AI infrastructure.

    The company also reported a reduction in the scope of its work for BMW, primarily affecting operations in Europe, the Middle East and Africa.

    The continuing conflicts in Ukraine and the Middle East were also identified as factors affecting client spending decisions.

    Marketing Services remains the group’s largest operating practice, accounting for approximately 91% of net revenue.

    Technology Services Revenue Falls Amid Longer Sales Cycles

    S4Capital’s Technology Services division reported third-quarter net revenue of £13.6 million, compared with £16.2 million a year earlier.

    The reported decline was 16.0%, while the like-for-like reduction reached 17.6%.

    For the first nine months, Technology Services net revenue decreased to £39.7 million from £45.4 million.

    This represented a reported decline of 12.6% and a like-for-like reduction of 11.0%.

    The company attributed the performance to macroeconomic conditions and extended customer sales cycles.

    Technology Services accounts for approximately 9% of group net revenue.

    S4Capital continues to develop its technology and AI-related services, although the division’s financial performance remains affected by the timing of customer investment decisions.

    Americas Net Revenue Declines 9% in Third Quarter

    The Americas remained S4Capital’s largest geographic market during the third quarter.

    Reported net revenue in the region declined 9.0% to £123.9 million, compared with £136.1 million in the same period last year.

    On a like-for-like basis, net revenue decreased 10.0%.

    For the first nine months of 2026, Americas net revenue totalled £373.8 million, down from £394.3 million.

    This represented a reported decline of 5.2% and a like-for-like reduction of 4.1%.

    The region accounted for approximately 81% of group net revenue.

    The performance reflected the wider slowdown in marketing expenditure among technology and other corporate clients.

    EMEA Returns to Quarterly Revenue Growth

    S4Capital reported improved third-quarter trading in Europe, the Middle East and Africa.

    EMEA net revenue increased 2.2% to £23.1 million, compared with £22.6 million a year earlier.

    On a like-for-like basis, revenue rose 3.1%.

    However, the region remained below the previous year’s level for the first nine months.

    Year-to-date net revenue declined 12.5% to £65.1 million from £74.4 million.

    The like-for-like reduction was 13.3%.

    S4Capital said the region’s performance continued to reflect the impact of reduced customer spending and changes in contract scope, including work undertaken for BMW.

    The improvement in third-quarter trading did not fully offset the declines recorded earlier in the year.

    Asia-Pacific Net Revenue Rises 12% in Third Quarter

    The Asia-Pacific region reported third-quarter net revenue of £9.3 million, compared with £8.3 million in the corresponding period of 2025.

    This represented reported growth of 12.0% and a like-for-like increase of 9.4%.

    For the first nine months, however, net revenue declined 4.2% to £25.4 million from £26.5 million.

    The like-for-like reduction for the nine-month period was 5.6%.

    The company said the region experienced an improvement in trading momentum during the third quarter.

    Asia-Pacific accounted for approximately 5% of group net revenue.

    AI Services and New Business Activity Continue

    S4Capital reported further commercial activity involving its artificial intelligence and digital transformation services.

    The company said existing customers in the automotive, financial services and fast-moving consumer goods sectors were increasingly moving from AI pilot projects towards broader implementation.

    S4Capital’s proprietary AI tools remain part of its new business offering.

    During the first nine months of 2026, the group expanded its automotive customer base and extended the geographic scope of an existing major consumer goods account from North America to international markets.

    The company also reported assignments involving Google, Amazon, T-Mobile, Hackensack, Presight, Nubank, Crusoe, Staples and Nike.

    These projects span creative services, media, technology and AI-related business transformation.

    S4Capital did not disclose the financial value of the individual assignments or quantify their expected contribution to future revenue.

    Monks.Flow Receives AI Marketing Award

    S4Capital reported that its Monks.Flow platform received the AI-based Marketing Solution of the Year award at the AI Breakthrough Awards.

    The recognition followed previous awards from Adweek, The One Show and Business Intelligence Group.

    Monks.Flow forms part of the group’s AI-related marketing and production capabilities.

    The company continues to develop its commercial offering around four principal propositions: Orchestration Partner, Real-Time Brands, Media Acceleration and Digital Transformation.

    These services combine data, content production, media management and technology platforms.

    Management said the offerings are intended to address customer requirements for personalised marketing, social media activity and digital transformation.

    Net Debt Falls by £75.1 Million Year-on-Year

    S4Capital reported net debt of £76.0 million at 30 September 2026, compared with £151.1 million at the same point last year.

    The reduction of £75.1 million reflected working capital management and improved liquidity.

    On a like-for-like basis, net debt decreased by £66.0 million.

    The company’s leverage ratio stood at 0.7 times pro-forma trailing 12-month operational EBITDA.

    This was below its internal target of 1.0 times and the principal debt covenant limit of 4.5 times.

    S4Capital said its debt maturity profile and available liquidity continued to support its financial position.

    The group maintained its year-end net debt target range of £50 million to £80 million and expects to finish the year comfortably within those limits.

    Net debt excludes lease liabilities.

    Further €50.9 Million of Term Loan B Repurchased

    Following the end of September, S4Capital repurchased a further €50.9 million of its Term Loan B debt.

    Of this amount, €10.5 million remained subject to settlement at the time of the announcement.

    The latest transactions follow €125.3 million of previous repurchases.

    Together, the transactions reduce the outstanding Term Loan B balance to €198.8 million from an original €375 million.

    The company continues to prioritise debt reduction as part of its capital allocation strategy.

    Management also indicated that further debt repurchases may take place as the group’s financial position develops.

    The company’s stated capital allocation priorities are dividend payments, additional debt repurchases and, subsequently, share buybacks as net debt declines.

    First Interim Dividend Paid in October

    S4Capital paid its first interim dividend of 1.35 pence per share on 6 October 2026.

    The payment represented 50% of adjusted basic earnings per share for the relevant period.

    The board has adopted a dividend policy targeting a payout ratio of 50% of adjusted basic earnings per share, subject to the achievement of financial targets.

    S4Capital intends to recommend a final dividend for 2026 in accordance with that policy, provided the relevant conditions are met.

    The company has not announced the amount of the proposed final dividend.

    Future distributions will remain subject to financial performance and board approval.

    Cost Management Supports Margin Expectations

    S4Capital said the annualised effects of cost reduction measures implemented during the second half of 2025 became more evident during the third quarter.

    The company continues to manage expenditure in response to lower revenue and changes in customer demand.

    These measures are expected to support an increase in the operational EBITDA margin to at least 13.7% for the full year.

    The forecast represents an improvement of at least 160 basis points.

    Management expects operational EBITDA to remain at approximately £85 million despite the revised net revenue outlook.

    The company did not provide a separate third-quarter operational EBITDA figure or quantify the contribution of individual cost reduction measures.

    Executive Chairman Comments on Trading Conditions

    Sir Martin Sorrell, Executive Chairman of S4Capital, attributed the group’s performance to changes in client spending and the wider economic environment.

    “Throughout the third quarter, our trading continued to reflect increasingly volatile global macroeconomic conditions, heightened by rising geopolitical risks. Clients remained cautious amid this uncertainty, with hyperscalers and other technology clients continuing to prioritise capital expenditure on expanding AI capacity over operating expenditure. The four biggest hyperscalers are projected to spend over $5 trillion on AI-related capital expenditure between 2025 and 2030.”

    Sorrell said the company expects cautious client spending to continue in the near term, particularly against the background of geopolitical uncertainty.

    He also pointed to opportunities associated with the adoption of AI and other technologies across corporate operations.

    Commenting on the financial outlook, Sorrell said:

    “In the third quarter, we saw the annualised impact of the cost actions taken in the second half of 2025 and have continued our disciplined cost management. We now expect 2026 like-for-like net revenue to be marginally below previous guidance down high-single digits, with operational EBITDA remaining at current analyst consensus level of £85 million and operational EBITDA margin now expected to increase by at least 160 basis points to 13.7%.”

    Board and Leadership Changes Confirmed

    S4Capital also confirmed changes to its board and executive leadership arrangements.

    Nirvik Singh has moved into a full-time executive role leading the Marketing Services practice across EMEA and Asia-Pacific.

    As a result, he stepped down as a non-executive director and as chair of the Nomination and Remuneration Committee, effective 30 September 2026.

    Alina Kessel, an existing non-executive director, became chair of the Nomination and Remuneration Committee on the same date.

    Christian Juhl has joined the board as a non-executive director.

    The company did not announce further changes to its executive management structure.

    Sustainability and Employee Development Initiatives Continue

    S4Capital reported further activity under its environmental, social and governance programme.

    The company said it had strengthened ESG data governance during the third quarter to improve the quality and traceability of sustainability information.

    Its EcoVadis assessment improved from the 77th percentile to the 82nd percentile of companies assessed, while the group retained its Bronze medal.

    S4Capital also continued employee development initiatives, including AI training through its School of AI programme.

    The company is incorporating previously introduced corporate values into performance management processes and working towards a more consistent employee merit review cycle.

    Outlook for the Remainder of FY2026

    S4Capital expects like-for-like net revenue for 2026 to decline by slightly more than the high-single-digit percentage indicated in its previous guidance.

    The group maintained its operational EBITDA target at £85 million and expects its operational EBITDA margin to reach at least 13.7%.

    Adjusted basic earnings per share are expected to exceed the current analyst consensus of 6.1 pence.

    Management continues to target year-end net debt of between £50 million and £80 million, following a reduction to £76.0 million at the end of September.

    The company is also continuing to reduce its Term Loan B balance and intends to maintain its dividend policy, subject to financial performance.

    S4Capital expects client spending to remain cautious in the near term, while continuing to pursue opportunities in AI-related marketing services and digital transformation.

    More About S4Capital

    S4Capital plc is a London-listed digital advertising, marketing and technology services group founded by Sir Martin Sorrell.

    The company operates through two principal practices: Marketing Services and Technology Services.

    Its activities include digital advertising, content production, media management, data services, technology consulting and AI-related business transformation.

    S4Capital employs approximately 6,100 people across 34 countries.

    The Americas account for approximately 81% of group net revenue, followed by EMEA at 14% and Asia-Pacific at 5%.

    Marketing Services contributes approximately 91% of net revenue, while Technology Services accounts for the remaining 9%.

  • Georgina Energy Outlines 8–10 Week Rig Mobilisation Plan for Hussar Helium and Hydrogen Project

    Georgina Energy Outlines 8–10 Week Rig Mobilisation Plan for Hussar Helium and Hydrogen Project

    Georgina Energy Plc (LSE:GEX) has outlined a revised mobilisation plan for its Hussar EP513 helium, hydrogen and natural gas exploration project in Western Australia, with drilling preparations expected to take approximately eight to ten weeks once formal authorisation to begin mobilisation activities is issued.

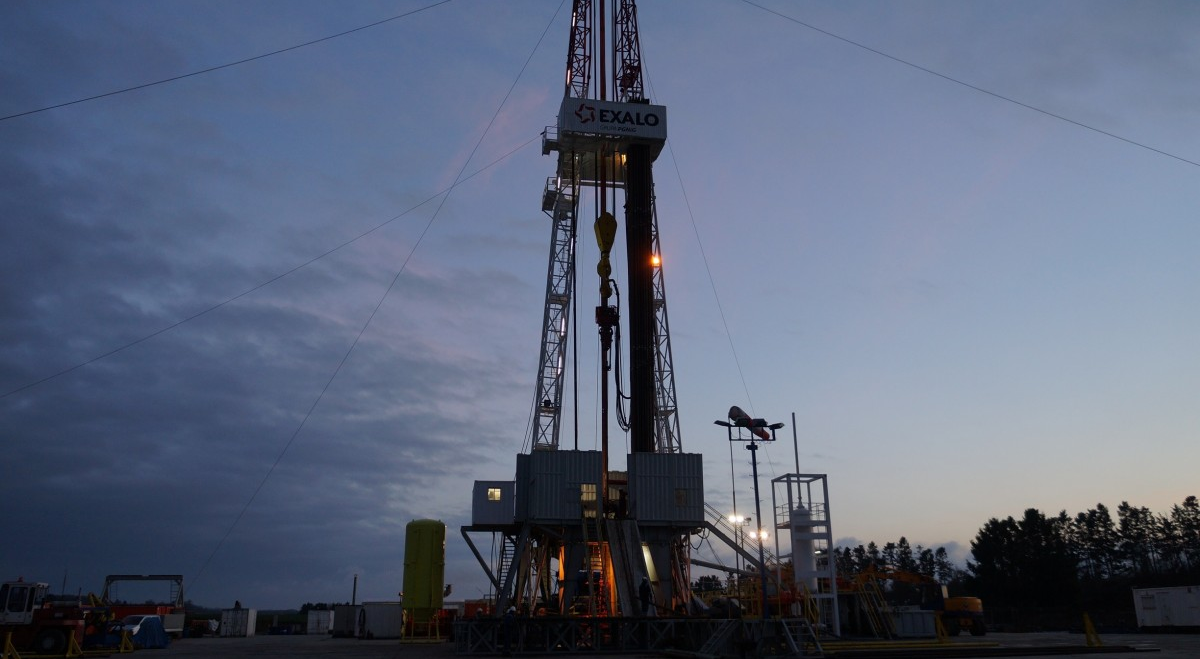
    The company is working with Ensign Energy Services to arrange the transportation and deployment of the Ensign Rig 970, following delays caused by adverse weather conditions and road closures affecting heavy vehicles.

    Georgina confirmed that all civil engineering and site preparation work required for drilling has been completed, with contractors and their equipment having left the site.

    However, the timing of rig mobilisation remains dependent on road access, and the company has not yet confirmed a revised drilling commencement date.

    Hussar Rig Mobilisation Expected to Take Eight to Ten Weeks

    Georgina Energy is reviewing a mobilisation programme with Ensign Energy Services and Westmarket Oil & Gas (WMOG), subject to the reopening of roads suitable for transporting the drilling equipment.

    Under the proposed schedule, reactivation of Ensign Rig 970 at its current Waylering location would take approximately four to five weeks.

    This phase includes recommissioning activities and ordering equipment required before transportation.

    Mobilisation of the accommodation camp from Port Augusta in South Australia would take place concurrently with the rig reactivation work.

    Once the equipment is ready and an accessible route has been confirmed, transportation of the drilling rig to the Hussar site is expected to take approximately three weeks.

    A further one to two weeks would be required to assemble the rig and prepare it for drilling.

    The company estimates that the overall process will take eight to ten weeks from the date Westmarket Oil & Gas formally instructs Ensign to commence mobilisation.

    The timetable remains conditional on road access and completion of the necessary preparations.

    Weather Conditions and Road Closures Delay Drilling Preparations

    Georgina said continuing road closures to heavy vehicles and variable weather conditions have prevented the planned mobilisation of Ensign Rig 970.

    The company is working with its contractors to identify a suitable transportation route that can accommodate the equipment.

    Although construction and preparation work at the Hussar location has been completed, the rig cannot be transported until the relevant roads are accessible.

    Management said personnel and equipment safety will remain a priority when determining the mobilisation arrangements.

    The company has not provided a firm date for the reopening of the affected roads.

    As a result, the eight-to-ten-week mobilisation estimate does not establish a confirmed drilling start date.

    Alternative Transport Routes Under Review

    Georgina and its contractors are assessing alternative routes to the Hussar exploration site.

    Consulting engineers and advisers Aztech Well Construction and Ingenua are assisting with the assessment of road access for Ensign Rig 970.

    Westmarket Oil & Gas is also reviewing a potential alternative route through Leonora, travelling along the Great Central Road before turning north onto the David Carnegie Highway.

    The proposed route would then continue towards the Mangkili turnoff and north along the Eagle Highway.

    The suitability of this route remains under review.

    The company has not confirmed whether the alternative will be adopted or whether additional transport approvals or road works will be required.

    Rig Reactivation and Transport Costs Expected to Increase

    Georgina reported that the revised mobilisation arrangements will result in additional costs compared with earlier estimates.

    The increases relate primarily to rig reactivation and transportation.

    Ensign Rig 970 has remained stacked for longer than initially anticipated, requiring additional reactivation work before deployment.

    Transport contractor ECS has also advised that its costs have increased from the original estimate.

    The company attributed the additional transport expenditure to changes identified in the August and September route survey, including the requirement for additional equipment and a longer transportation route.

    Higher fuel prices have also contributed to the revised cost estimate.

    Georgina said the additional mobilisation costs will be allocated between Ensign and Westmarket Oil & Gas.

    The company did not disclose the total expected increase or specify the amount payable by each party.

    Hussar Site Preparation Work Completed

    Georgina confirmed that all civil engineering and site preparation activities required to facilitate drilling at Hussar have been completed.

    Contractors responsible for these activities have demobilised from the location with their equipment.

    The project is therefore awaiting the mobilisation of the drilling rig and associated facilities before drilling operations can begin.

    The company is continuing to coordinate with Ensign Energy Services and Westmarket Oil & Gas to establish a revised schedule.

    Further announcements are expected as the mobilisation arrangements progress and a new drilling commencement date becomes available.

    Hussar Well Targets Helium, Hydrogen and Natural Gas

    The Hussar prospect is located within Exploration Permit 513 in the Officer Basin of Western Australia.

    Georgina plans to drill the exploration well to a total depth of approximately 3,200 metres.

    The planned depth may be extended depending on the geological formations encountered, indications of gas and the quality of potential reservoir intervals.

    The primary exploration targets are subsalt reservoir formations, including the Townsend Formation and fractured Neoproterozoic basement rocks.

    These formations are being evaluated for their potential to contain helium, hydrogen and natural gas.

    The company is also targeting hydrocarbon gas within the shallower Kanpa and Hussar formations.

    Georgina said these secondary targets have not been adequately tested by previous drilling, although earlier exploration encountered hydrocarbon indications and reservoir intervals with favourable porosity characteristics.

    The planned well is intended to provide further geological and reservoir information to assess the prospect’s resource potential.

    Fractured Basement Reservoirs Form Part of Exploration Strategy

    Georgina’s exploration programme includes fractured basement formations beneath the principal sedimentary sequences.

    The company identified these formations as potential reservoirs based on geological characteristics and comparisons with producing fields elsewhere.

    As an example of fractured basement production, Georgina referred to the Bach Ho field offshore Vietnam.

    The company noted that Bach Ho has produced hydrocarbons from fractured basement reservoirs for more than four decades and reached peak production equivalent to approximately 1.6 billion cubic feet of gas per day.

    However, the performance of an established producing field does not establish that similar production rates or commercially recoverable resources will be present at Hussar.

    The planned exploration well will be required to assess the geological conditions and potential gas accumulations at the Western Australian prospect.

    Independent Report Estimates Prospective Helium, Hydrogen and Gas Resources

    Georgina referred to an Independent Geological Report dated 1 February 2026, prepared by competent person Maki Petkovski.

    The report estimates unrisked net attributable 2U prospective resources at Hussar of 283 billion cubic feet of helium, 315 billion cubic feet of hydrogen and 2.93 trillion cubic feet of hydrocarbon gas.

    The estimates were prepared under the Society of Petroleum Engineers Petroleum Resources Management System framework.

    These figures represent prospective resources rather than discovered reserves.

    Prospective resources relate to quantities that may potentially be recoverable from undiscovered accumulations, subject to exploration success, development feasibility and commercial conditions.

    The estimates are unrisked and therefore do not incorporate the probability of geological discovery or commercial development.

    Drilling and further evaluation will be required to determine whether commercially recoverable accumulations exist.

    Company Estimates Potential In-Situ Resource Value at $152 Billion

    Georgina provided an indicative combined in-situ value of approximately US$152 billion for the prospect’s unrisked net attributable prospective resources.

    The estimate is based on assumed commodity prices of US$450 per thousand cubic feet of helium, US$2.65 per kilogram of hydrogen and US$8 per thousand cubic feet of hydrocarbon gas.

    The company said the valuation uses pricing information associated with the Australian Energy Regulator and the Helium Price Index.

    The figure represents an indicative gross in-situ resource value calculated from prospective volumes and assumed commodity prices.

    It is not a project valuation, net present value, revenue forecast or estimate of recoverable economic value.

    The calculation excludes production, processing, gas separation and transportation costs, together with other expenses required to develop and commercialise any discoveries.

    There is no certainty that the prospective resources will be discovered or that any portion will be commercially recoverable.

    Revised Drilling Date Remains Subject to Mobilisation

    Georgina has not announced a new drilling commencement date for Hussar EP513.

    The company said the timing will depend on the reopening of roads, the suitability of alternative transport routes and the completion of rig reactivation and mobilisation activities.

    The proposed eight-to-ten-week schedule will begin only after Westmarket Oil & Gas issues formal notification to Ensign Energy Services to commence the work.

    Further technical and logistical updates are expected as preparations continue.

    Georgina also intends to provide additional site photographs through its corporate website.

    CEO Comments on Hussar Mobilisation

    Anthony Hamilton, Chief Executive Officer of Georgina Energy, commented on the revised mobilisation arrangements and the company’s exploration objectives.

    “The Company is working with Ensign to facilitate mobilisation as quickly as possible and we anticipate that road closures due to unseasonal weather conditions will be overcome with careful planning and drilling Hussar for its Helium and Hydrogen potential into a full field development remains our priority target. We look forward to making further announcements in due course”.

    The company continues to work with its contractors to establish road access and prepare the drilling equipment for transportation.

    Outlook for the Hussar EP513 Project

    Georgina’s immediate priority is to finalise arrangements for mobilising Ensign Rig 970 to the Hussar exploration site.

    The company has completed the required civil engineering and site preparation work but remains dependent on suitable transport access.

    The revised mobilisation plan allows approximately eight to ten weeks between formal authorisation and readiness to commence drilling, subject to road conditions and completion of the planned activities.

    The exploration programme will target helium, hydrogen and natural gas within subsalt formations and secondary hydrocarbon-bearing intervals.

    The results of drilling will be needed to establish whether the prospect contains recoverable gas accumulations and to inform any subsequent appraisal or development decisions.

    Georgina has indicated that further announcements will follow as the mobilisation schedule and revised drilling date are determined.

    More About Georgina Energy

    Georgina Energy Plc is a London-listed exploration and development company focused on helium, hydrogen and natural gas opportunities in Australia.

    The company’s portfolio includes the Hussar prospect within Exploration Permit 513 in the Officer Basin of Western Australia.

    Hussar is planned as an exploration well targeting subsalt reservoir formations and shallower hydrocarbon-bearing intervals.

    An independent geological report dated February 2026 estimated unrisked net attributable prospective resources of 283 billion cubic feet of helium, 315 billion cubic feet of hydrogen and 2.93 trillion cubic feet of hydrocarbon gas.

    These estimates remain subject to geological uncertainty and do not constitute commercially recoverable reserves.

  • Pri0r1ty Intelligence Launches AI-Powered HR Platform as Pirkx Reaches £42,700 in Monthly Recurring Revenue

    Pri0r1ty Intelligence Launches AI-Powered HR Platform as Pirkx Reaches £42,700 in Monthly Recurring Revenue

    Pri0r1ty Intelligence Group PLC (LSE:PR1) has launched Pri0r1ty People, an artificial intelligence-powered human resources management platform incorporating its recently acquired Pirkx employee wellbeing business, which now serves 9,859 contracted users across 525 companies.

    The AIM-listed company reported that Pirkx, acquired in early September 2026 and now operating as Pri0r1ty Pirkx Limited, generates monthly recurring revenue of £42,700 and is trading close to operational break-even.

    Pri0r1ty expects restructuring and technology changes to reduce Pirkx’s operating expenditure from February 2027, potentially allowing the subsidiary to become operationally cash-flow positive in early 2027, provided existing contracted revenues are maintained or increased.

    The launch of Pri0r1ty People extends the group’s software offering into workforce management, combining employee records, leave administration, performance appraisals, contractor management and workplace benefits within its existing AI platform.

    Pirkx Serves 9,859 Users Across 525 Contracted Companies

    Pri0r1ty reported that Pirkx has 9,859 contracted users across 525 companies, with platform engagement of 75%.

    The business operates a subscription-based employee wellbeing and benefits platform serving small and medium-sized enterprises, workforce communities and membership organisations.

    During September 2026, Pirkx’s organic user base increased by more than 1.5%, despite the absence of sales and marketing activity during the acquisition period.

    The company said its immediate priorities include increasing recurring revenue from existing customers, completing operational restructuring and developing a more established marketing strategy.

    The acquisition provides Pri0r1ty with an existing customer base for the introduction of additional software products.

    Monthly Recurring Revenue Reaches £42,700

    Pirkx currently generates contracted monthly recurring revenue of £42,700 from its existing customer base.

    At the current monthly rate, this represents approximately £512,400 on an annualised basis, assuming contracted revenue remains unchanged.

    Pri0r1ty said the business is operating close to break-even following its acquisition.

    Management has undertaken a restructuring and technology programme intended to reduce operating costs.

    The company expects the measures to result in a significant reduction in expenditure from February 2027.

    On an indicative basis, management believes Pirkx could become operationally cash-flow positive in early 2027 if current contracted revenues are maintained or increased.

    The forecast is conditional and does not represent a confirmed profitability outcome.

    Pri0r1ty did not disclose Pirkx’s current operating expenditure, EBITDA or the expected monetary value of restructuring savings.

    Pirkx Reports More Than £3.1 Million in Member Spending

    Pri0r1ty also provided cumulative activity figures for the Pirkx platform.

    Since its launch, members have spent more than £3.1 million through the platform’s cards, vouchers, cinema offers and online purchasing arrangements.

    The company reported that members have generated more than £187,000 in savings, including £115,000 in cashback.

    Users have also entered more than 18,000 competitions and 9,300 lottery draws through the platform.

    Total recorded logins have exceeded 295,000.

    These figures reflect cumulative member activity rather than revenue earned by Pirkx.

    The company did not disclose the period over which the transactions occurred or the revenue generated directly from member purchases.

    Pri0r1ty People Introduces AI-Powered HR Management

    Alongside the Pirkx operational update, Pri0r1ty announced the launch of Pri0r1ty People, a human resources management module within its existing software platform.

    The new product combines workforce administration with AI-assisted functions and Pirkx employee wellbeing services.

    Pri0r1ty People is designed to provide businesses with a central system for managing employee records, leave requests, performance reviews, contractor costs and workplace documentation.

    The platform uses the group’s existing AI infrastructure to process employee requests, generate administrative documents and provide information based on company policies and workforce records.

    The company intends to offer the product initially to Pirkx’s 525 contracted business customers, followed by a wider rollout to existing Pri0r1ty AI users.

    No separate revenue forecast or customer adoption target was disclosed for the new product.

    AI HR Assistant Supports Employee Requests

    One of the principal features of Pri0r1ty People is an AI-powered HR assistant available to employees.

    The assistant is designed to answer questions about workplace policies, check leave balances and submit time-off requests using natural-language instructions.

    Responses can be personalised according to the employee’s information and the policies of their employer.

    The service is available through WhatsApp Business, email and SMS, allowing employees to access HR functions without relying exclusively on the main software interface.

    The assistant uses the group’s existing AI technology and is integrated with other Pri0r1ty services.

    The company did not provide performance metrics for the assistant or quantify the administrative savings it expects customers to achieve.

    AI-Generated Appraisals and Employee Management Tools

    Pri0r1ty People includes tools for preparing and managing employee performance reviews.

    Managers can describe the areas to be covered in an appraisal, after which the AI system generates a draft template tailored to the employee and their role.

    The platform supports the appraisal process from the initial draft through to employee acknowledgement.

    Other functions include an employee directory containing individual profiles and four levels of role-based access.

    Businesses can link existing Pri0r1ty users to employee records and import workforce information through bulk CSV uploads.

    The company said these features are intended to support organisations managing larger numbers of employees.

    Leave, Contractor and Document Management Integrated Into One Platform

    The new HR module also includes a shared calendar showing employee attendance, leave and working-from-home arrangements.

    Time-off and remote-working requests can be routed automatically to the appropriate manager for approval.

    Contractor management functions include timesheet recording, automatic cost calculations, approval workflows and cost summaries for finance teams and departmental managers.

    Pri0r1ty People can also generate organisational charts from employee reporting structures.

    Document management functions provide storage with access permissions based on user roles.

    A separate HR complaints feature allows workplace concerns to be submitted and tracked, including through anonymous reporting.

    These functions are included within the wider Pri0r1ty People product rather than being presented as separate standalone systems.

    Pirkx Wellbeing and Benefits Integrated Into HR Platform

    Pirkx’s existing employee wellbeing and benefits offering has been incorporated into Pri0r1ty People as a dedicated section.

    The integration allows businesses using the HR platform to access Pirkx services alongside workforce administration tools.

    Pri0r1ty said the combination is intended to expand Pirkx beyond its original employee benefits offering.

    The company believes the integration will create additional opportunities to sell software subscriptions to Pirkx’s existing corporate customers.

    The initial rollout will target the 525 businesses already contracted to Pirkx.

    A wider introduction to Pri0r1ty AI customers is planned, although the company did not provide a specific launch date for that phase.

    Existing Pri0r1ty Customers Gain Access to Additional HR Functions

    Pri0r1ty People operates within the group’s existing technology infrastructure.

    The module shares its AI engine with the Pri0r1ty Advisor agent and uses the same user identity system as aInbox.

    It also incorporates the secure cloud storage infrastructure used by the Knowledge Centre, alongside existing notification and subscription systems.

    According to the company, current Pri0r1ty customers can activate HR functions for their teams without a separate setup process.

    Access is governed by the group’s subscription plans.

    This structure creates a potential route for increasing revenue from existing customers who adopt additional services.

    However, the company did not disclose the pricing of Pri0r1ty People or the expected revenue contribution from cross-selling.

    Restructuring Programme Targets Early 2027 Profitability

    Following the acquisition of Pirkx in September, Pri0r1ty began implementing technology and operational changes.

    The programme is intended to reduce the subsidiary’s cost base while integrating its services into the wider group platform.

    Management expects the resulting expenditure reductions to take effect from February 2027.

    Based on current contracted recurring revenue, the company believes these changes could allow Pirkx to become operationally cash-flow positive in early 2027.

    The forecast assumes that contracted revenues are maintained or increased.

    Pri0r1ty said this potential outcome would be ahead of its internal expectations.

    The company has not disclosed the acquisition consideration, total restructuring costs or the financial contribution expected from Pirkx in the current financial year.

    Group Plans Further Acquisitions of Recurring-Revenue Businesses

    Pri0r1ty also outlined plans to pursue additional acquisitions as part of its growth strategy.

    The company intends to target businesses with established customer relationships and recurring subscription revenue.

    Its proposed approach involves acquiring complementary operations, integrating their services into the Pri0r1ty AI platform, reviewing operating costs and introducing additional products to existing customers.

    Management views the Pirkx acquisition and subsequent launch of Pri0r1ty People as an example of this strategy.

    The group said it is actively evaluating further acquisition opportunities.

    However, no additional transactions, acquisition targets or proposed financial terms were announced.

    Any future acquisitions would depend on the completion of negotiations and other applicable conditions.

    Chief Technology Officer Comments on Pirkx Integration

    Daniel Gee, Chief Technology Officer of Pri0r1ty Intelligence Group, commented on the acquired business and its financial outlook.

    “Pirkx is exactly the kind of business we look for: a loved product, a loyal and growing membership of nearly 10,000 people across 525 companies, and contracted recurring revenue that already covers almost all of its costs. In our first month of ownership we have taken the steps needed to put the business on a path towards profitability in early 2027, and that is before any new revenue.

    “The bigger opportunity is what Pirkx becomes inside Pri0r1ty. With the launch of Pri0r1ty People we are turning a wellbeing and benefits platform into a complete, AI-powered HR system. Every employee gets an AI assistant that answers their questions and handles their requests, every manager gets appraisals, leave and contractor costs in one view, and every business gets Pirkx wellbeing built in. We have 525 contracted companies to introduce it to from day one and a full platform of AI tools behind it. This is a significant step in our strategy of building recurring SaaS revenues and cross-selling across the Group.”

    Outlook for Pri0r1ty People and Pirkx

    Pri0r1ty’s near-term priorities include completing the Pirkx restructuring programme, introducing Pri0r1ty People to existing Pirkx customers and expanding the product’s availability across the group’s wider user base.

    The company expects lower operating expenditure at Pirkx from February 2027 and has identified a potential route to operational cash-flow profitability in early 2027.

    The timing of that outcome will depend on the implementation of cost reductions and the maintenance or growth of contracted revenue.

    Pri0r1ty also intends to increase subscription revenue through the adoption of additional AI-powered software products by existing customers.

    Further acquisitions remain under consideration as the group seeks to expand its customer base and recurring revenue activities.

    The company has not issued a quantified group revenue forecast or financial guidance associated with the launch of Pri0r1ty People.

    More About Pri0r1ty Intelligence Group

    Pri0r1ty Intelligence Group PLC is an AIM-listed technology company developing artificial intelligence-powered business software and growth solutions for small and medium-sized enterprises.

    Its platform includes AI-assisted business tools, communication services, document management and subscription-based software applications.

    The group acquired the Pirkx employee wellbeing and benefits business in September 2026 and subsequently integrated it into its wider technology offering.

    Pri0r1ty People extends the group’s product range into human resources management, combining workforce administration tools with AI-assisted functions and employee benefits.

    Pirkx currently serves 9,859 contracted users across 525 companies and generates £42,700 in monthly recurring revenue.

  • Hunting Cuts FY2026 EBITDA Guidance to $128–133 Million as Middle East Conflict Affects Trading

    Hunting Cuts FY2026 EBITDA Guidance to $128–133 Million as Middle East Conflict Affects Trading

    Hunting PLC (LSE:HTG) has lowered its full-year 2026 EBITDA guidance to between $128 million and $133 million, citing disruption to Middle East operations, slower activity in North America and supply chain delays affecting its advanced manufacturing businesses.

    The London-listed precision engineering group reported year-to-date EBITDA of approximately $89 million, representing a margin of around 12%, as trading conditions varied across its five operating segments.

    Hunting said the continuing conflict in the Middle East has disrupted oil country tubular goods (OCTG) tender activity, affected product deliveries and reduced demand in certain regional markets. The company also reported a decline in drilling activity in Saudi Arabia, affecting its Hunting Titan business.

    Despite these conditions, the group’s Subsea Technologies operations continued to generate profits, while restructuring measures contributed to a return to quarterly profitability in its Europe, Middle East and Africa (EMEA) segment.

    Hunting also reported an improvement in its net borrowing position during the third quarter, with net borrowings declining to approximately $11 million at 30 September 2026 from $19 million at the end of June.

    Full-Year EBITDA Forecast Revised to $128–133 Million

    Hunting now expects EBITDA of between $128 million and $133 million for the financial year ending 31 December 2026.

    The revised outlook reflects changes in trading conditions during the third quarter and a deterioration in near-term demand across several markets during the opening weeks of the fourth quarter.

    Management identified the continuing Middle East conflict as a principal factor affecting the group’s outlook.

    Disruption to shipping routes and regional infrastructure has affected tender activity and product deliveries, while lower drilling activity in Saudi Arabia has reduced demand associated with the Jafurah unconventional gas development.

    Hunting also expects slower fourth-quarter activity in North America, reflecting seasonal conditions, customer budget constraints and caution among operators.

    In addition, third-party supply chain problems have delayed deliveries and order completion within its Electronics and Dearborn businesses.

    The company did not disclose its previous EBITDA guidance in the latest announcement.

    Year-to-Date EBITDA Reaches Approximately $89 Million

    Hunting reported EBITDA of approximately $89 million for the first nine months of 2026, equivalent to an EBITDA margin of around 12%.

    The result reflects contributions from the group’s operating segments and product lines, including Hunting Titan, North America, Subsea Technologies, EMEA and Asia Pacific.

    Performance differed across the portfolio, with continued profitability in Subsea Technologies and improved year-to-date results in Hunting Titan’s North American operations.

    These contributions were partly offset by weaker Middle East activity, delayed orders and slower trading improvements in certain manufacturing businesses.

    The company expects the combined effects of these developments to continue influencing its financial performance during the final quarter.

    Middle East Conflict Disrupts Tender Activity and Deliveries

    Hunting reported that the prolonged conflict in the Middle East has affected trading across several product lines.

    The company cited logistical difficulties, attacks on commercial shipping and disruption to regional infrastructure as factors restricting OCTG and other equipment tender activity.

    Reduced drilling activity in Saudi Arabia has also affected demand for Hunting Titan products associated with the Jafurah unconventional development.

    Management said the deterioration in regional trading conditions had continued into the fourth quarter.

    Hunting expects the effects of these disruptions to remain evident in its full-year results.

    The company indicated that activity could recover following an improvement in regional conditions, although the timing and extent of any recovery remain uncertain.

    Hunting Titan Reports North American Growth Despite Slower Deliveries

    Hunting Titan’s third-quarter performance was marginally below management’s expectations.

    The business experienced slower deliveries to the Middle East, while activity in North America also moderated.

    Hunting expects these conditions to continue through the remainder of 2026.

    Nevertheless, the company anticipates year-on-year growth for Hunting Titan, reflecting increased activity in its domestic North American market during the first nine months and higher international sales.

    Management remains cautious about fourth-quarter demand because of seasonal factors, customer spending constraints and reduced activity among some operators.

    The slowdown in Saudi Arabian drilling activity has also affected Hunting Titan’s regional performance.

    Advanced Manufacturing Recovery Delayed by Supply Chain Issues

    Hunting reported that the anticipated improvement in its Electronics and Dearborn businesses has been slower than expected.

    Both operations form part of the group’s Advanced Manufacturing product group.

    Third-party supply chain constraints have restricted deliveries and delayed the completion of customer orders.

    These delays have affected the timing of revenue and earnings contributions from the businesses.

    The company did not quantify the value of delayed orders or provide a revised timetable for their completion.

    The slower recovery in Advanced Manufacturing was among the factors contributing to Hunting’s revised full-year EBITDA guidance.

    Subsea Technologies Maintains Profitability

    Hunting’s Subsea Technologies operations continued to report profitability during the third quarter.

    The company attributed the performance to ongoing customer demand and operational management across its subsea businesses.

    The division has remained an area of trading stability within the group’s wider portfolio.

    Hunting also reported commercial interest in its Organic Oil Recovery technology.

    During the quarter, the company received orders for pilot testing and sampling activities involving potential applications in South America, the North Sea and the Middle East.

    These orders represent early-stage commercial and technical work rather than confirmed large-scale deployments.

    Hunting did not disclose the financial value of the orders or provide revenue forecasts associated with the technology.

    EMEA Segment Returns to Quarterly Profitability

    Hunting’s EMEA operating segment returned to profitability during the third quarter of 2026.

    The improvement followed restructuring measures, including the closure of the company’s Fordoun operating site in Aberdeen in September.

    The company said the restructuring had begun to generate previously announced cost savings.

    However, continued disruption in the Middle East is expected to affect the segment’s full-year performance.

    Hunting now anticipates that EMEA will report a small EBITDA loss for 2026 despite returning to profitability during the third quarter.

    The group is continuing to review operating costs and organisational arrangements as part of its wider restructuring programme.

    Asia Pacific Performance Affected by Kuwait Tender Delays

    Hunting reported lower year-to-date results in its Asia Pacific operating segment.

    The performance reflects delays to the Kuwait Oil Company tender process and reduced OCTG tender activity across the Middle East.

    The company said market volatility and regional disruption have slowed the award of new contracts.

    Following a small profit in the first half, the Asia Pacific segment is now expected to report approximately break-even EBITDA for the second half of 2026.

    The company continues to monitor tender activity and customer demand across the region.

    Kuwait Oil Company Re-Tender Published in October

    Hunting confirmed that Kuwait Oil Company published its delayed re-tender on 12 October 2026.

    A decision is anticipated before the end of the year.

    Under the expected timetable, product shipments associated with any awarded contracts would begin during the second half of 2027.

    Hunting intends to participate in the tender process and is seeking additional orders based on its existing commercial relationship with Kuwait Oil Company.

    However, the company has not announced any contract award arising from the new tender.

    The timing, value and allocation of potential orders remain subject to the customer’s procurement process.

    Net Borrowings Decline to Approximately $11 Million

    Hunting reported a net borrowing position of approximately $11 million at 30 September 2026, compared with $19 million at 30 June.

    The $8 million improvement reflected operating cash conversion and working capital management during the third quarter.

    The group’s net assets stood at approximately $876 million at the end of September.

    Working capital was approximately $399 million, broadly unchanged from the position reported at the half-year stage.

    Hunting expects its year-end cash and bank borrowings position to be in the range of $40 million to $45 million, on a net borrowing basis.

    This forecast reflects the company’s anticipated financial position following its planned expenditure and capital allocation activities during the final quarter.

    Interim Dividend Scheduled for 30 October

    Hunting confirmed that its 2026 interim dividend of 7.0 US cents per share will be paid on Friday, 30 October 2026.

    The payment is expected to require approximately $10 million in cash.

    The company also provided updated expectations for capital expenditure and shareholder returns.

    Full-year capital expenditure is now forecast at approximately $35 million to $45 million, covering tangible and intangible investment.

    In addition, Hunting expects its share buyback programme to require approximately $42 million during 2026.

    These planned cash outflows form part of the group’s capital allocation programme alongside operating requirements and potential investment opportunities.

    Cost Reduction and Portfolio Restructuring Continue

    Hunting is continuing a restructuring programme intended to simplify its operating structure and reduce costs.

    The measures include combining its EMEA and Asia Pacific operating segments.

    The company is also pursuing the disposal of non-core businesses and reviewing selling, general and administrative expenses.

    The closure of the Fordoun facility in Aberdeen during September formed part of the restructuring activity already completed.

    Hunting said the measures are intended to improve operating efficiency and align resources with its business priorities.

    The company did not disclose additional restructuring costs or quantify the total savings expected from the remaining initiatives.

    Acquisition Opportunities Remain Under Review

    Hunting continues to evaluate potential acquisitions as part of its business development strategy.

    Management said its focus remains on subsea and well completion businesses.

    The company did not identify specific acquisition targets or disclose the potential financial terms of any transactions.

    No new acquisition agreement was announced in the trading update.

    The group is assessing these opportunities alongside its ongoing restructuring programme and capital expenditure commitments.

    CEO Comments on Market Conditions and Revised Guidance

    Jim Johnson, Chief Executive Officer of Hunting, commented on the impact of the Middle East conflict and the group’s revised outlook.

    “Whilst the long-term fundamentals of our end-markets remain robust, which includes ongoing strong trading results within our Subsea-focused businesses, the protracted and deepening nature of the conflict in the Middle East has impacted our overall results in Q3 and into Q4, with a deterioration in the short-term trading outlook seen in recent weeks.”

    Johnson also addressed the effect of regional disruption on tender activity and drilling operations.

    “The Directors believe that there is significant upside within the Middle East once hostilities cease. However, OCTG and other product line tender activity across the region remains challenged at present by logistical issues and continued attacks on shipping and regional infrastructure. Rig activity in Saudi Arabia has declined, reducing activity levels in the Jafurah unconventional development, affecting trading within Hunting Titan.”

    Commenting on the financial outlook, Johnson said:

    “These pressures, together with a slower than planned trading improvement within the Electronics and Dearborn business units due to third-party supply chain issues, have led to us reducing our FY 2026 guidance, with EBITDA now likely to be in the range of $128-$133 million.”

    He added that the company remains focused on its restructuring programme and medium-term strategic objectives.

    Search for New Chief Executive Progresses

    Hunting also provided an update on its chief executive succession process.

    The board’s Nomination Committee continued reviewing internal and external candidates during the third quarter.

    Interviews are planned for the fourth quarter of 2026.

    The selection process is focused on identifying a candidate with relevant strategic, operational and leadership experience.

    The company did not provide a date for the appointment of a new chief executive.

    Hunting said it expects to conclude the process following further evaluation of the candidates.

    Outlook for the Remainder of FY2026

    Hunting expects full-year EBITDA of between $128 million and $133 million, reflecting continued disruption in the Middle East and slower activity in other markets.

    The company anticipates that Hunting Titan will deliver year-on-year growth, although fourth-quarter demand is expected to moderate.

    Subsea Technologies continues to contribute to group profitability, while EMEA is expected to record a small full-year EBITDA loss and Asia Pacific is forecast to achieve approximately break-even EBITDA in the second half.

    The group is also awaiting the outcome of the Kuwait Oil Company re-tender, with a decision expected before year-end.

    Hunting expects year-end net borrowings of approximately $40 million to $45 million, while continuing its planned capital expenditure, dividend payments and share repurchases.

    The company’s next scheduled trading update is Tuesday, 19 January 2027.

    More About Hunting

    Hunting PLC is a London-listed precision engineering company established in 1874.

    The group manufactures equipment and provides services for the global energy industry, with activities spanning oil country tubular goods, perforating systems, subsea technologies and advanced manufacturing.

    Hunting is headquartered in London and maintains a corporate office in Houston, Texas.

    Its operations extend across the United Kingdom, United States, China, India, Indonesia, Mexico, Saudi Arabia, Singapore and the United Arab Emirates.

    The company reports its financial performance through five operating segments: Hunting Titan, North America, Subsea Technologies, EMEA and Asia Pacific.

    Its five product groups are OCTG, Perforating Systems, Subsea, Advanced Manufacturing and Other Manufacturing.

  • Prospex Energy Reports 78% Rise in Q3 Cash Balance to £1.5 Million as Gas and Electricity Revenues Increase

    Prospex Energy Reports 78% Rise in Q3 Cash Balance to £1.5 Million as Gas and Electricity Revenues Increase

    Prospex Energy PLC (LSE:PXEN) reported a 78% increase in its group cash balance to £1.515 million at 30 September 2026, compared with approximately £852,000 at the end of the previous quarter, supported by higher European energy prices and cash receipts from its gas and electricity operations.

    The AIM-listed energy investment company recorded £1.701 million in combined operating revenue receipts from its Selva Malvezzi gas concession in Italy and Tarba Energía operations in Spain during the third quarter, compared with £1.203 million in the preceding quarter.

    Prospex also reported progress across its European portfolio, including continued production at Selva Malvezzi, lower operating costs at El Romeral, testing activities at the Viura gas field and development planning for the Mniszow oil discovery in Poland.

    The company said its cash position provides funding for near-term activities, while it continues to consider asset-level partnerships to support medium-term investment requirements.

    Third-Quarter Cash Receipts Increase to £1.75 Million

    Prospex reported total group cash receipts of £1.750 million for the three months ended 30 September 2026, compared with £1.286 million in the second quarter.

    Receipts included £1.701 million from the group’s share of gross operating revenue and approximately £48,000 from interest and other financing activities.

    Operating revenue receipts increased by approximately 41% from the £1.203 million recorded in the preceding quarter.

    Total group cash outgoings declined to £1.086 million from £1.341 million in the second quarter.

    These included operating expenditure of £778,000, development costs of £140,000, royalties, taxes and licence fees of £111,000, and debt servicing and repayments of £57,000.

    The difference between receipts and outgoings contributed to the increase in the group’s quarter-end cash balance.

    For the first nine months of 2026, Prospex reported total cash receipts of £5.332 million and cash outgoings of £3.859 million.

    The figures are unaudited and relate to cash resources and operating receipts within the group’s direct control.

    Selva Malvezzi Gas Production Continues Under Revised Operating Conditions

    Production from the Podere Maiar-1 (PM-1) well at the Selva Malvezzi concession in Italy continued during the third quarter.

    The well’s average gross daily production rate was reported at 74,955 standard cubic metres (scm), compared with 77,127 scm in the second quarter and 80,687 scm in the first quarter.

    During the second half of September, operator Po Valley Operations Pty Ltd reduced the gas flow rate to approximately 60,000–62,000 scm per day.

    The adjustment followed an increase in formation-water production and was implemented as part of reservoir management procedures intended to protect longer-term gas recovery.

    Water production had increased from approximately 40–45 litres per day to 70–100 litres per day.

    A slickline intervention conducted between 29 and 30 September examined the change in well conditions.

    At the reduced gas flow rate, water production remained stable at approximately 80–90 litres per day, while pressures remained within the normal operating range.

    No sand or silt production was detected, and the depth of the uppermost sediments remained unchanged.

    PM-1 Flow Rate May Increase Following Further Monitoring

    Following the September intervention, the operator planned to maintain production from the C2 reservoir interval at approximately 60,000 scm per day during October.

    The well is connected to two reservoir zones, the upper C1 and lower C2 sands, but currently produces exclusively from the C2 interval.

    The operator continues to monitor water production, reservoir pressures and other performance indicators.

    If conditions remain stable, management intends to consider increasing the gas flow rate to approximately 62,000–65,000 scm per day towards the end of October.

    Further increases may be evaluated following additional monitoring and technical analysis.

    The next scheduled slickline intervention is planned for January 2027, subject to the ongoing assessment of well data.

    Higher Gas Prices Support Selva Malvezzi Revenue

    Prospex reported a weighted average realised gas price of €0.69 per standard cubic metre during the third quarter, compared with €0.48 in the second quarter and €0.43 in the first quarter.

    The increase in realised pricing supported revenue despite lower average production volumes.

    Gross revenue from Selva Malvezzi reached approximately €4.566 million during the quarter.

    Revenue attributable to Prospex’s 37% interest was €1.689 million, compared with €1.255 million in the second quarter and €1.155 million in the first quarter.

    The company said third-quarter revenue reached a record level for the operation.

    At 30 September, the gas price was €0.75 per scm, while indications for October were above €0.80 per scm.

    Prospex also confirmed that a new 12-month gas sales agreement with Hera Trading S.r.l. came into effect on 1 October 2026.

    Revenue attributable to Prospex differs from cash receipts in the group’s unaudited cash-flow statement because of the timing of payments.

    Selva Malvezzi Prepares for 2027 Drilling Programme

    Prospex continued preparations for further drilling at Selva Malvezzi during the quarter.

    Schlumberger Italy delivered a preliminary dataset following processing of the recently completed three-dimensional seismic survey.

    The project team will interpret the information to identify and confirm drilling locations for a planned 2027 campaign.

    The programme is intended to evaluate additional productive wells within the concession.

    Prospex also reported progress in the environmental permitting process.

    Italy’s Ministry of Environment and Energy Security has confirmed the admissibility of the Environmental Impact Assessment for a proposed four-well drilling programme.

    A 60-day public observation period is now underway.

    The timing of drilling activities will depend on the completion of technical planning and the relevant permitting processes.

    El Romeral Generates Positive Cash Contribution

    Prospex reported improved financial performance at the El Romeral gas and electricity operation in Spain during the third quarter.

    The operation is held through Tarba Energía S.L.

    Electricity generation revenue increased, supported by continued production and higher electricity prices.

    As a result, Tarba generated a positive net cash contribution of £105,000 during the quarter.

    The company said Tarba became self-sufficient on a current cash basis during August and September, removing the need for funding support from Prospex during those months.

    Gas production and electricity generation continued throughout the reporting period.

    New Transformer Reduces Romeral Operating Costs

    A replacement transformer was installed and commissioned at El Romeral during the third quarter.

    The equipment had originally been ordered in September 2025.

    Following installation, Tarba returned a rented transformer to its supplier, reducing fixed monthly operating expenditure by approximately €14,000.

    The company said the cost of the new transformer is expected to be funded entirely from Tarba’s internal cash flow, without additional contributions from Prospex.

    Prospex also assessed the operation’s ability to maintain its current electricity generation levels.

    Based on existing well and reservoir performance, the company expects current generation rates to continue until the third quarter of 2027, with the possibility of extending production beyond that period.

    This expectation remains dependent on future operating conditions.

    Viura Gas Field Begins Water Re-Injection Testing

    At the Viura gas field in Spain, operator HEYCO Energy Iberia continued managing production to support cash generation during the third quarter.

    Prospex holds a 7.5% interest in the operation.

    During the period, the operator prepared an interference and water re-injection test using the Viura 1 ST3 well.

    The testing programme is intended to validate the reservoir dynamic model and assess whether the existing well could be used for produced-water disposal.

    Testing began in October, after the end of the reporting period.

    Prospex said the initial results were encouraging, although it did not provide detailed technical findings.

    Establishing a sustainable water injection system could improve reservoir recovery, operating costs and cash generation.

    Further updates are expected as testing progresses.

    Viura Reports Monthly Gas and Condensate Production

    Viura recorded sales gas volumes of approximately 1.832 million normal cubic metres in July, 1.276 million in August and 1.602 million in September.

    Total sales gas volumes for the third quarter were therefore approximately 4.709 million normal cubic metres.

    This compares with 7.9 million normal cubic metres in the second quarter and 10.5 million in the first quarter.

    Condensate production totalled 522 barrels in July, 377 barrels in August and 453 barrels in September.

    Combined third-quarter condensate production was approximately 1,352 barrels, compared with 1,962 barrels in the second quarter.

    Water production totalled 7,820 cubic metres in July, 4,094 cubic metres in August and 6,094 cubic metres in September.

    The operator’s testing programme is intended to assess options for managing produced water and supporting future field performance.

    Mniszow Oil Discovery Development Planning Advances in Poland

    Prospex continued technical work on the Mniszow oil discovery within the Dunajec licence in Poland.

    The company reviewed historical geological and operational information to develop a potential production strategy.

    The proposed approach involves lateral drilling techniques used in other fractured carbonate reservoirs.

    During September, Prospex management visited the licence area and met with local seismic and drilling service providers.

    The company also published an investor presentation outlining the proposed development approach.

    The work is intended to establish a drilling and completion strategy capable of supporting commercial oil production.

    Prospex did not announce a drilling timetable, development budget or production forecast for Mniszow.

    Nine-Month Cash Flow Reflects Operating and Financing Activities

    For the first nine months of 2026, Prospex recorded £3.817 million in operating revenue receipts from assets within its direct control.

    The group also received £1.355 million in net debt financing proceeds during the period, primarily associated with financing completed in the first quarter.

    Interest and other financing receipts totalled £160,000.

    Cash outgoings included £2.686 million in operating expenditure, £441,000 in development costs and £675,000 in royalties, taxes and licence fees.

    Development expenditure during 2026 primarily related to seismic processing at Selva Malvezzi.

    The group also recorded £57,000 in debt servicing and repayments.

    Prospex noted that second-quarter royalties, taxes and licence fees included £177,000 of new permit fees in Poland.

    The company’s interim accounts also reflected one-off costs associated with its convertible loan note financing and management changes earlier in the year.

    CEO Comments on Operations and Funding Strategy

    Tom Reynolds, Chief Executive Officer of Prospex Energy, commented on the group’s third-quarter activities and financial position.

    “I am pleased to provide shareholders with an overview of Q3 2026 activities, including unaudited Group cash-flow figures for the period. During the quarter, we focused on operational delivery at El Romeral, resulting in a cash surplus and advanced detailed development plans at Mniszow in Poland.

    “At Selva Malvezzi, PM-1 delivered record production and revenues during the quarter. The new seismic data is feeding into the 2027 drilling and activity plan, which aims to establish additional productive wells within the concession. In the meantime, the PM1 well will be carefully managed to optimise its continuing contribution.

    “Ending the quarter with a strong cash balance of over £1.5 million provides the Prospex with sufficient cash to progress assets in the near term. Consistent with previous guidance, I expect medium-term capital needs to be met by introducing partnership capital at the asset level where the Company has engaged with a number of interested counterparties. This will allow us to add value to our assets through discovery, de-risking and development, maximising value for existing shareholders.”

    The company indicated that discussions with potential partners are continuing as part of its approach to funding future development activities.

    No binding partnership agreements or financing commitments were announced.

    Outlook for the Remainder of 2026

    Prospex enters the final quarter of 2026 with a group cash balance of £1.515 million and continued production from its Italian and Spanish operations.

    At Selva Malvezzi, the operator is monitoring PM-1 well performance following the September reduction in gas flow rates.

    Further analysis of seismic data will support planning for the proposed 2027 drilling programme, while the environmental assessment process for four additional wells continues.

    At El Romeral, the company expects the installation of the new transformer to reduce operating costs and support Tarba’s cash generation.

    Testing at Viura will continue to assess the potential for water re-injection, while development planning at Mniszow remains focused on establishing a commercial production strategy.

    Prospex expects to fund near-term activities from existing cash resources and intends to pursue asset-level partnership capital for medium-term development requirements.

    More About Prospex Energy

    Prospex Energy PLC is an AIM-listed investment company focused on natural gas, electricity generation and energy development projects in Europe.

    Its portfolio includes interests in the Selva Malvezzi gas concession in Italy, the El Romeral gas and electricity operation and Viura gas field in Spain, and the Mniszow oil discovery within the Dunajec licence in Poland.

    Prospex is classified as an investment entity under IFRS 10. Consequently, its statutory financial statements recognise investments in subsidiaries, joint ventures and underlying assets at fair value rather than consolidating their operating results.

    The group’s third-quarter cash-flow information is unaudited and excludes cash balances held by entities outside Prospex’s direct control, including HEYCO Energy Iberia.

  • Ecora Royalties Reports 32% Rise in Nine-Month Portfolio Contribution to $56.2 Million as Net Debt Declines

    Ecora Royalties Reports 32% Rise in Nine-Month Portfolio Contribution to $56.2 Million as Net Debt Declines

    Ecora Royalties PLC (LSE:ECOR) reported a 32% increase in portfolio contribution to $56.2 million for the nine months ended 30 September 2026, compared with $42.6 million in the corresponding period last year, supported by contributions from its base metals and other royalty interests.

    The critical minerals royalty and streaming company generated a total portfolio contribution of $24.8 million in the third quarter, broadly unchanged from $25.0 million a year earlier but above the $19.0 million recorded in the second quarter.

    Excluding its Kestrel steelmaking coal royalty, third-quarter portfolio contribution increased 17% to $14.6 million, while the nine-month contribution rose 66% to $44.7 million.

    Ecora also reported a reduction in net debt to $71.6 million at 30 September 2026, from $74.9 million at the end of June. The company expects net debt to decline further to approximately $57 million at the end of October, including royalty receivables due during that month.

    Nine-Month Portfolio Contribution Increases 32%

    Ecora’s total portfolio contribution reached $56.2 million during the first nine months of 2026, an increase of $13.6 million from the $42.6 million reported in the same period of 2025.

    Third-quarter contribution was $24.8 million, compared with $25.0 million a year earlier, representing a decline of approximately 1%.

    On a sequential basis, the quarterly contribution increased from $19.0 million in the second quarter.

    The company’s portfolio excluding Kestrel generated $14.6 million during the third quarter, up from $12.5 million in the prior-year period.

    For the first nine months, contribution excluding Kestrel reached $44.7 million, compared with $26.9 million in 2025.

    The results reflect increased contributions from several producing assets, including cobalt, copper and gold interests.

    Base Metals Contribution Rises 17%

    Ecora’s base metals portfolio generated $11.6 million in the third quarter, compared with $9.9 million a year earlier.

    The increase of 17% was supported by contributions from the Voisey’s Bay cobalt stream and the Mimbula copper operation.

    For the first nine months of 2026, base metals contributed $34.1 million, compared with $18.5 million in the corresponding period last year.

    The portfolio includes interests in Voisey’s Bay, Mantos Blancos, Mimbula and Carlota.

    Metal purchase costs under the group’s streaming agreements are deducted when calculating net portfolio contribution.

    Voisey’s Bay Cobalt Contribution Increases to $7.2 Million

    Ecora received 154 tonnes of attributable cobalt from Voisey’s Bay during the third quarter, compared with 182 tonnes in the same period last year.

    Despite the lower volume, net portfolio contribution increased to $7.2 million from $6.0 million.

    The average realised cobalt price rose to $26.20 per pound, compared with $18.13 per pound in the third quarter of 2025.

    The increase in realised pricing supported the higher contribution despite the reduction in attributable metal received.

    Before associated metal purchase costs, Voisey’s Bay generated a portfolio contribution of $8.9 million, compared with $7.4 million a year earlier.

    For the first nine months of 2026, its contribution before metal purchase costs totalled $25.5 million, compared with $12.4 million in the previous year.

    Mantos Blancos Copper Contribution Remains at $2.6 Million

    The Mantos Blancos copper operation generated a portfolio contribution of $2.6 million during the third quarter, unchanged from the corresponding period in 2025.

    For the first nine months of 2026, the asset contributed $7.5 million, compared with $6.4 million a year earlier.

    Operator Capstone Copper Corp. is progressing a pre-feasibility study for the Mantos Blancos Phase II expansion.

    The study is examining increased throughput at the concentrator plant and additional cathode production through the re-leaching of historical tailings.

    Capstone is targeting publication of the study towards the end of 2026.

    The proposed expansion remains subject to the findings of the study and subsequent development decisions.

    Mimbula Copper Contribution Increases as Further Metal Entitlement Is Recorded

    Ecora reported a net portfolio contribution of $1.7 million from Mimbula during the third quarter, compared with $1.1 million a year earlier.

    The asset generated a gross portfolio contribution of $2.4 million before associated metal purchase costs, compared with $1.5 million in the prior-year quarter.

    Ecora also reported a copper entitlement of 250 tonnes for the third quarter of 2026.

    The entitlement is expected to generate a net portfolio contribution of $2.5 million in the fourth quarter.

    For the first nine months of 2026, Mimbula contributed $7.3 million before metal purchase costs, compared with $2.2 million in the corresponding period last year.

    Specialty Metals and Uranium Contribution Declines 16%

    Ecora’s specialty metals and uranium portfolio generated $1.6 million in the third quarter, compared with $1.9 million in the same period of 2025.

    The decline of 16% reflected lower contributions from certain uranium interests.

    For the first nine months of 2026, the portfolio contributed $6.2 million, compared with $5.9 million a year earlier.

    The portfolio includes the McClean Lake uranium interest, Maracás Menchen vanadium royalty and Four Mile uranium interest.

    McClean Lake contributed $0.6 million during the quarter, down from $0.8 million, while Four Mile contributed $0.5 million, compared with $0.6 million.

    Maracás Menchen generated $0.5 million, unchanged year on year.

    Maracás Menchen Operator Secures $60.1 Million US Defense Supply Order

    The Maracás Menchen vanadium operation contributed $0.5 million to Ecora’s portfolio during the third quarter, matching the contribution recorded a year earlier.

    During the period, Largo Resources USA Inc. received a $60.1 million firm fixed-price delivery order from the US Defense Logistics Agency Strategic Materials.

    The order covers the supply of high-purity vanadium pentoxide produced at Maracás Menchen for the US National Defense Stockpile.

    The agreement provides a further commercial development for the operation, which supplies vanadium products outside China and Russia.

    Ecora did not quantify any potential additional royalty contribution arising from the supply order.

    McClean Lake Uranium Operations Resume Following Temporary Disruption

    Ecora reported a $0.6 million portfolio contribution from McClean Lake during the third quarter, compared with $0.8 million in the prior-year period.

    On 14 July, Cameco announced that production at its Cigar Lake mine had restarted following a two-week stoppage.

    The interruption resulted from an expansion joint failure at the sulphuric acid plant at the McClean Lake mill, where ore from Cigar Lake is processed.

    Cameco maintained its full-year 2026 Cigar Lake production guidance of 17.5 million to 18.0 million pounds.

    Ecora did not announce any revision to its expectations for the McClean Lake interest following the restart.

    Phalaborwa Rare Earths Project Advances Feasibility Work

    Ecora also provided an update on the Phalaborwa Rare Earths project, where Rainbow Rare Earths Limited is progressing development studies.

    On 1 July, Rainbow reported that test work and pilot plant operations had enabled it to optimise and simplify the project’s processing flowsheet.

    According to the update, approximately 75% of the flowsheet had progressed to the engineering phase of the definitive feasibility study, with final optimisation of the solvent extraction process continuing.

    On 24 September, Rainbow announced a memorandum of understanding with Neo Performance Materials.

    The agreement covers technical support and design input for the project’s final solvent extraction separation circuit.

    Rainbow intends to publish an updated pre-feasibility study in the fourth quarter of 2026, followed by a definitive feasibility study planned for the first half of 2027.

    These studies represent upcoming development milestones for Ecora’s rare earths royalty portfolio.

    Kestrel Generates $10.2 Million in Third-Quarter Contribution

    Ecora’s Kestrel steelmaking coal royalty generated $10.2 million in portfolio contribution during the third quarter, compared with $12.5 million a year earlier.

    Mining operations remained within the group’s private royalty area throughout the period.

    Saleable production attributable to that area reached 0.9 million tonnes during the quarter.

    For the first nine months of 2026, saleable production from the private royalty area totalled 1.0 million tonnes.

    Full-year guidance remains unchanged at between 1.0 million and 1.2 million tonnes.

    Kestrel contributed $11.5 million during the first nine months of 2026, compared with $15.7 million in the same period last year.

    EVBC Gold Royalty Contribution Doubles

    Ecora reported a third-quarter contribution of $1.4 million from its EVBC gold royalty, compared with $0.7 million in the corresponding period of 2025.

    The contribution therefore doubled year on year.

    For the first nine months of 2026, EVBC contributed $4.4 million, compared with $2.3 million in the previous year.

    Under IFRS 9 accounting requirements, royalties received from EVBC are reflected in the fair value movement of the underlying royalty rather than being recognised as royalty income.

    The company did not provide additional production or pricing details for the operation in its quarterly update.

    Net Debt Declines to $71.6 Million

    Ecora reported net debt of $71.6 million at 30 September 2026, compared with $74.9 million at 30 June.

    The reduction of $3.3 million reflects the group’s financial position at the end of the third quarter.

    The September figure excludes royalty receivables due in October.

    Management expects net debt to decline to approximately $57 million by the end of October, including those receivables.

    The company said this would represent a reduction of approximately 35% since the beginning of 2026.

    Ecora expects further debt reduction during the remainder of the year, assuming it does not undertake additional royalty or streaming acquisitions.

    CEO Highlights Cash Generation and Development Milestones

    Marc Bishop Lafleche, Chief Executive Officer of Ecora, commented on the group’s financial performance and development portfolio.

    “Q3 continued to demonstrate the cash generation potential and value of our producing critical minerals portfolio. Net debt at the end of October is expected to reduce to ~ $57m (inclusive of Q3 royalty receivables due in October) down ~35% year to date. Looking ahead, we are entering a pivotal phase. The next twelve months should feature a number of key milestones across our development portfolio of copper and wider critical minerals royalties, that are expected to derisk the next wave of Ecora’s organic growth.”

    The company expects several development-stage assets to reach further technical and planning milestones over the next 12 months.

    These include the planned Mantos Blancos Phase II pre-feasibility study and the updated pre-feasibility and definitive feasibility studies for Phalaborwa.

    Outlook for the Remainder of 2026

    Ecora enters the final quarter of 2026 with nine-month portfolio contribution of $56.2 million and net debt of $71.6 million at the end of September.

    The company expects further debt reduction, subject to the timing of royalty receipts and the absence of additional royalty or stream acquisitions.

    The Mimbula copper entitlement recorded for the third quarter is expected to contribute $2.5 million in the fourth quarter.

    At Kestrel, full-year saleable production guidance from the group’s private royalty area remains between 1.0 million and 1.2 million tonnes.

    Development activity is also continuing across the portfolio, including studies at Mantos Blancos and Phalaborwa.

    The timing and outcomes of these projects will influence the development of Ecora’s future royalty and streaming interests.

    More About Ecora Royalties

    Ecora Royalties PLC is a mining royalty and streaming company focused on critical minerals, with copper forming a central part of its portfolio.

    The group holds interests in producing and development-stage assets across several commodities, including copper, cobalt, vanadium, uranium, rare earths, gold and steelmaking coal.

    Its business model involves receiving royalties or metal deliveries linked to mining operations, rather than directly operating the underlying mines.

    Ecora’s shares are listed on the London and Toronto Stock Exchanges under ECOR and trade on the US OTCQX market under ECRAF.

    The company reported total portfolio contribution of $56.2 million for the first nine months of 2026, representing an increase of 32% year on year.

  • Elementis Raises FY2026 Adjusted Operating Profit Guidance to $133–135 Million as Nine-Month Revenue Rises 7%

    Elementis Raises FY2026 Adjusted Operating Profit Guidance to $133–135 Million as Nine-Month Revenue Rises 7%

    Elementis plc (LSE:ELM) has raised its full-year adjusted operating profit guidance to between $133 million and $135 million, slightly above its previous forecast and in line with the latest market expectations, following revenue growth during the first nine months of 2026.

    The specialty chemicals group reported revenue of $479 million for the nine months ended 30 September 2026, representing an increase of 7% on an organic constant currency basis. Growth was supported by its Personal Care division, continued demand in Asia and improved trading in the Americas.

    Elementis said its performance reflected progress under the Elevate Elementis strategy introduced in 2025, which focuses on revenue growth, customer relationships and simplifying the group’s operating structure.

    The company expects fourth-quarter revenue to be lower than in the third quarter, partly because some customer orders were fulfilled earlier than anticipated.

    Elementis Raises Full-Year Profit Expectations

    Elementis now expects adjusted operating profit of between $133 million and $135 million for the financial year ending 31 December 2026.

    The revised forecast is slightly above the company’s previous guidance and is consistent with the latest market expectations.

    Management attributed the improvement to trading progress across the business despite mixed conditions in its end markets.

    The group said it remains on track to deliver further progress during the second half of the financial year.

    The updated guidance reflects performance across its Personal Care and Coatings operations, alongside measures implemented through its Elevate Elementis strategy.

    Nine-Month Revenue Increases to $479 Million

    Elementis reported revenue of $479 million for the nine months to 30 September 2026, an organic constant currency increase of 7% compared with the corresponding period last year.

    The increase was supported by growth in Personal Care, continued trading momentum in Asia and an improvement in the Americas.

    The company reported differing market conditions across its regions, with growth in some markets offsetting weaker performance elsewhere.

    Elementis did not provide a separate revenue figure for the third quarter or disclose the contribution of each division to the nine-month total.

    The company said its trading performance continued to reflect progress under its operational and commercial strategy.

    Personal Care Revenue Growth Accelerates Across All Regions

    Elementis reported an acceleration in Personal Care revenue growth across all geographic regions during the third quarter.

    The division benefited from a weaker comparative period in the previous year, alongside further improvement in the Americas.

    Trading was also supported by the timing of customer orders, with some demand brought forward into September.

    The favourable order phasing contributed to the division’s third-quarter performance but may affect the distribution of revenue between the final two quarters of the year.

    Elementis did not disclose a specific revenue growth rate for Personal Care or provide separate regional sales figures.

    Coatings Performance Improves in the Americas

    The Coatings division reported improved performance in the Americas following a weaker first half of the financial year.

    The company’s Energy business, which operates within Coatings, continued to benefit from operational improvements at its St. Louis facility in the United States and favourable demand conditions.

    Elementis also reported continued trading progress in Asia, which helped offset weaker results in Europe, the Middle East and Africa during the quarter.

    The regional differences reflected the mixed market conditions affecting the group’s operations.

    The company did not provide separate third-quarter revenue or profitability figures for Coatings.

    Energy Business Benefits From St. Louis Operational Improvements

    Elementis said its Energy business continued to perform well during the period, supported by further operational improvements at its St. Louis plant.

    The business also benefited from demand conditions in its markets.

    The company did not provide details of the operational changes implemented at the facility or quantify their contribution to revenue and profitability.

    The performance of the Energy business contributed to trading within the wider Coatings division.

    Fourth-Quarter Revenue Expected to Be Lower

    Elementis expects revenue in the fourth quarter of FY2026 to be below the level recorded in the third quarter.

    The company said this reflects its usual seasonal trading pattern, together with the effect of customer orders being fulfilled earlier than anticipated.

    The third quarter benefited from this favourable order timing, particularly within Personal Care.

    Elementis also expects growth in Coatings to moderate during the final quarter because of a stronger comparative period in Asia in the previous year.

    Despite the expected reduction in quarterly revenue, the group maintained its revised full-year adjusted operating profit guidance of $133 million to $135 million.

    Elevate Elementis Strategy Continues to Shape Operations

    Elementis introduced its Elevate Elementis strategy in 2025 with the aim of supporting sustainable growth, improving customer relationships and establishing a simpler operating model.

    The company said the strategy continues to influence its commercial and operational activities.

    Its priorities include developing specialty chemical products, strengthening customer relationships and simplifying the business to improve operating efficiency.

    The group linked its nine-month revenue growth and improved profit expectations to progress under these initiatives.

    Elementis did not provide updated financial targets specifically associated with the strategy in its third-quarter trading statement.

    CEO Comments on Trading Performance

    Luc van Ravenstein, Chief Executive Officer of Elementis, commented on the group’s performance and strategic progress.

    “Our ‘Elevate Elementis’ strategy is progressing well, with revenue up 7%2 for the nine months to September 2026 despite mixed end market conditions. This is being driven by Elementis’ high-quality capabilities in specialty chemicals and a simpler, leaner model that puts customers first. We look forward to sharing more about our innovation that underpins this growth and differentiation at our Innovation Day next week.”

    The company plans to provide further information about its innovation activities at an Innovation Day scheduled for the following week.

    Outlook for the Remainder of FY2026

    Elementis enters the final quarter of FY2026 with nine-month revenue of $479 million and revised adjusted operating profit guidance of $133 million to $135 million.

    The company expects fourth-quarter revenue to be lower than in the preceding quarter, reflecting normal seasonality and the earlier fulfilment of certain customer orders.

    Personal Care has reported growth across all regions, while Coatings has benefited from improvements in the Americas and continued activity in Asia.

    The group also expects Coatings growth to moderate in the final quarter because of the prior-year comparison in Asia.

    Management remains focused on implementing its Elevate Elementis strategy and maintaining progress across the business.

    The next scheduled corporate event highlighted in the announcement is the company’s Innovation Day, where it intends to provide further information about its product development activities.

    More About Elementis

    Elementis plc is a London-listed specialty chemicals company operating through its Personal Care and Coatings businesses.

    The group develops and supplies specialty chemical products for customers across a range of industrial and consumer markets.

    Its operations include manufacturing facilities and commercial activities in the Americas, Asia and Europe, the Middle East and Africa.

    Elementis introduced its Elevate Elementis strategy in 2025 to support growth, strengthen customer relationships and simplify its operating structure.

    For FY2026, the company expects adjusted operating profit of between $133 million and $135 million, following organic constant currency revenue growth of 7% during the first nine months of the year.