Author: Fiona Craig

  • Mkango Magnetic Materials Reports Up to $2.06 Billion NPV for Proposed HyProMag USA Expansion

    Mkango Magnetic Materials Reports Up to $2.06 Billion NPV for Proposed HyProMag USA Expansion

    Mkango Magnetic Materials Ltd. (LSE:MKA) announced on Tuesday, 27 October 2026, that an independent pre-feasibility study (PFS) for the proposed expansion of HyProMag USA’s rare earth magnet manufacturing operations estimates an incremental post-tax net present value (NPV) of between US$1.85 billion and US$2.06 billion.

    The study, completed by PegasusTSI Inc. and BBA USA Inc., evaluates the development of three additional U.S. production facilities and a centralised manufacturing and finishing hub, alongside the existing planned facility in Northlake, Texas.

    The proposed expansion could increase HyProMag USA’s annual saleable material production capacity to approximately 6,000 metric tons by 2034, including 4,192 metric tons of finished magnets. The initial Northlake facility remains in detailed engineering, with Phase 1 commissioning expected in mid-2028.

    Pre-Feasibility Study Estimates 31% to 36% Internal Rate of Return

    The independent study examined two potential development scenarios for the three additional manufacturing facilities, excluding the Northlake project.

    Case 1 considers a production system using recycled rare earth magnet feedstock, while Case 2 incorporates both recycled materials and primary neodymium iron boron (NdFeB) alloy feedstock.

    Under Case 1, the PFS estimates a post-tax NPV of US$2.06 billion, an internal rate of return (IRR) of 36% and capital expenditure of approximately US$623 million. The estimated payback period is 2.3 years.

    Case 2 produces an estimated post-tax NPV of US$1.85 billion, an IRR of 31% and capital expenditure of approximately US$656 million, with a projected payback period of three years.

    The profitability index, calculated as post-tax NPV divided by capital cost, ranges from approximately 2.8 times to 3.3 times across the two scenarios.

    These estimates are based on forecast product prices and Class 3 AACE capital cost estimates. They relate exclusively to the proposed expansion facilities and do not include the value of the Northlake Texas project.

    The findings represent preliminary economic assessments of potential future developments rather than financial results from operating facilities.

    Combined U.S. Platform Valuation Estimated at Up to $2.8 Billion

    Including the proposed Northlake facility, the estimated combined post-tax NPV of HyProMag USA’s planned manufacturing platform ranges from US$2.6 billion to US$2.8 billion.

    The Northlake project has an updated estimated post-tax NPV of approximately US$723 million, compared with US$797 million announced on 22 June 2026.

    Mkango attributed the reduction to a revised construction timetable, higher capital expenditure and updated operating cost assumptions.

    Estimated capital expenditure for Northlake has increased to approximately US$167 million, reflecting its phased construction approach and the finalisation of equipment orders.

    The project is currently undergoing detailed engineering, with initial commissioning scheduled for mid-2028.

    Proposed Expansion Targets 6,000 Metric Tons of Annual Production

    The PFS outlines a phased expansion involving three additional production plants in South Carolina, Nevada and a second location in Texas.

    Together with the Northlake facility, the proposed manufacturing platform targets approximately 6,000 metric tons of saleable material annually by 2034.

    Projected annual output comprises approximately 4,192 metric tons of NdFeB magnets, 1,305 metric tons of magnetic alloy powder and 503 metric tons of other saleable materials.

    The projected magnet production capacity represents a fourfold increase from the approximately 1,048 metric tons per year planned at Northlake.

    The three additional plants would contribute an estimated 4,474 metric tons of annual saleable material production beyond the Northlake facility.

    The expansion remains subject to further development work, including progression to a feasibility study.

    Manufacturing Costs and Product Pricing Assumptions

    The PFS estimates all-in sustaining costs for the first expansion plant in 2030 of approximately US$37.40 per kilogram under Case 1 and US$41.60 per kilogram under Case 2.

    These estimates include downstream processing and finishing costs, including plating and epoxy coating.

    Based on forecast market prices and the proposed product mix, the study assumes a weighted average realised selling price of approximately US$100.50 per kilogram in 2030.

    The study also considers increasing the proportion of higher-grade magnet products from approximately 10% to 20% of total magnet output.

    This would involve the use of grain boundary diffusion technology, which enables the manufacture of magnet grades designed for applications including medical equipment, industrial automation, robotics, energy infrastructure and advanced manufacturing.

    The projected costs, selling prices and product mix remain assumptions used in the PFS economic modelling.

    Central Texas Hub to Support Manufacturing and Finishing

    The proposed expansion includes a Central Texas Hub within the second Texas production facility.

    The hub would provide shared manufacturing and finishing services for the three additional plants, including alloy processing, machining, plating, coating, quality assurance and product qualification.

    Planned processing capabilities include vacuum induction melting, strip casting and grain boundary diffusion.

    Under the proposed operating structure, the regional facilities would process feedstock and manufacture unfinished sintered NdFeB magnet blocks.

    These products would subsequently be transferred to the Central Texas Hub for additional processing and finishing.

    The hub could also provide manufacturing and finishing services to third parties, creating potential additional revenue opportunities beyond HyProMag USA’s own magnet production.

    Recycling Technology and Feedstock Supply

    The proposed facilities would use Hydrogen Processing of Magnet Scrap (HPMS) technology to recover rare earth magnetic materials from end-of-life products and manufacturing waste.

    The process is designed to recover magnet-grade materials without chemical processing.

    According to HyProMag USA, its recycling technology uses 88% less energy and produces 85% fewer carbon emissions than conventional processing methods.

    The company also referenced a previously completed carbon footprint assessment for the Northlake facility indicating approximately 2.35 kilograms of carbon dioxide equivalent per kilogram of sintered NdFeB block product.

    The PFS considers combining recycled feedstock with primary alloy materials to provide additional sourcing options.

    HyProMag USA may also gain future access to primary feedstock from Mkango under certain existing supply rights.

    The proposed manufacturing configuration includes the recovery and reprocessing of machining residues and other production by-products.

    Commercial Qualification and Employment Plans

    HyProMag USA is undertaking product testing and customer validation activities with potential U.S. offtake customers.

    The company expects to draw on technical and commercial qualification work already underway within the wider HyProMag Group in the United Kingdom and Germany.

    The proposed U.S. expansion is expected to create approximately 300 jobs across Texas, South Carolina and Nevada, in addition to around 100 positions associated with the Northlake facility.

    The company has identified potential applications for its magnet products in electric vehicles, robotics, advanced electronics, energy infrastructure and defence systems.

    The expansion strategy remains under review, with a feasibility study expected to follow at an appropriate stage.

    Management Comments on Expansion Plans

    Will Dawes, chief executive officer of Mkango, commented on the study’s findings and the potential relationship between the company’s existing rare earth operations and HyProMag USA:

    “The Study indicates the scalability of the HyProMag business model and provides a framework for disciplined growth in the United States using HyProMag USA’s first plant in Northlake. Together with ongoing development activities in the United Kingdom and Germany, it strengthens the foundation for establishing a significant domestic rare earth magnet manufacturing capability for HyProMag. It also highlights the significant potential synergies between HyProMag USA and Mkango, including increased security of feedstock supply and enhanced supply chains into USA markets, respectively.”

    Julian Treger, chief executive officer of CoTec, also commented:

    “This Pre-Feasibility Study confirms the opportunity to establish a significant domestic rare earth magnet manufacturing platform in the United States. The Study demonstrates robust economics and a pathway to producing higher-value NdFeB magnet products for strategically important sectors including advanced manufacturing, energy, defense and AI-driven technologies. Importantly, the platform is designed with the flexibility to utilize primary alloy feedstock alongside recycled materials, providing greater supply chain resilience and supporting long-term operational competitiveness. The results highlight the platform’s potential to create substantial long-term value while strengthening the U.S. rare earth magnet supply chain.”

    The companies indicated that further technical, commercial and development work will be required before the proposed expansion advances.

    HyProMag USA Ownership Structure

    HyProMag USA is a joint venture owned equally by CoTec Holdings Corp. (TSXV: CTH; OTCQX: CTHCF) and HyProMag Limited.

    HyProMag Limited is wholly owned by Maginito Limited, in which Mkango holds a 79.4% interest and CoTec owns the remaining 20.6%.

    Through this structure, Mkango participates in the development of HyProMag USA’s rare earth magnet recycling and manufacturing operations.

    The joint venture is pursuing a phased manufacturing strategy, beginning with the Northlake facility and potentially extending to three additional U.S. plants.

    More About Mkango Magnetic Materials

    Mkango Magnetic Materials Ltd. (LSE:MKA) is a rare earth materials company with interests in recycling, magnet manufacturing and rare earth resource development.

    Through Maginito, the company participates in HyProMag’s magnet recycling and manufacturing operations in the United Kingdom, Germany and the United States.

    Mkango also owns the Songwe Hill rare earth project in Malawi and the proposed Pulawy rare earth separation plant in Poland.

    The company has entered into a proposed business combination involving Mkango Rare Earths Limited and Crown PropTech Acquisitions, intended to list the Songwe Hill and Pulawy projects on Nasdaq.

    The HyProMag USA pre-feasibility study provides preliminary economic estimates for a potential expansion of U.S. rare earth magnet manufacturing capacity, with further development and feasibility work required before implementation.
  • IG Design Group Reports 12% First-Half Revenue Growth to £109 Million, Maintains FY2027 Outlook

    IG Design Group Reports 12% First-Half Revenue Growth to £109 Million, Maintains FY2027 Outlook

    IG Design Group plc (LSE:IGR) reported a 12% increase in first-half revenue to approximately £109 million for the six months ended 30 September 2026, supported by organic growth, contributions from its Glenart acquisition and additional customer contracts.

    The celebration and creative products manufacturer also reported an increase in adjusted operating profit to approximately £5.7 million, compared with £4.2 million in the corresponding period last year.

    The company reaffirmed its expectations for the financial year ending 2027, with the board anticipating results in line with market consensus.

    First-Half Revenue Rises 12%

    IG Design Group expects to report revenue of approximately £109 million for the first half of FY2027, representing an increase of around 12% compared with the previous year.

    Organic revenue growth was approximately 8%, excluding the effects of the Glenart acquisition and foreign exchange translation.

    The company attributed the increase in revenue partly to additional customer tenders secured during the period, alongside the implementation of its strategic priorities.

    The reported figures are preliminary and remain subject to confirmation when the group publishes its unaudited interim financial results.

    Adjusted Operating Profit Increases to £5.7 Million

    Adjusted operating profit for the six-month period increased to approximately £5.7 million, compared with £4.2 million a year earlier.

    This represents an increase of approximately 36% year on year.

    Based on the preliminary revenue and adjusted operating profit figures, the group’s first-half adjusted operating margin was approximately 5.2%, compared with around 4.3% in the corresponding period last year.

    IG Design Group attributed the improvement in trading performance to its commercial activities and the execution of its strategic priorities, including securing incremental customer business.

    The company has not yet provided a detailed breakdown of profitability across its operating activities for the period.

    Glenart Acquisition Performs in Line With Expectations

    IG Design Group confirmed that Glenart, which was acquired before the reporting period ended, continued to trade in line with management expectations.

    The acquisition contributed to reported revenue growth during the first half, although the company did not disclose the specific revenue or profit contribution from Glenart.

    Excluding the acquisition and foreign exchange translation effects, organic revenue increased approximately 8%.

    The board indicated that Glenart’s performance since acquisition has remained consistent with its original expectations.

    Net Cash Position of £1.5 Million at September-End

    IG Design Group reported a net cash balance of approximately £1.5 million as of 30 September 2026.

    The company described cash generation during the first half as robust, with underlying cash outflow broadly consistent with the corresponding period in the previous financial year.

    The trading update did not provide detailed cash flow figures or a breakdown of working capital movements.

    Further information on the group’s financial position is expected to be included in its interim results.

    FY2027 Revenue and Margin Expectations Maintained

    IG Design Group reaffirmed its full-year outlook, with the board expecting FY2027 financial results to align with current market expectations.

    The company identified market consensus forecasts of £222 million in revenue and an adjusted operating margin of 4.8%.

    Management maintained this outlook following the first-half trading performance, while acknowledging continued uncertainty in the wider macroeconomic environment.

    The group has not announced any revisions to its full-year guidance.

    Management Reviewing Medium-Term Growth Strategy

    Under its new leadership team, IG Design Group is reviewing and refining its strategic priorities and medium-term growth plans.

    The company said work on these initiatives is progressing and that a comprehensive update will accompany the publication of its interim financial results.

    The trading statement did not provide further details of potential changes to the group’s operating strategy or specific medium-term financial targets.

    Management continues to focus on implementing the group’s existing commercial priorities while developing its plans for future financial periods.

    Interim Results to Provide Further Financial Detail

    IG Design Group’s forthcoming unaudited interim results will provide additional information on its financial performance for the six months ended 30 September 2026.

    The results are also expected to include an update on the company’s strategic priorities and medium-term growth plans.

    For the first half, the group expects revenue of approximately £109 million, adjusted operating profit of £5.7 million and a closing net cash balance of £1.5 million.

    Its FY2027 expectations remain aligned with market consensus of £222 million in revenue and a 4.8% adjusted operating margin.

    More About IG Design Group

    IG Design Group plc (LSE:IGR) designs and manufactures products across celebration and creative categories.

    The group’s operations include product design, innovation and manufacturing, with its commercial activities supported by customer contracts and an expanded business portfolio following the Glenart acquisition.

    For the first half of FY2027, the company reported approximately 12% revenue growth, including 8% organic growth, alongside an increase in adjusted operating profit.

    IG Design Group continues to develop its medium-term strategic plans under its new leadership team while maintaining its existing financial expectations for FY2027.

  • LPA Group Reports 30% Revenue Growth to £28.1 Million in FY2026, Maintains FY2027 Guidance

    LPA Group Reports 30% Revenue Growth to £28.1 Million in FY2026, Maintains FY2027 Guidance

    LPA Group plc (LSE:LPA) reported a 30% increase in revenue to £28.1 million for the financial year ended 30 September 2026, with adjusted earnings expected to meet its recently upgraded guidance.

    The engineering company, which designs and manufactures electronic and electro-mechanical components and systems, also reported annual order intake of £20.7 million and a closing order book of £25.1 million.

    LPA confirmed that its financial guidance for FY2027 remains unchanged.

    FY2026 Revenue Increases 30%

    LPA Group reported revenue of £28.1 million for FY2026, representing a 30% increase compared with the previous financial year.

    The company expects adjusted earnings for the period to be in line with its recently increased guidance, although the trading update did not provide a specific adjusted earnings figure.

    Management also confirmed that revenue and margins for the year exceeded the company’s original expectations.

    The reported figures reflect the group’s trading performance for the 12 months ended 30 September 2026.

    Order Intake Reaches £20.7 Million

    LPA recorded £20.7 million in new orders during FY2026, ending the financial year with a total order book valued at £25.1 million.

    The order book represents contracted business held by the company at the end of September.

    Management also reported a pipeline of prospective business opportunities entering FY2027, although the update did not quantify the value of those opportunities.

    The company continues to pursue geographic expansion and entry into additional market segments using its existing product portfolio.

    Exceptional Income to Benefit Reported Profit

    LPA confirmed that reported profit before tax for FY2026 will include a benefit from net exceptional income.

    The exceptional income relates to an accelerated payment under an existing contract following changes to customer requirements.

    The company had previously disclosed the payment and reiterated its expected impact on reported profitability in the latest trading update.

    The announcement did not specify the value of the exceptional income or provide a forecast for reported profit before tax.

    Adjusted earnings are expected to remain consistent with the company’s recently upgraded guidance.

    FY2027 Financial Guidance Maintained

    LPA Group reaffirmed its existing guidance for FY2027 without announcing any changes to its financial expectations.

    The company continues to implement its group-wide One LPA transformation programme, which forms part of its operational and strategic development plans.

    Management identified geographical expansion and increased participation in new market segments as elements of its strategy.

    LPA also acknowledged continuing inflationary pressures and macroeconomic uncertainty as factors affecting the wider operating environment.

    The company did not provide additional financial targets or revised forecasts for FY2027 in the trading statement.

    Chief Executive Comments on Performance and Strategy

    Philo Daniel-Tran, chief executive officer of LPA Group, commented on the company’s financial performance and strategic priorities:

    “I am delighted that the Group concluded the FY26 year exceeding original expectations for both revenue and margins. Looking ahead we enter the new financial year with a healthy pipeline of opportunities and remain on track in delivering our strategic Group wide ‘One LPA’ transformation. While inflationary pressures and macroeconomic uncertainties persist, the strength of our balance sheet combined with our strategy of geographical expansion and penetration into new market segments with our existing product portfolio, gives us confidence that the Group is well positioned to capture future opportunities to deliver sustainable long-term growth for all stakeholders.”

    The company indicated that its One LPA programme remains on schedule and that its existing strategy will continue into the new financial year.

    More About LPA Group

    LPA Group plc (LSE:LPA) is an engineering company specialising in the design and manufacture of electronic and electro-mechanical components and systems.

    The company is pursuing a group-wide transformation programme under its One LPA strategy, alongside geographic expansion and the development of additional markets for its existing products.

    For FY2026, LPA reported revenue of £28.1 million, order intake of £20.7 million and a closing order book of £25.1 million.

    Adjusted earnings are expected to meet the company’s recently increased guidance, while reported profit before tax will include net exceptional income associated with an accelerated contractual payment.

    Financial guidance for FY2027 remains unchanged.

  • RWS Holdings Expects FY2026 Revenue of £700 Million and 9% Profit Growth as Acolad Acquisition Nears Completion

    RWS Holdings Expects FY2026 Revenue of £700 Million and 9% Profit Growth as Acolad Acquisition Nears Completion

    RWS Holdings plc (LSE:RWS) reported a return to organic revenue growth for the financial year ended 30 September 2026, with adjusted profit before tax expected to increase approximately 9% year on year. The language technology and AI solutions group also confirmed progress across its three operating segments and expects to complete its acquisition of Acolad within the next two weeks.

    In its unaudited full-year trading update, RWS said reported revenue is expected to reach approximately £700 million, representing a 2% increase from the previous year. Organic constant currency revenue growth was approximately 3%, compared with a 0.7% decline in FY2025.

    The company expects adjusted profit before tax to meet market expectations, with its adjusted profit margin increasing to approximately 9.4% from 8.8% in the preceding financial year.

    Revenue Growth and Profitability in FY2026

    RWS expects reported revenue of approximately £700 million for FY2026, following a 4% revenue decline in FY2025.

    Organic constant currency revenue increased approximately 3% over the year, compared with a 0.7% contraction in the previous financial period.

    Adjusted profit before tax is expected to rise approximately 9% year on year, including the impact of a £1 million loss associated with Obviously Group during the period.

    The adjusted profit before tax margin is forecast at approximately 9.4%, an increase of 0.6 percentage points from the 8.8% reported for FY2025.

    RWS also reported cash conversion ahead of its expectations. Net debt stood at approximately £38 million at 30 September 2026, compared with £32.5 million at 31 March 2026, following an initial £16.5 million payment for the acquisition of Obviously Group.

    The figures remain unaudited ahead of the publication of the company’s full-year financial results in December.

    Generate Segment Records Double-Digit Organic Growth

    RWS reported double-digit organic constant currency revenue growth in its Generate division during FY2026.

    The company attributed the increase primarily to its TrainAI business, which recorded higher activity during the first half of the financial year.

    According to RWS, performance benefited from an expanding customer base and continued demand from developers of frontier AI models.

    Generate was one of two operating segments to report organic revenue growth during the financial year, alongside Protect.

    Transform Revenue Declines as AI Translation Products Advance

    The Transform division recorded a mid-single-digit decline in organic constant currency revenue during FY2026.

    RWS said its services business maintained activity across Europe, the Middle East and Africa, Asia-Pacific and global technology customers. The group also rationalised parts of its client portfolio during the period.

    The company launched Language Weaver Pro, developed in collaboration with Cohere, in March 2026. RWS reported initial revenue contributions from the product during the second half of the financial year.

    A next-generation translation management platform is scheduled for launch in November 2026 as part of the company’s technology development programme.

    In September, RWS was named a Leader in The Forrester Wave: Localization Services, Q3 2026. According to the company, the evaluation recognised its capabilities in hyperlocalisation, AI-readiness services and multimodal localisation.

    The Transform division remains a focus of RWS’s transition towards AI-based translation and language technology services.

    Protect Segment Grows Following Obviously Group Acquisition

    RWS reported mid-single-digit organic constant currency revenue growth in its Protect division.

    The company attributed the increase to new customer contracts and an expanded product portfolio.

    During the financial year, RWS completed the integration of Obviously Group, extending its activities into brand protection and adding an intellectual property management platform to the division.

    The group also invested in personnel and technology within Protect to support its planned expansion.

    The acquisition contributed a £1 million loss during FY2026, which was included in the group’s adjusted profit before tax expectations.

    Acolad Acquisition Expected to Complete Within Two Weeks

    RWS confirmed that it has received the necessary regulatory clearance for its proposed acquisition of Acogroup, the parent company of Acolad.

    Approvals have been obtained from the French Ministry for the Economy, Finance and Industrial, Energy and Digital Sovereignty, together with the relevant French Works Councils.

    The company expects to announce completion of the transaction within the next two weeks.

    According to RWS, the acquisition is intended to expand its presence in Europe, increase its enterprise customer base and provide additional opportunities to offer services across its Generate, Transform and Protect divisions.

    The transaction forms part of the group’s go-to-market strategy announced in December 2025.

    Strategic Programme Focuses on Sales, Technology and Efficiency

    RWS reported progress across the three strategic priorities established in December 2025: go-to-market development, technology and innovation, and operational simplification.

    Within its commercial operations, the group reported new customer wins across several end markets and continued investment in sales capabilities. The proposed acquisition of Acolad is also intended to expand its European operations and cross-selling opportunities.

    Technology initiatives during FY2026 included the launch of Language Weaver Pro and the addition of Obviously Group’s intellectual property management platform. A further translation management product launch is planned for November.

    RWS also reported changes to internal processes, delivery operations and automated workflows. Management expects these initiatives to improve productivity measures across the group.

    The company said all three operating segments delivered revenue in line with its internal expectations for the year.

    CEO Comments on FY2026 Performance and Outlook

    Ben Faes, chief executive officer of RWS, commented on the group’s financial performance and operational developments:

    “I am pleased with the progress that the Group has made in FY26. We returned to growth, grew profit and operating margin, and generated strong cash.

    “The Generate and Protect segments are driving profitable growth. In Transform, we are moving at pace to AI-led technology. Language Weaver Pro is in market and our next generation translation management platform launches next month.

    “We enter FY27 in a stronger position. The acquisition of Acolad is expected to complete shortly, adding scale in Europe and a larger enterprise client base for all three segments. Our investment in sales capability is intended to support improved organic growth in FY27, including in Transform technology revenue.

    “AI is reshaping our industry and RWS is leading that change. Our vision is clear: to be the cultural intelligence layer for enterprise AI. I would like to thank the whole RWS team for their commitment, energy and focus during the year.”

    The company expects its investment in sales capabilities to support organic revenue growth during FY2027, including revenue generated by technology products within Transform.

    Board Changes and Full-Year Results Date

    RWS confirmed that Patrick De Smedt joined the board as chair on 8 October 2026, following the announcement of his appointment on 17 September.

    He succeeds Andrew Brode, who served as interim chairman for the preceding nine months.

    The group is scheduled to publish its full-year financial results for the year ended 30 September 2026 on 15 December 2026.

    Those results will provide the company’s final financial figures following the unaudited trading update.

    More About RWS Holdings

    RWS Holdings plc (LSE:RWS) provides language technology, AI-related services and intellectual property solutions to enterprise customers.

    The group operates through three segments: Generate, Transform and Protect. Its activities include AI training data services, translation and localisation technology, and intellectual property management.

    During FY2026, the company expanded its product portfolio through the launch of Language Weaver Pro and the integration of Obviously Group. It is also progressing the acquisition of Acolad, which is expected to extend its European operations.

    RWS expects to report approximately £700 million in annual revenue and a 9% increase in adjusted profit before tax for FY2026, subject to confirmation in its full-year results on 15 December 2026.

  • Central Asia Metals Completes Cygnus Metals Acquisition, Issues 78.5 Million Shares and Secures TSX Listing

    Central Asia Metals Completes Cygnus Metals Acquisition, Issues 78.5 Million Shares and Secures TSX Listing

    Central Asia Metals PLC (LSE:CAML) announced on Tuesday, 27 October 2026, that it has completed its acquisition of Cygnus Metals Limited following the implementation of a scheme of arrangement. The transaction brings Cygnus and its assets, including the Chibougamau copper-gold project, into the Central Asia Metals group.

    The company also confirmed the listing of its ordinary shares on the Toronto Stock Exchange (TSX), the issuance of approximately 78.5 million new shares as acquisition consideration, and the appointment of Ernest Mast as an independent non-executive director.

    Acquisition Completion and Share Issuance

    Following the scheme becoming effective, Cygnus Metals has become a wholly owned subsidiary of Central Asia Metals.

    Under the transaction terms, Cygnus shareholders were entitled to receive 0.06 new CAML shares for each Cygnus share held on the scheme record date, subject to arrangements for participants in the Share Sale Facility.

    Central Asia Metals has allotted 78,474,252 new ordinary shares, each with a nominal value of US$0.01, as consideration for the acquisition. The allotment is conditional only upon admission of the shares to trading on AIM.

    Admission and commencement of dealings in the new shares are expected at 08:00 GMT on 27 October 2026. Once admitted, the shares will carry the same rights as existing ordinary shares, including dividend entitlements.

    Following admission, Central Asia Metals will have 256,378,533 ordinary shares in issue, including 193,325 shares held in treasury. The total number of voting rights will be 256,185,208.

    Shareholders may use the voting rights figure when calculating notification obligations under the Financial Conduct Authority’s Disclosure Guidance and Transparency Rules.

    Toronto Stock Exchange Listing

    Central Asia Metals confirmed that its ordinary shares have been listed on the Toronto Stock Exchange, with trading scheduled to begin at 09:30 Eastern time on 27 October 2026.

    The TSX listing follows the completion of the Cygnus acquisition, which adds the Chibougamau copper-gold project to the group’s asset portfolio.

    Replacement Share Options

    As part of the acquisition arrangements, Central Asia Metals has granted replacement options over 649,913 ordinary shares to holders of Cygnus options outstanding at the scheme record date.

    The new options replace corresponding Cygnus options cancelled upon implementation of the transaction. Each replacement option provides the right to acquire one Central Asia Metals ordinary share under equivalent terms established in the relevant replacement agreements.

    The options comprise six tranches with exercise prices ranging from £0.49 to £2.89 per share and expiry dates between May 2027 and September 2029.

    The largest tranche covers 392,470 ordinary shares at an exercise price of £0.49, expiring on 19 April 2029.

    The remaining tranches comprise 61,480 options exercisable at £2.89 until 12 May 2027; 6,587 at £2.69 until 13 June 2027; 109,782 at £2.01 until 19 August 2027; 71,360 at £0.98 until 12 May 2028; and 8,234 at £0.51 until 16 September 2029.

    Ernest Mast Joins Board as Independent Non-Executive Director

    Central Asia Metals has appointed Ernest Mast to its board as an independent non-executive director, effective 27 October 2026.

    Mast previously served as a non-executive director and managing director of Cygnus Metals. He was also president and chief executive officer of Doré Copper Mining, which owned the Chibougamau project before its acquisition by Cygnus.

    He has more than 30 years of experience in the mining industry, covering technical, operational and executive positions.

    His previous appointments include vice president of operations at New Gold Inc. and president and chief executive officer of Minera Panama, the Inmet Mining subsidiary responsible for developing the Cobre Panama project.

    Mast currently serves as president and chief executive officer of PPX Mining Corp. He is a member of l’Ordre des ingénieurs du Québec and holds bachelor’s and master’s degrees in metallurgical engineering from McGill University.

    His appointment was previously outlined in the Cygnus transaction scheme booklet published on 13 August 2026.

    Management Comments on the Transaction

    Nick Clarke, non-executive chairman of Central Asia Metals, said the acquisition forms part of the company’s strategy to combine existing production operations with development and exploration assets.

    Clarke commented:

    “We are delighted to complete this important acquisition for the Company, which forms a key element in our overall strategy of creating a balanced portfolio of profitable production, development-based growth and exploration potential.

    “We also welcome Ernie Mast to the Board as an Independent Non-Executive Director. Ernie’s extensive industry experience will add to the Board’s capabilities, and his long association with the Chibougamau project and his relationships with key stakeholders, both locally and in Canada more generally, will be invaluable as we advance the Chibougamau project towards a development decision.”

    The completion of the acquisition establishes Chibougamau as part of Central Asia Metals’ portfolio, while the company’s comments indicate that the project has yet to reach a development decision.

    More About Central Asia Metals

    Central Asia Metals PLC is a mining company listed on AIM under the ticker LSE:CAML. Following the acquisition of Cygnus Metals, the group includes the Chibougamau copper-gold project among its assets.

    The company has also secured a listing on the Toronto Stock Exchange, expanding its exchange presence beyond London.

    The completed transaction, new share issuance, replacement option grants and board appointment represent the principal corporate changes announced on 27 October 2026.

  • Mello London 2026: 55 companies, two days, and 25% off for ADVFN readers

    Mello London 2026: 55 companies, two days, and 25% off for ADVFN readers

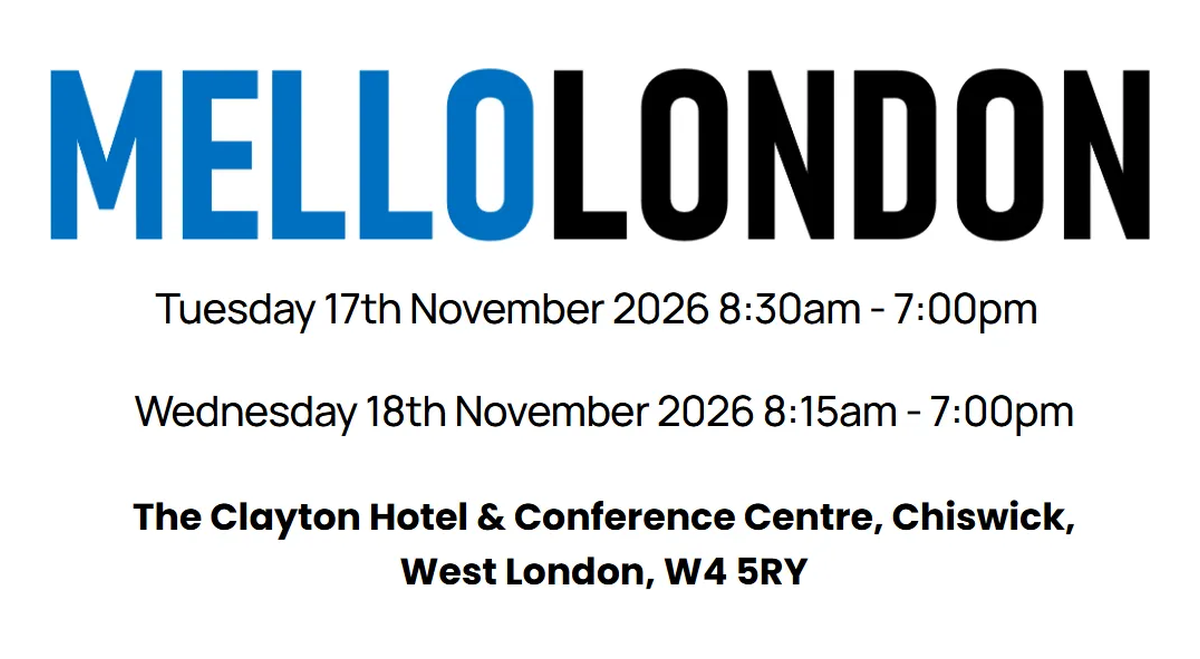
    Mello London, the UK’s two-day investor conference, returns on 17 and 18 November 2026 with 55 companies presenting to private investors. ADVFN readers can save 25% on tickets with the code ADVFN.

    The event takes place at The Clayton Hotel & Conference Centre in Chiswick, west London. It is aimed at individual investors, fund managers and finance professionals, and organiser Mello Events says it attracts more than 450 attendees.

    What to expect

    Over two days, investors can hear from Main Market, AIM and Aquis-listed companies, investment trusts and funds. Keynote speakers include Lord Lee, Richard Staveley and Paul Hill. There is also time to meet analysts, specialist service providers and fellow investors.

    • Dates: Tuesday 17 November, 8:30am to 7pm, and Wednesday 18 November, 8am to 7pm
    • Venue: The Clayton Hotel & Conference Centre, 626 Chiswick High Road, London W4 5RY
    • Getting there: Gunnersbury station (District line and Overground) is a two-minute walk.
    • Schedule: The full presentation timetable will be published by 9 November.

    The companies presenting

    The line-up so far spans technology, healthcare, financials, property, industrials and energy, alongside 12 investment companies and trusts. More names may be added before the event.

    Technology

    • Bango (LSE:BGO) – subscription bundling platform for telcos and retailers
    • Gelion (LSE:GELN) – advanced battery technology for energy storage
    • Made Tech Group (LSE:MTEC) – digital, data and AI services for the UK public sector
    • PCI Pal (LSE:PCIP) – provider of secure payments and experiences across business communications
    • SRT Marine Systems (LSE:SRT) – maritime surveillance and vessel-tracking systems
    • SysGroup (LSE:SYS) – managed cloud, cybersecurity and IT services
    • Tan Delta Systems (LSE:TAND) – real-time oil condition sensors for engines and industrial machinery
    • Ten Technologies Group (LSE:TENG) – concierge and loyalty platform for banks and premium brands, formerly Ten Lifestyle Group
    • Xaar (LSE:XAR) – industrial inkjet printheads
    • ZOO Digital Group (LSE:ZOO) – dubbing, subtitling and localisation for studios and streamers

    Healthcare and life sciences

    • Inspiration Healthcare Group (LSE:IHC) – neonatal intensive-care devices
    • Kooth (LSE:KOO) – digital mental health platforms
    • Renalytix (LSE:RENX) – AI-enabled testing for kidney disease
    • TheraCryf (LSE:TCF) – clinical-stage treatments for addiction and neuropsychiatric disorders
    • Tristel (LSE:TSTL) – chlorine dioxide disinfectants for medical devices
    • Venture Life Group (LSE:VLG) – self-care consumer health brands
    • Verici Dx (LSE:VRCI) – diagnostic tests for kidney transplant patients

    Financials

    • Burford Capital (LSE:BUR) (NYSE:BUR) – litigation finance
    • DF Capital (LSE:DFCH) – specialist bank providing inventory finance to dealers
    • FRP Advisory Group (LSE:FRP) – restructuring, corporate finance and forensic advisory
    • Manx Financial Group (LSE:MFX) – banking and SME lending in the Isle of Man and UK
    • Mercia Asset Management (LSE:MERC) – regional UK private capital manager
    • S&U (LSE:SUS) – motor finance and property bridging loans

    Investment companies and trusts

    • Global Opportunities Trust (LSE:GOT) – global trust buying undervalued assets
    • IP Group (LSE:IPO) – invests in science and technology companies
    • Kelso Group Holdings (LSE:KLSO) – concentrated portfolio of UK smaller companies
    • Molten Ventures (LSE:GROW) – venture capital in European technology
    • Neuberger Private Equity Partners (LSE:NBPE) – co-investments in private equity buyouts, mainly in North America
    • Oberon AIM VCT (LSE:OVCT) – venture capital trust investing in AIM-quoted growth companies
    • Odyssean Investment Trust (LSE:OIT) – concentrated UK smaller companies trust
    • Oxford Technology 2 VCT (LSE:OXH) – venture capital trust with UK science and technology holdings
    • Polar Capital Technology Trust (LSE:PCT) – global technology shares
    • Polar Capital Global Financials Trust (LSE:PCFT) – global banks, insurers, exchanges and fintech
    • Rockwood Strategic (LSE:RKW) – value-driven investor in UK smaller companies
    • Temple Bar Investment Trust (LSE:TMPL) – value-focused UK equity income trust

    Property

    • Living REIT (LSE:LIVE) – supported housing, senior living and care homes, formerly Social Housing REIT
    • LSL Property Services (LSE:LSL) – surveying, estate agency franchising and mortgage services
    • RentGuarantor Holdings (LSE:RGG) – online rent guarantor service for tenants
    • The Property Franchise Group (LSE:TPFG) – the UK’s largest multi-brand estate agency and lettings franchisor

    Industrials and business services

    • Braemar (LSE:BMS) – shipbroking, chartering and risk advisory
    • Franchise Brands (LSE:FRAN) – B2B franchises including Pirtek, Metro Rod and Filta
    • Gattaca (LSE:GATC) – STEM recruitment
    • James Cropper (LSE:CRPR) – advanced materials and premium paper
    • Restore (LSE:RST) – records storage, digitisation, shredding and IT recycling
    • SpaceandPeople (LSE:SAL) – promotional and retail space in shopping centres and stations
    • Trifast (LSE:TRI) – engineered fastenings and components

    Energy

    • Prospex Energy (LSE:PXEN) – gas and power projects in Spain and Italy
    • SulNOx Group (AQSE:SNOX) – fuel-conditioning products that cut emissions and fuel use

    Private companies

    • Kernow Asset Management – boutique UK equity fund manager
    • Nudea – digital-first British lingerie brand

    How to book with the ADVFN discount

    Use code ADVFN at checkout to receive 25% off ticket prices.

    General Sale (available until 10 November)

    Two-day pass: £149 → £111.75 with code ADVFN

    One-day pass: £99 → £74.25 with code ADVFN

    Book tickets @ https://www.tickettailor.com/events/melloeventslimited/2312083· Mello London 2026 event page (https://www.melloevents.com/mellolondon2026)

  • US Stock Futures Point Higher as Crude Oil Retreats and Investors Await Fed Meeting: Dow Jones, S&P, Nasdaq, Wall Street

    US Stock Futures Point Higher as Crude Oil Retreats and Investors Await Fed Meeting: Dow Jones, S&P, Nasdaq, Wall Street

    US stock futures indicated a higher opening on Monday as investors assessed a decline in crude oil prices following two sessions of losses on Wall Street, with attention turning to the Federal Reserve’s monetary policy announcement and earnings from major technology companies.

    The expected advance follows a decline in the Nasdaq Composite to its lowest closing level since early August on Friday, while the S&P 500 finished at a one-month low.

    Lower share prices following the recent sell-off may also encourage some investors to increase their equity holdings.

    However, uncertainty surrounding artificial intelligence investment, monetary policy and developments in the Middle East remains a consideration for financial markets.

    Crude Oil Futures Decline After US Military Reports Export Recovery

    US crude oil futures fell more than 2% on Monday, reversing part of the previous week’s increase.

    The decline followed an announcement by US Central Command (CENTCOM) concerning its support for oil exports from the Gulf region.

    According to CENTCOM, US forces have assisted regional partners in exporting more than 1.5 billion barrels of crude oil since the summer.

    The military command also said more than 3,000 commercial vessels had successfully travelled through the Strait of Hormuz with US support over the past six months.

    The figures indicated that maritime transport and crude shipments had continued despite disruptions associated with the conflict involving Iran.

    Russ Mould, investment director at AJ Bell, said the recovery in exports was helping to reduce concerns about the potential impact of further military action.

    “The ongoing recovery in Middle Eastern exports is easing some of the concerns surrounding the possibility of renewed American and Israeli attacks on Iran,” Mould said.

    Oil prices had risen during the previous week as attacks by Iran-aligned Houthi forces in Yemen against Saudi Arabia added to concerns about regional supply disruptions.

    Reports that the United States and Israel could resume military operations against Iran after the November midterm elections also contributed to the increase.

    On Friday, US crude futures climbed nearly 4%, returning to levels above $100 per barrel, while Brent crude reached a six-month high.

    The subsequent decline on Monday reduced some of the pressure associated with elevated energy prices.

    Federal Reserve Expected to Maintain Interest Rates

    The Federal Reserve’s monetary policy announcement on Wednesday will be among the principal events for US financial markets this week.

    The central bank is widely expected to leave its benchmark interest rate unchanged.

    Investors will examine the accompanying statement for indications of how policymakers are evaluating inflation and the possibility of additional rate increases.

    Market expectations continue to favour a quarter-percentage-point increase at the Fed’s December meeting.

    The outlook for interest rates is particularly relevant to equity valuations and financing costs, including those associated with investment in technology infrastructure.

    Trading volumes could remain relatively limited before the announcement as market participants await further guidance.

    Technology Earnings Could Influence AI Investment Expectations

    Corporate earnings will provide another source of information for investors, particularly following recent declines in technology shares.

    Amazon (NASDAQ:AMZN), Microsoft (NASDAQ:MSFT) and Alphabet (NASDAQ:GOOGL), Google’s parent company, are scheduled to report quarterly financial results.

    Their announcements will be monitored for evidence of demand trends, profitability and spending on artificial intelligence infrastructure.

    Investors have been assessing whether revenue generated from AI products and services will support the substantial capital expenditure required to develop computing capacity.

    Concerns about financing requirements and potential investment returns contributed to the recent weakness in technology stocks.

    The upcoming results could provide further information about spending plans, operating costs and management expectations for future growth.

    Given the companies’ substantial influence on major US equity indices, their financial performance could also affect broader market movements.

    Wall Street Extends Losses on Friday

    US equities declined on Friday following a sell-off during Thursday’s session, with all three major indices finishing lower.

    The Dow Jones Industrial Average recorded the largest percentage decline, falling 652.82 points, or 1.2%, to close at 52,215.16. The index retreated from a one-month closing high reached in the preceding session.

    The S&P 500 declined 39.75 points, or 0.5%, to 7,623.68, its lowest closing level in approximately one month.

    The Nasdaq Composite fell 53.52 points, or 0.2%, to 25,955.34, ending the session at its lowest level since early August.

    For the week, the Dow Jones advanced 0.4%, despite Friday’s decline.

    The S&P 500 and Nasdaq recorded weekly losses of 0.5% and 0.7%, respectively.

    The market movements reflected concerns about AI-related investments, higher oil prices and uncertainty ahead of the Federal Reserve’s next decision.

    Oil Price Increase Affects Airline and Energy Shares

    Friday’s sector performance showed differences between companies exposed to higher energy costs and those operating in the oil industry.

    Airline shares declined as crude prices increased, with the NYSE Arca Airline Index falling 2.6%.

    Fuel is a significant operating expense for airlines, making higher oil prices relevant to their cost outlook.

    Gold mining companies also recorded losses after the price of gold declined.

    The NYSE Arca Gold Bugs Index fell 2.2%, while pharmaceutical and retail stocks also experienced selling pressure.

    Oil services shares moved in the opposite direction.

    The Philadelphia Oil Service Index gained 5.5% as crude prices advanced, reflecting increases among companies providing equipment and services to oil producers.

    The different sector performances illustrated the effects of commodity price movements on companies with varying operating costs and revenue exposures.

    Investors Assess Monetary Policy and Geopolitical Risks

    Monday’s expected gains suggest that US equities could recover part of their recent losses, with lower oil prices providing a change from the conditions that affected markets late last week.

    The Federal Reserve’s decision on Wednesday and earnings from major technology companies will provide further information for investors assessing interest rates, corporate profitability and AI-related capital expenditure.

    Developments in the Middle East will also remain relevant because of their potential implications for oil shipments, energy prices and inflation.

    Market movements during the week will reflect how investors respond to these economic, corporate and geopolitical developments.

  • European Stocks Advance as Oil Prices Decline Ahead of Central Bank Decisions: DAX, CAC, FTSE100

    European Stocks Advance as Oil Prices Decline Ahead of Central Bank Decisions: DAX, CAC, FTSE100

    European stock markets traded mostly higher on Monday, supported by a decline in oil prices as investors prepared for interest rate decisions from major central banks and quarterly earnings announcements from leading technology companies.

    The FTSE 100 gained 0.5%, while France’s CAC 40 and Germany’s DAX each advanced 0.9%.

    Market attention remained focused on developments in the Middle East, the outlook for monetary policy and the financial performance of companies investing heavily in artificial intelligence infrastructure.

    Oil Prices Fall Following Middle East Diplomatic Developments

    Oil prices declined by nearly 2% after Saudi Arabia partially resumed operations at King Khalid International Airport in Riyadh and a Qatari delegation arrived in Tehran for diplomatic discussions.

    The visit was part of renewed efforts to reduce regional tensions, undertaken in coordination with the United States.

    The developments followed disruptions associated with the continuing conflict in the Middle East, which has affected energy markets and raised concerns about regional oil supplies.

    The decline in crude prices provided some relief to equity markets, where investors have been assessing the potential effects of higher energy costs on inflation, corporate expenses and consumer demand.

    Further developments in diplomatic negotiations and regional security remain relevant to the outlook for oil prices.

    Fed, ECB and Bank of Japan Prepare Interest Rate Announcements

    Investors are also awaiting monetary policy decisions from the US Federal Reserve, the European Central Bank and the Bank of Japan.

    The three institutions are scheduled to announce their decisions between 28 and 30 October.

    The meetings come as central banks assess inflation, economic activity and the implications of energy price movements for monetary policy.

    Investors will examine the accompanying statements and comments from policymakers for indications of how interest rates may develop over the coming months.

    The announcements could influence government bond yields, currency markets and equity valuations.

    Technology Earnings to Provide Further Information on AI Spending

    Quarterly results from several major US technology companies are also scheduled for this week.

    Microsoft (NASDAQ:MSFT), Alphabet (NASDAQ:GOOG), Amazon (NASDAQ:AMZN), Intel (NASDAQ:INTC) and SanDisk (NASDAQ:SNDK) are among the companies expected to report earnings.

    The announcements come amid investor scrutiny of spending on artificial intelligence infrastructure and uncertainty about the financial returns from those investments.

    Market participants will assess revenue, profitability, capital expenditure and management guidance for information about demand for AI-related products and services.

    The results could also provide further indications of how technology companies are financing infrastructure expansion and managing associated costs.

    Bolloré and Man Group Shares Rise, Sika Declines

    Individual European companies also recorded share price movements following corporate announcements.

    French conglomerate Bolloré advanced after reporting its group revenue figures for the third quarter and the first nine months of 2026.

    The company’s revenue performance was among the factors drawing investor attention during Monday’s session.

    In London, Man Group (LSE:EMG) shares rose following the announcement of an expanded strategic partnership with Japan’s Meiji Yasuda Life Insurance.

    The agreement extends the relationship between the UK investment management company and the Japanese insurer.

    Meanwhile, shares in Swiss speciality chemicals company Sika (TG:SIKA) declined after the company agreed to acquire Duproof, a Dubai-based manufacturer of waterproofing membranes.

    The acquisition represents an expansion of Sika’s activities in construction-related materials.

    European Market Outlook

    European equities began the week with gains across several major indices as oil prices eased and investors awaited further economic and corporate developments.

    Central bank announcements between 28 and 30 October will provide information about the direction of monetary policy, while technology earnings will offer additional evidence about corporate spending and returns associated with artificial intelligence.

    Developments in the Middle East and company-specific announcements will remain additional factors for European markets.

  • Gold Prices Stabilise Near Three-Month Lows Ahead of Fed Rate Announcement

    Gold Prices Stabilise Near Three-Month Lows Ahead of Fed Rate Announcement

    Gold prices were broadly steady during Asian trading on Monday after declining more than 4% over the previous week, as investors considered the implications of higher energy prices for inflation and US interest rates.

    Spot gold increased 0.2% to $4,005.41 per ounce by 02:28 ET (06:28 GMT), while US gold futures advanced 0.3% to $4,017.45 per ounce.

    The precious metal had fallen below $4,000 on Friday for the first time since mid-July, contributing to a weekly decline of 4.1%.

    Prices remained close to their lowest levels in approximately three months as financial markets prepared for the Federal Reserve’s monetary policy meeting on 27–28 October.

    Investors are also monitoring the outlook for energy costs, government bond yields and developments in the Middle East.

    Rising Energy Costs Add to Inflation Considerations

    The recent decline in gold prices followed a substantial increase in crude oil prices associated with the ongoing conflict in the Middle East.

    Brent crude gained 6.2% during the previous week, reaching its highest weekly closing level since mid-2022.

    Oil prices subsequently moved lower on Monday following reports of diplomatic initiatives aimed at reducing regional tensions.

    Higher energy prices can contribute to inflation by increasing transportation and production costs across the economy.

    If these pressures persist, central banks may have less scope to reduce borrowing costs and could maintain restrictive monetary policies for longer.

    Gold is frequently held as a hedge against inflation and geopolitical uncertainty.

    However, the metal does not provide interest income, meaning higher yields on government bonds and other interest-bearing securities can reduce its relative attractiveness.

    This relationship has been an important consideration for investors as energy prices and interest rate expectations have changed.

    Federal Reserve Expected to Hold Rates at October Meeting

    The Federal Reserve is widely expected to leave its benchmark interest rate unchanged when policymakers meet on 27 and 28 October.

    Market participants will therefore focus on the central bank’s assessment of inflation and its guidance regarding the possibility of further rate increases.

    According to CME FedWatch data, markets were pricing in approximately a 78% probability of an interest rate increase at the December meeting.

    The expectations followed recent US consumer and producer inflation reports that exceeded economists’ forecasts.

    The figures indicated that price pressures could remain persistent despite continued economic growth.

    Investors will be assessing whether the Federal Reserve considers these developments sufficient to justify additional monetary tightening before the end of the year.

    A decision to maintain rates in October would not necessarily rule out further adjustments at subsequent meetings.

    US PCE Inflation Report Scheduled for 29 October

    The personal consumption expenditures price index for September is due to be released on 29 October.

    The PCE index is the Federal Reserve’s preferred measure of inflation and provides information about changes in prices paid by US consumers.

    The report will offer further evidence about whether inflation is moving towards the central bank’s 2% target.

    Investors will compare the figures with recent consumer and producer price data, which showed inflation running above expectations.

    A higher-than-anticipated reading could reinforce expectations of restrictive monetary policy, while a lower reading could affect market assessments of the timing of future interest rate decisions.

    Changes in interest rate expectations can influence gold through their effects on Treasury yields and the US dollar.

    US Treasury Yields Remain Elevated

    The yield on the benchmark 10-year US Treasury note stood close to 5%, maintaining pressure on non-yielding assets such as gold.

    Higher bond yields increase the potential income available from fixed-income securities relative to holding bullion.

    However, uncertainty about the duration of the Middle East conflict has continued to provide some support for demand for assets traditionally regarded as safe havens.

    The interaction between these factors has contributed to gold trading around $4,000 per ounce following the previous week’s decline.

    Market participants will continue to assess the balance between interest rate expectations and demand linked to international uncertainty.

    Silver Little Changed as Platinum and Copper Fall

    Other precious and industrial metals recorded mixed movements during Monday’s session.

    Silver traded broadly unchanged at $53.95 per ounce.

    Platinum declined 0.6% to $1,543.71 per ounce.

    Copper prices also moved lower, with benchmark futures on the London Metal Exchange falling 0.4% to $14,277.33 per tonne.

    US copper futures decreased 0.2% to $6.49 per pound.

    The movements occurred as commodity markets evaluated the outlook for economic activity, monetary policy and international supply conditions.

    Gold Market Awaits Further Guidance on US Interest Rates

    Gold remained near a three-month low despite modest gains during Monday’s Asian trading session.

    The metal’s weekly decline of 4.1% came amid higher energy costs, elevated US Treasury yields and expectations that interest rates could remain restrictive.

    The Federal Reserve’s October policy decision and the September PCE inflation report, due on 29 October, will provide additional information about the outlook for borrowing costs.

    Developments in the Middle East will also remain relevant to both energy prices and demand for gold as a safe-haven asset.

  • Crude Oil Prices Retreat as Saudi Infrastructure Attacks Keep Supply Risks in Focus

    Crude Oil Prices Retreat as Saudi Infrastructure Attacks Keep Supply Risks in Focus

    International crude oil prices moved lower on Monday following the previous week’s gains, as investors assessed diplomatic efforts involving the United States and Iran alongside further attacks on Saudi Arabian infrastructure.

    Brent crude futures declined $1.90, or 1.63%, to $114.82 per barrel by 09:59 GMT. US West Texas Intermediate (WTI) futures fell $2.08, equivalent to 2%, to $101.19 per barrel.

    Despite the declines, both benchmarks remained close to their highest levels in six months.

    Oil prices had settled almost $3 higher on Friday, contributing to weekly gains of approximately 6% for Brent and 2.3% for WTI.

    The latest trading movements reflected the interaction between reported diplomatic initiatives and continuing concerns about energy infrastructure and maritime security in the Middle East.

    Saudi Arabia Reports Further Missile and Drone Interceptions

    Security developments in Saudi Arabia remained a focus for oil traders following additional attacks claimed by Yemen’s Iran-backed Houthi movement.

    The Houthis said they had targeted pumping stations on Saudi Arabia’s East-West crude oil pipeline and Riyadh airport during the weekend.

    Saudi authorities reported on Sunday that they had intercepted further missiles and drones.

    The attacks have drawn attention to the security of Saudi Arabia’s oil transportation infrastructure.

    The East-West pipeline provides a route for transporting crude across Saudi territory and forms part of the country’s export logistics network.

    Disruptions affecting such infrastructure can influence transportation arrangements and contribute to uncertainty about the availability of regional oil supplies.

    John Evans, an analyst at PVM Oil Associates, said the additional risks associated with Houthi attacks could support buying interest if Brent returned to the lows recorded during the previous week.

    “With the jeopardy doubled by Houthi attacks into Saudi, any Brent price dips back to the lows of last week will find grateful buyers,” Evans said.

    He added that the scale of price corrections was difficult to measure and that the recent decline had not reached levels that would necessarily cause investors expecting higher prices to reconsider their positions.

    His comments reflected an assessment of market positioning rather than a confirmed forecast of future oil prices.

    Diplomatic Contacts Continue Between Iran and Regional Governments

    Diplomatic initiatives aimed at reducing regional tensions continued on Sunday, when Qatari mediators travelled to Tehran.

    According to an official briefed on the discussions, the visit formed part of an effort coordinated with the United States to explore possible measures to reduce hostilities.

    Senior officials from Saudi Arabia, Turkey and Pakistan were also scheduled to meet Iranian leaders in Tehran on Monday.

    The three countries are associated with the Mecca Pact, and the planned meeting would represent their first high-level contact with Iranian officials since attacks on Saudi Arabia became a prominent issue in the wider conflict.

    The diplomatic activity occurred alongside continuing military operations.

    Despite the discussions, the Houthis reported additional attacks during the weekend, while Saudi Arabia confirmed further interceptions of missiles and drones.

    No agreement ending the hostilities or restoring normal energy transportation operations had been announced.

    Oil traders therefore continued to monitor the potential for diplomatic progress alongside the possibility of further disruptions.

    Maritime Security Incidents Affect Major Energy Shipping Routes

    The conflict involving the United States, Israel and Iran, which began on 28 February, continues to affect commercial shipping through important Middle Eastern waterways.

    Companies have been adjusting transportation arrangements in response to disruptions affecting the Strait of Hormuz and the Bab el-Mandeb Strait.

    Both waterways are significant routes for international energy trade.

    The Strait of Hormuz connects the Persian Gulf with international shipping routes, while Bab el-Mandeb provides access between the Red Sea and the Gulf of Aden.

    Interruptions to maritime traffic can affect delivery schedules, vessel deployment and transportation costs.

    Data compiled by the Washington Institute for Near East Policy indicated that October had recorded the highest number of attacks on commercial shipping in the Strait of Hormuz and nearby waters since the organisation began monitoring maritime security incidents in 2017.

    The increase in reported incidents has added to concerns about the reliability of shipping routes used by energy exporters and importers.

    Companies operating in the region have consequently been assessing alternative arrangements to manage deliveries and transportation risks.

    Saudi Aramco Announces Singapore Storage Plans

    Saudi Aramco is preparing to begin storing crude oil in Singapore during the second half of 2027, according to an announcement involving energy ministers from Saudi Arabia and Singapore.

    The arrangement is intended to improve the resilience of the Saudi state-owned company’s supply chain in Asia.

    Establishing additional storage capacity in Singapore would provide another location for maintaining crude inventories closer to regional customers.

    The arrangement could also offer greater flexibility in managing delivery schedules and responding to transportation disruptions.

    The announcement comes amid adjustments to international energy logistics resulting from the conflict and restrictions affecting established shipping routes.

    The information released did not specify the planned storage volume or provide further details about the facilities involved.

    IEA Director Expects Energy Market Changes to Persist Into 2027

    International Energy Agency Executive Director Fatih Birol addressed the longer-term implications of the conflict during an industry event in Singapore on Monday.

    Birol said he did not expect energy markets in 2027 to return to the conditions that prevailed before the war involving Iran.

    His assessment indicated that changes affecting energy transportation and supply arrangements could remain relevant beyond the immediate period of military operations.

    The comments came as producers and importing countries considered adjustments to supply chains and infrastructure.

    Future market conditions will depend on developments in the conflict, the restoration of commercial shipping routes and changes in global energy supply arrangements.

    Oil Supply Outlook Remains Linked to Regional Developments

    The decline in oil prices on Monday followed reports of diplomatic efforts to reduce tensions involving Iran and the United States.

    However, Brent at $114.82 per barrel and WTI at $101.19 remained close to six-month highs after the previous week’s increases.

    Continued attacks on Saudi infrastructure and disruptions affecting major maritime routes remain important considerations for oil supply expectations.

    The planned expansion of Saudi Aramco’s storage arrangements in Singapore and the IEA’s assessment of longer-term market conditions also highlight changes under consideration across the international energy industry.

    Investors will continue to assess developments in regional security, diplomatic negotiations and transportation conditions when evaluating the outlook for crude oil prices.