Author: Fiona Craig

  • Topps Tiles maintains resilient sales as cost savings and digital growth support performance (TPT)

    Topps Tiles maintains resilient sales as cost savings and digital growth support performance (TPT)

    Market weakness weighs on third-quarter revenue

    Topps Tiles (LSE:TPT) reported third-quarter group revenue of £75.6 million, down 1.8% from the previous year as subdued consumer demand, CTD store closures and the closure of underperforming Topps Tiles locations affected sales.

    Excluding the impact of CTD, core revenue edged 0.6% higher, while like-for-like sales at the Topps Tiles brand remained unchanged. Although the company continued to outperform the declining UK home improvement market, trading was weaker than anticipated as customers shifted towards lower-priced products and periods of hot weather disrupted activity across construction sites.

    Cost-saving measures and online growth support margins

    The group said it continued to make progress on initiatives designed to improve efficiency and protect profitability, including optimising its store estate, introducing a more flexible labour model and consolidating head office operations.

    Digital sales continued to expand, with online revenue accounting for 23.3% of total sales during the quarter. The launch of a new trade-focused mobile app also supported professional customers, while newer hard surface categories such as acoustic panels and outdoor tiles delivered double-digit growth. Despite these positive developments, the company expects adjusted pre-tax profit for the year to be slightly above £6.5 million as broader economic challenges continue to affect demand.

    Cash generation offsets balance sheet concerns

    Topps Tiles’ investment outlook is supported by improving financial performance, strong cash generation and ongoing cost-saving initiatives, alongside a generally constructive earnings outlook.

    However, these strengths are balanced by relatively high balance sheet leverage and weaker technical indicators, including a negative MACD signal and a share price trading below key moving averages. The valuation also appears relatively demanding, although the company’s dividend yield continues to provide support for income-focused investors.

    More about Topps Tiles

    Topps Tiles is the UK’s largest specialist retailer of tiles and hard surface flooring products, supplying ceramic and porcelain tiles, flooring accessories and related materials to both retail and trade customers. The group operates its core Topps Tiles business alongside the recently acquired CTD brand and continues to expand its digital capabilities while serving the home improvement and commercial construction markets.
  • Associated British Foods maintains full-year outlook as Primark growth offsets Sugar challenges (ABF)

    Associated British Foods maintains full-year outlook as Primark growth offsets Sugar challenges (ABF)

    Primark expansion supports steady third-quarter performance

    Associated British Foods (LSE:ABF) reported a resilient third-quarter trading performance, with group revenue broadly unchanged at constant exchange rates as growth in Primark, Ingredients and Grocery helped offset weaker results from its Sugar and Agriculture businesses.

    Primark delivered a 3% increase in sales, supported by new store openings across Europe, the United States and the Middle East. However, like-for-like sales declined as consumer demand remained subdued, particularly in continental Europe.

    Sugar outlook weakens despite progress across other divisions

    The group reaffirmed its full-year guidance for all businesses excluding Sugar. Within the Sugar division, however, higher natural gas costs linked to tensions in the Middle East, together with operational uncertainty in Africa, have led the company to forecast an adjusted operating loss of between £25 million and £60 million for the current financial year.

    Associated British Foods said it continues to invest in Primark’s product offering, competitive pricing and digital marketing initiatives, while Grocery and Ingredients delivered steady growth. The company also highlighted continued progress with the acquisition of Hovis, reflecting confidence in its long-term strategy despite ongoing challenges in European sugar operations and softer revenue from Agriculture.

    Attractive valuation balanced by cautious earnings outlook

    Associated British Foods’ investment outlook reflects generally stable financial performance, although management expects profit and earnings per share to remain below 2025 levels, largely due to the anticipated losses within the Sugar business.

    The shares continue to benefit from an attractive valuation, supported by a relatively low price-to-earnings ratio and a solid dividend yield. However, technical indicators remain neutral to slightly negative, suggesting limited momentum in the near term.

    More about Associated British Foods

    Associated British Foods is an international food, ingredients and retail group whose largest consumer business is value fashion retailer Primark. The company also operates across grocery, sugar, agriculture and specialty ingredients, supplying branded and private-label products to customers in Europe, the UK, the US, Africa and other international markets.

  • Goldplat expects FY2026 results to beat market forecasts on higher gold prices (GDP)

    Goldplat expects FY2026 results to beat market forecasts on higher gold prices (GDP)

    Strong trading driven by robust gold market and processing volumes

    Goldplat plc (LSE:GDP) has announced that it expects its financial results for the year ended 30 June 2026 to materially exceed current market expectations.

    The company said the stronger-than-anticipated performance has been supported by sustained high gold prices alongside strong processing volumes across its gold recovery operations in South Africa and Ghana.

    Higher commodity prices boost profitability outlook

    The trading update highlights the sensitivity of Goldplat’s recovery business to favourable commodity price movements and increased processing throughput.

    Classified as inside information under the UK Market Abuse Regulation (MAR), the announcement points to stronger profitability than previously anticipated and reinforces the company’s position as a specialist provider of gold recovery services within the mining sector.

    Strong balance sheet offsets operational challenges

    Goldplat’s investment outlook is supported by a solid financial position, healthy cash generation, a very low price-to-earnings ratio and a modest dividend yield.

    These strengths are balanced by declining revenue and pressure on profit margins, while technical indicators remain positive but suggest the shares may be approaching overbought territory, potentially increasing short-term price volatility.

    More about Goldplat

    Goldplat plc is an AIM-listed mining services company specialising in gold recovery operations. The group operates processing facilities in South Africa and Ghana, recovering gold from mining by-products and residual materials for customers across the African and South American mining industries. Its business model provides an alternative to traditional gold mining by extracting additional value from existing mining waste streams.

  • IQE appoints MACOM executives to board under strategic partnership agreement (IQE)

    IQE appoints MACOM executives to board under strategic partnership agreement (IQE)

    Board additions strengthen ties with major shareholder

    IQE plc (LSE:IQE) has appointed MACOM Technology Solutions executives Robert Dennehy and David O’Carroll as non-executive directors, in accordance with the board appointment agreement previously established between the two companies.

    The appointments further strengthen the relationship between IQE and MACOM, which holds an 11.5% stake in the compound semiconductor wafer manufacturer, and could support closer strategic alignment between the long-standing industry partners.

    New directors bring extensive operational and industry experience

    Dennehy, MACOM’s senior vice president and chief operating officer, brings more than 30 years of leadership and operational experience gained across Europe and the United States.

    O’Carroll adds expertise in international operations, finance and government relations, with experience spanning both European and Asian markets. IQE said the appointments support its strategy of positioning the business to capture future growth opportunities, while potentially enhancing collaboration across the global semiconductor supply chain.

    Financial pressures remain despite improving market momentum

    IQE’s investment outlook continues to be constrained by weak financial performance, including ongoing losses, a negative gross profit reported during 2025, negative free cash flow, rising debt levels and declining shareholder equity.

    These challenges are partly offset by stronger technical indicators, with the shares trading above key moving averages and supported by a positive MACD signal. However, valuation remains difficult to assess given the company’s negative earnings and the absence of a dividend.

    More about IQE plc

    IQE plc is a Cardiff-based manufacturer of advanced compound semiconductor wafers and engineered materials used in smart devices, communications infrastructure, automotive and industrial applications, as well as aerospace and defence technologies. The company operates epitaxy wafer manufacturing facilities in the UK, the US and Taiwan, supplying proprietary semiconductor materials to global chipmakers and original equipment manufacturers. IQE’s shares are listed on the AIM market of the London Stock Exchange.

  • MedPal AI launches largest robotic pharmacy facility to expand dispensing capacity (MPAL)

    MedPal AI launches largest robotic pharmacy facility to expand dispensing capacity (MPAL)

    New Runcorn hub increases automation and prescription throughput

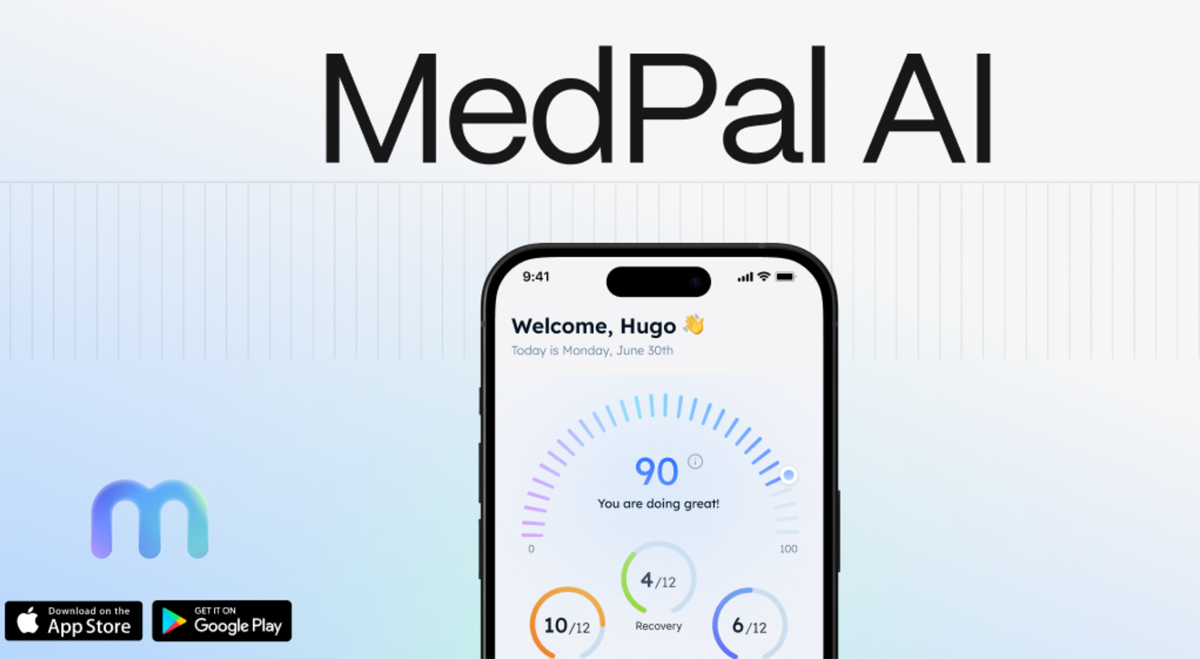
    MedPal AI (LSE:MPAL) has opened Sarus Court, its largest robotic pharmacy dispensing and distribution centre to date, marking a significant expansion of the company’s technology-driven healthcare operations.

    Located in Runcorn, the 23,000-square-foot NHS-approved facility replaces the group’s previous site in the town while operating alongside its existing Swaffham location. The new hub is being brought online in phases and is expected to process more than 2,000 prescription items each day during its initial rollout.

    £1m investment supports long-term growth plans

    The new facility has been developed with more than £1 million invested in robotics, automation and MedPal AI’s proprietary pharmacy technology platform.

    Once fully operational, Sarus Court is expected to handle more than 10,000 prescription items per day, equating to over 300,000 prescriptions each month. The expanded capacity strengthens MedPal AI’s direct-to-patient dispensing model and supports its ambitions to grow across NHS prescription services, private healthcare, AI-powered patient engagement and nationwide medication fulfilment.

    The company said the scale of the operation positions it among the UK’s most ambitious technology-led pharmacy providers, with planned processing capacity exceeding prescription volumes reported by a number of established digital and high street competitors.

    More about MedPal AI Plc

    MedPal AI is a UK digital healthcare company developing MedPal Health OS, an integrated platform that combines artificial intelligence, clinical services and automated pharmacy fulfilment.

    Its consumer app brings together data from more than 100 wearable devices and health applications to create unified health profiles while providing access to NHS and private prescription services. Through its subsidiary, MedPal Limited, the group operates a 24-hour AI-enabled pharmacy distribution network using robotic dispensing technology and automated triage to deliver medicines efficiently across the UK with same-day and next-day delivery options.

  • Chemring secures up to $48.8m US biological threat detection contract (CHG)

    Chemring secures up to $48.8m US biological threat detection contract (CHG)

    Sole-source award strengthens position in US defence market

    Chemring (LSE:CHG) has announced that its US subsidiary, Chemring Sensors & Electronic Systems, has been awarded a sole-source Indefinite Delivery/Indefinite Quantity (IDIQ) full-rate production contract for the Joint Biological Tactical Detection System (JBTDS) programme.

    The contract has a maximum value of $48.8 million and is scheduled to run through 2029. It includes an initial production order worth $36.3 million, with work expected to continue until March 2028. The award further reinforces Chemring’s position as a leading supplier of biological warfare agent detection systems to the US military.

    Contract builds on successful testing and expands CBRN portfolio

    The JBTDS programme follows successful field testing and operational acceptance trials, with production to be carried out at Chemring’s facility in Charlotte, North Carolina.

    The latest award complements the company’s existing sole-source role on the US Navy’s Enhanced Maritime Biological Detector programme, increasing its exposure to long-term spending on chemical, biological, radiological and nuclear (CBRN) defence. The contract also reflects growing demand for advanced detection technologies capable of identifying increasingly complex biological threats.

    Strong order book supports outlook despite valuation concerns

    Chemring’s investment outlook is underpinned by solid financial performance and positive management commentary, particularly regarding continued momentum within its Energetics division.

    However, weaker technical indicators and a relatively high price-to-earnings ratio suggest a more cautious near-term outlook. While the company’s record order book and long-term growth strategy remain significant strengths, pressure on cash flow and an elevated valuation continue to weigh on the overall investment case.

    More about Chemring

    Chemring Group is a FTSE 250 defence, aerospace and security company supplying advanced technologies and specialist services to customers in more than 50 countries. Operating through its Sensors & Information and Countermeasures & Energetics divisions, the company develops mission-critical products designed to protect people, infrastructure and military platforms against evolving security threats.

  • Amcomri sells Premier Limpet for £10.1m to fund future acquisitions (AMCO)

    Amcomri sells Premier Limpet for £10.1m to fund future acquisitions (AMCO)

    Disposal generates cash for next stage of growth strategy

    Amcomri Group (LSE:AMCO) has agreed the sale of Premier Limpet, the UK’s largest independent manufacturer of printed and plain adhesive tape, to Dalpo Group UK for a minimum consideration of £10.1 million.

    Following the repayment of debt, the transaction is expected to deliver approximately £7 million in net cash proceeds. The disposal comes after a three-year programme that improved Premier Limpet’s profitability and included the integration of a bolt-on acquisition in the water-activated adhesive tape market, positioning the business for its next phase of expansion under its new European owner.

    Sale highlights success of acquisition strategy

    According to Amcomri, the disposal represents a return of around 28 times its invested capital, demonstrating the effectiveness of its “Buy, Improve, Build” strategy in creating value from specialist industrial businesses.

    The company intends to reinvest the proceeds into further acquisitions across the specialist engineering and industrial manufacturing sectors, supporting its acquisition-led growth strategy. Management also confirmed that trading remains in line with market expectations, providing additional confidence as it pursues new investment opportunities.

    Strong performance balanced by premium valuation

    Amcomri’s investment outlook is supported by solid financial performance and favourable technical indicators, reflecting positive momentum in the company’s shares.

    However, its valuation remains relatively demanding, which could limit upside if future growth expectations are not met. With no recent earnings call updates or significant additional corporate developments beyond the disposal, these factors have little impact on the current outlook.

    More about Amcomri Group Plc

    Amcomri Group plc is a UK and Ireland-focused engineering services and industrial manufacturing group operating under a “Buy, Improve, Build” strategy. Through its specialist engineering and business-to-business manufacturing divisions, the company supplies technical products and services to customers across the industrial, infrastructure, transport and energy sectors. Amcomri primarily acquires owner-managed businesses, seeking to improve operational performance while supporting long-term organic and acquisition-driven growth.

  • Greggs appoints new finance chief as CFO Richard Hutton prepares for retirement (GRG)

    Greggs appoints new finance chief as CFO Richard Hutton prepares for retirement (GRG)

    Planned leadership transition to take effect in 2027

    Greggs (LSE:GRG) has announced that Chief Financial Officer Richard Hutton will retire at the end of 2026 after 28 years with the business, including 20 years as a board director.

    Hutton will remain in his current role until the end of the year to ensure an orderly handover, reflecting the company’s focus on maintaining continuity throughout the leadership transition.

    Ben Waldron named CFO-designate

    The board has appointed former Bakkavor executive Ben Waldron as CFO-designate and executive director. He is scheduled to join Greggs in late October 2026 before officially assuming the role of Chief Financial Officer on 1 January 2027.

    With extensive financial and operational experience across international food businesses, Waldron is expected to support Greggs’ long-term growth strategy while providing continuity in the group’s financial leadership.

    Solid fundamentals tempered by near-term pressures

    Greggs’ investment outlook continues to be supported by a resilient operating business, although earnings quality softened during 2025 as margins, earnings per share and free cash flow weakened while leverage increased.

    The company’s valuation remains relatively attractive, with a price-to-earnings ratio of around 14 and a dividend yield of approximately 3.34%. Technical indicators are generally constructive, although momentum signals are mixed. Management has maintained a balanced outlook, highlighting positive sales trends and a manageable inflation and capital expenditure environment, while acknowledging flat profit expectations and continued investment in the supply chain.

    More about Greggs plc

    Greggs plc is a UK-based food-on-the-go retailer operating a nationwide network of bakeries and takeaway outlets. The company offers a wide range of freshly prepared food and drink, including pastries, sandwiches, savouries and hot beverages, serving value-focused consumers across high streets, retail parks, transport hubs and convenience locations. Greggs continues to expand its national footprint while investing in operational capacity to support future growth.

  • Sanderson Design Group reports continued trading growth and reiterates full-year guidance (SDG)

    Sanderson Design Group reports continued trading growth and reiterates full-year guidance (SDG)

    AGM update highlights positive start to FY2027

    Sanderson Design Group PLC (LSE:SDG) has confirmed that positive trading momentum has continued into FY2027, with the luxury interiors company reporting year-on-year growth since the start of the financial year while maintaining its full-year outlook.

    The update, provided at the company’s Annual General Meeting, indicates that the improvement seen during the second half of FY2026 has carried into the new financial year. The board reaffirmed its confidence in the group’s strategy, the strength of its portfolio of premium brands and its balance sheet, while confirming that a half-year trading update will be published in early August.

    Established brands support long-term growth strategy

    Sanderson Design Group designs and manufactures luxury wallpapers, fabrics and paints, while also generating licensing income through the use of its designs across homeware categories including bedding, rugs, tableware and other furnishings.

    Its portfolio includes well-known brands such as Zoffany, Sanderson and Morris & Co., supported by a UK manufacturing base and an international showroom network that strengthens the group’s position in the premium interiors market.

    Valuation and technical trends remain supportive

    Sanderson’s investment outlook benefits from an attractive valuation, with a relatively low price-to-earnings ratio and a dividend yield that adds to shareholder appeal.

    Technical indicators also remain supportive, with the shares trading above key moving averages and maintaining positive momentum. These strengths are balanced by relatively modest operating profitability, despite the company’s stronger financial performance during 2026 following earlier periods of volatility.

    More about Sanderson Design Group PLC

    Sanderson Design Group PLC is a UK-based designer, manufacturer and marketer of luxury wallpapers, fabrics and paints. The company also licenses its heritage designs for a wide range of homeware products, including bed and bath collections, rugs, blinds and tableware.

    Alongside brands including Harlequin, Clarke & Clarke and Scion, the group operates manufacturing facilities in Loughborough and Lancaster and maintains showrooms in London, New York and Chicago. Sanderson also manufactures products for third-party wallpaper and fabric brands, providing additional revenue streams and supporting its presence in the global premium interiors market.

  • Shearwater secures £25m telecoms contract extension through Brookcourt Solutions (SWG)

    Shearwater secures £25m telecoms contract extension through Brookcourt Solutions (SWG)

    Five-year agreement strengthens long-standing customer relationship

    Cybersecurity specialist Shearwater (LSE:SWG) has announced that its subsidiary, Brookcourt Solutions, has won a five-year contract expansion valued at approximately £25 million with a leading UK-based global telecommunications provider.

    The agreement extends an established partnership and covers the continued supply of packet monitoring, forensic analysis and service assurance technologies across the customer’s network infrastructure and key strategic accounts. The award further reinforces Brookcourt’s position as a provider of network visibility and assurance solutions for the telecommunications sector.

    Contract boosts revenue visibility for FY26

    The contract is expected to generate around £25 million in revenue over the five-year term, with approximately £12.5 million anticipated to be recognised during FY26 through the delivery of initial software and support licences.

    The board said the award leaves the company confident of meeting market expectations for both revenue and EBITDA in FY26. Although the first cash payment is expected to be received in early FY27, resulting in period-end cash of roughly £5.6 million—around 20% below market forecasts—management believes the improved revenue visibility strengthens Shearwater’s long-term growth outlook within the telecoms cybersecurity and network intelligence market.

    Financial challenges remain despite operational momentum

    Shearwater’s investment outlook continues to be influenced by weak financial quality, with the company remaining loss-making and reporting declining free cash flow despite delivering strong revenue growth.

    Short-term technical indicators provide some support, with the shares trading above their 20-day and 50-day moving averages alongside a positive MACD signal. However, valuation remains constrained by negative earnings and the absence of a dividend yield.

    More about Shearwater

    Shearwater Group plc is a UK-based cybersecurity company providing managed security services and specialist consulting to organisations worldwide. Its portfolio includes identity and access management, data protection, managed cybersecurity services, governance, risk and compliance, and wider cyber advisory solutions. The group continues to pursue a buy-and-build strategy to expand its presence across the cybersecurity and managed services markets, with its shares listed on AIM under the ticker SWG.