Author: Fiona Craig

  • ITM Power’s Hydropulse Signs Heads of Terms for 150 MW Green Hydrogen Project at European Refinery

    ITM Power’s Hydropulse Signs Heads of Terms for 150 MW Green Hydrogen Project at European Refinery

    ITM Power (LSE:ITM) has announced that its Hydropulse subsidiary has signed Heads of Terms with a European oil refinery for a proposed 150 MW green hydrogen production facility, with the project expected to operate under a 10-year agreement.

    The proposed development will use ITM Power’s Alpha electrolyser technology and follow Hydropulse’s build-own-operate (BOO) business model. Under the arrangement, Hydropulse would be responsible for constructing, owning and operating the hydrogen production facility, supplying hydrogen to the refinery under a long-term commercial agreement.

    The project is targeting a final investment decision in 2027, with hydrogen production expected to begin in 2029, subject to the necessary development and investment approvals.

    According to ITM Power, the refinery will provide electricity and utilities required for hydrogen production. This arrangement is intended to reduce Hydropulse’s exposure to fluctuations in electricity prices while supporting contracted revenue generation over the proposed operating period.

    Management described the agreement as the company’s largest potential commercial commitment to date, based on the planned capacity of the facility and the proposed contractual arrangements.

    The signing of Heads of Terms represents an initial stage in the project’s commercial development, with final agreements and investment decisions still to be completed.

    ITM Power said joint front-end engineering and design (FEED) activities are already progressing with the refinery customer. These studies will support the technical development of the proposed facility ahead of the targeted final investment decision.

    Hydropulse is also holding discussions with banks regarding potential project-level financing. The company is evaluating funding arrangements intended to support construction and operation of the facility under its BOO model.

    The proposed 150 MW development forms part of ITM Power’s strategy to expand its involvement in hydrogen production and supply, alongside its existing electrolyser manufacturing business.

    Through Hydropulse, the group aims to establish long-term hydrogen supply agreements with industrial customers seeking to reduce emissions from their operations.

    The refinery project remains subject to further development, financing arrangements and a final investment decision before construction and commercial hydrogen production can proceed.

    About ITM Power plc

    ITM Power plc is a UK-headquartered developer and manufacturer of proton exchange membrane (PEM) electrolyser technology used to produce green hydrogen from electricity and water.

    The AIM-listed company supplies industrial-scale hydrogen production equipment to customers in the energy and industrial sectors, including its standardised Alpha electrolyser platform.

    Through its Hydropulse subsidiary, ITM Power also operates a build-own-operate business model under which it develops, owns and manages hydrogen production facilities and supplies hydrogen directly to industrial customers.
  • Mila Resources Extends Gold Mineralisation to 170 Metres Depth at Yarrol Project

    Mila Resources Extends Gold Mineralisation to 170 Metres Depth at Yarrol Project

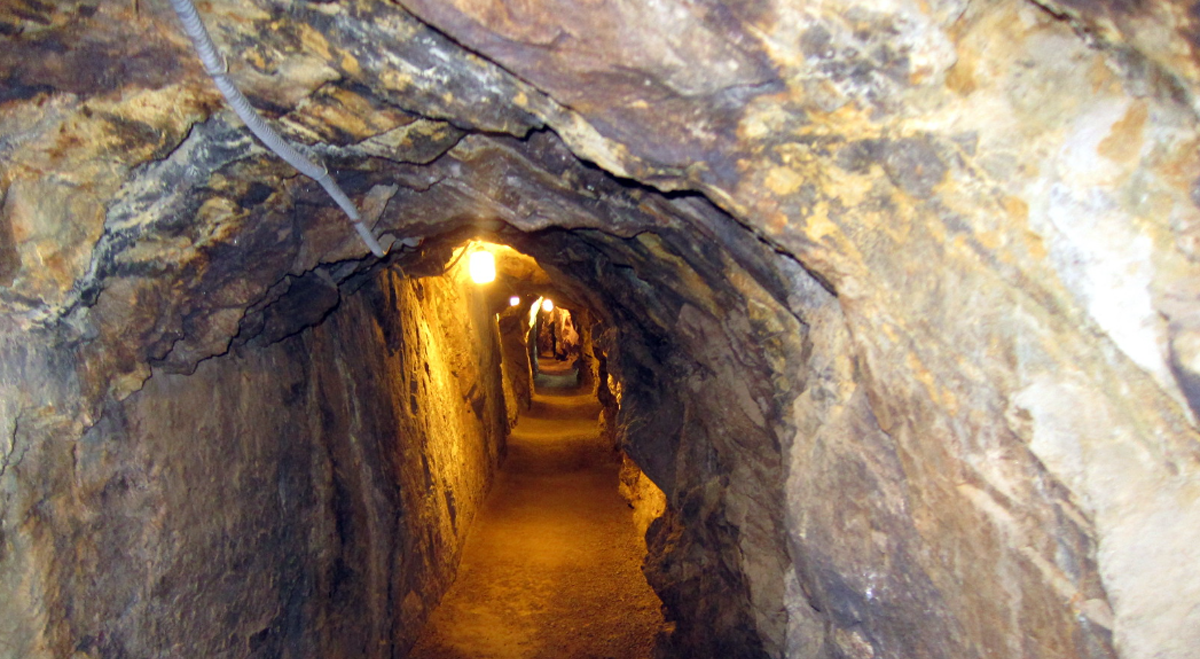
    Mila Resources (LSE:MILA) has reported additional gold assay results from its third-quarter reverse circulation drilling programme at the Yarrol Gold Project in Queensland, Australia, extending the known mineralised zone at Yarrol North to approximately 170 metres below surface.

    The latest results cover four of the nine holes drilled during the programme, with each returning multiple stacked gold intercepts. The drilling has identified mineralisation beyond the historical depth limits of approximately 60 to 70 metres, providing further information about the extent and geological structure of the deposit.

    Two drill holes, MYARC0224 and MYARC0225, intersected gold mineralisation at depth, including broader mineralised intervals containing narrower zones of higher-grade material. According to Mila, the results demonstrate vertical continuity within the gold-bearing system and support its geological interpretation of an east-dipping, structurally controlled deposit.

    The company said the findings indicate that the historical resource area forms part of a wider mineralised corridor associated with the Yarrol Fault. Gold mineralisation remains open at depth and along the fault structure, with further drilling required to establish its full extent.

    Mila’s geological model identifies multiple higher-grade gold shoots within a broader sheeted-vein system. Management said the latest drilling has increased its confidence in the interpretation of these structures and provided additional information for planning future exploration.

    The company is continuing to evaluate the relationship between the higher-grade intercepts and the wider mineralised envelope as it works towards defining the project’s resource potential.

    Assay results from the remaining five holes completed during the third-quarter programme are still pending. Mila expects the outstanding results to help determine the location and scope of subsequent drilling aimed at testing extensions to the known mineralisation.

    The company is targeting completion of an initial mineral resource estimate for Yarrol during the fourth quarter of 2026, using the results of its ongoing exploration and geological assessment work.

    The latest drilling forms part of Mila’s programme to reassess the historical Yarrol resource area and investigate additional mineralisation along the fault corridor. Further exploration will be required to establish the size and continuity of the mineralised system beyond the areas tested to date.

    About Mila Resources Plc

    Mila Resources Plc is a London-listed natural resources company focused on gold and copper exploration and resource development in Australia.

    Its principal asset is the 100%-owned Yarrol Gold Project in Queensland, located within the North New England Fold Belt. The project contains an intrusion-related gold system associated with the Yarrol Fault corridor, including historical workings and previously identified mineralisation.

    The company is using systematic drilling, geological modelling and machine-learning-assisted exploration targeting to reassess the historical resource area and identify potential extensions to the mineralised system.

  • Hays Reports 3% Decline in First-Quarter Net Fees as Restructuring Savings Reach £125 Million

    Hays Reports 3% Decline in First-Quarter Net Fees as Restructuring Savings Reach £125 Million

    Hays (LSE:HAS) reported a 3% decline in group net fees on a like-for-like basis for the first quarter of its 2027 financial year, with the recruitment company expecting market conditions to remain broadly stable in the near term. The group also reported further cost reductions under its Momentum restructuring programme.

    For the three months ended 30 September 2026, net fees declined 5% on an actual basis, partly reflecting country disposals completed earlier in the year. The rate of decline moderated during the quarter, with September net fees falling 2%.

    Temporary and contracting recruitment continued to outperform permanent placements. Net fees from temporary and contracting operations decreased 1% on a like-for-like basis, with volumes remaining sequentially stable. Permanent recruitment net fees fell 7%, reflecting a 12% reduction in placement volumes.

    Regional performance varied across the group’s markets. Germany recorded a 6% decline in net fees, while the United Kingdom and Ireland reported a 5% reduction. Australia and New Zealand experienced a 3% decrease, while the Rest of World division recorded flat net fees, supported by growth in the Americas and Asia.

    Chief executive Mark Dearnley attributed the moderation in the group’s net fee decline to growth in temporary and contracting recruitment across several countries. He also reported a return to growth in permanent placement activity in North America.

    Consultant net fee productivity increased 8% during the quarter, marking the twelfth consecutive quarter of improvement on a seasonally adjusted basis. Productivity rose 11% in Germany and 10% in the UK and Ireland.

    Hays continued implementing its Momentum restructuring strategy, which targets approximately £50 million in annual structural cost savings during the current financial year.

    The company achieved around £10 million of additional annualised savings during the first quarter, bringing cumulative structural cost savings to approximately £125 million per annum since the beginning of FY2024.

    The group’s net debt position stood at approximately £45 million at 30 September 2026, compared with net cash of £20.1 million at 30 June 2026. Hays attributed the change to seasonal cash flow movements and share purchases associated with its all-colleague share award.

    Looking ahead, Hays expects recruitment market conditions to remain broadly stable in the near term, with temporary and contracting activity continuing to demonstrate greater resilience than permanent hiring.

    The company also said it does not anticipate any material impact from differences in working days during the second quarter.

    About Hays plc

    Hays plc is a global specialist recruitment company providing permanent, temporary and contracting recruitment services across multiple industries and professional sectors.

    The group operates internationally, connecting employers with qualified professionals through its recruitment network. Its activities cover major markets including Germany, the United Kingdom, Ireland, Australia, New Zealand and other territories across Europe, the Americas and Asia.

  • KEFI Gold and Copper Resumes Tulu Kapi Development Following Fatal Incident and Safety Review

    KEFI Gold and Copper Resumes Tulu Kapi Development Following Fatal Incident and Safety Review

    KEFI Gold and Copper (LSE:KEFI) has resumed development activities at its Tulu Kapi Gold Project in Ethiopia following a suspension associated with the fatal Genji Incident. The decision follows safety reviews and consultations with local communities and government authorities at multiple levels.

    The company has outlined a phased approach to restarting work, beginning with electricity connections and access road development. The next stage will involve community resettlement, followed by construction activities within the mining licence area, including security infrastructure, bulk earthworks and accommodation facilities for workers.

    KEFI said the revised development programme incorporates findings from the reviews conducted after the incident. The company is also prioritising the use of experienced local contractors as part of its approach to sourcing labour and services within Ethiopia.

    According to KEFI, project lenders remain supportive as the company updates its development schedule and associated funding drawdown arrangements to reflect the revised sequence of activities.

    The company also reported continued engagement with Ethiopian stakeholders, including government representatives and local communities. Management reiterated its commitment to workplace safety, environmental and social standards, and community participation as development progresses.

    KEFI has invested more than US$150 million in Tulu Kapi to date. Once operational, the mine is expected to provide direct employment for approximately 1,000 local workers.

    The project also includes plans for infrastructure improvements, including roads and electricity connections, alongside education and healthcare facilities. KEFI expects the development to create opportunities for local businesses supplying goods and services to the mining operation.

    The resumption of activities marks the next stage in the company’s development programme at Tulu Kapi, with initial work focused on infrastructure and community arrangements before construction progresses within the mining licence area.

    About KEFI Gold and Copper

    KEFI Gold and Copper is a mineral exploration and development company focused on the Arabian-Nubian Shield, with projects in Ethiopia and Saudi Arabia.

    Its principal development asset is the Tulu Kapi Gold Project in Ethiopia, where the company is working towards establishing a producing gold mine. KEFI’s development plans include local employment, infrastructure investment and community engagement, alongside environmental and social management measures.

  • ActiveOps Reports 21% First-Half Revenue Growth but Expects FY28 Results Below Forecasts

    ActiveOps Reports 21% First-Half Revenue Growth but Expects FY28 Results Below Forecasts

    ActiveOps (LSE:AOM) reported a 21% increase in revenue to £25.3 million for the first half of its 2027 financial year, alongside growth in annual recurring revenue (ARR) and adjusted EBITDA. However, the software company expects revenue and adjusted EBITDA for FY28 to fall significantly below current market forecasts following the planned departure of a major customer and lower levels of new business activity.

    For the six months ended 30 September 2026, organic Software as a Service (SaaS) revenue increased 19%, while adjusted EBITDA recorded double-digit growth. The company reported increased sales across Canada, Africa and the Asia-Pacific region, with cash balances rising to £19.6 million and ARR reaching £42.2 million.

    Despite the overall revenue increase, ActiveOps reported lower underlying revenue from training and implementation services, reflecting fewer new customer contracts and implementations compared with the corresponding period last year.

    The company confirmed that trading remains broadly in line with market expectations for FY27 and maintained its existing full-year guidance.

    However, ActiveOps disclosed that a major customer intends not to renew a contract representing £3.8 million in annual recurring revenue when it expires in March 2027. The anticipated contract loss, combined with reduced new business activity, is expected to result in FY28 revenue and adjusted EBITDA being significantly below current forecasts.

    The Board nevertheless intends to maintain investment in growth initiatives, supported by the company’s cash generation and balance sheet position. ActiveOps also identified increasing customer interest in software capable of measuring productivity improvements associated with artificial intelligence.

    The company continues to focus on generating additional revenue from existing enterprise customers, supported by its net revenue retention levels and recent acquisitions. Management expects these activities to contribute to its medium-term development plans.

    ActiveOps said the expected loss of the major customer contract has not changed its assessment of the longer-term international market opportunities for its Decision Intelligence products.

    The company is scheduled to publish its detailed interim financial results for the six months ended 30 September 2026 on 24 November 2026.

    About ActiveOps plc

    ActiveOps plc is a UK-based Software as a Service provider specialising in Decision Intelligence technology for service operations. Its software is used by organisations in banking, insurance, healthcare administration and business process outsourcing to manage workloads, allocate resources and monitor operational productivity.

    The company’s AI-enabled platform draws on more than two decades of operational data and is designed to help enterprise customers manage backlogs, improve processing times and assess productivity improvements. ActiveOps employs approximately 290 people across offices in Europe, North America, Asia-Pacific and Africa.

  • Afentra Revises Angola Drilling Programme as Impala-2 First Oil Targeted for January 2027

    Afentra Revises Angola Drilling Programme as Impala-2 First Oil Targeted for January 2027

    Afentra (LSE:AET) has revised its drilling programme at Block 3/05 offshore Angola, prioritising development of the Impala-2 well ahead of further work at the Pacassa SW discovery. The company now expects first oil from Impala-2 in January 2027, with initial gross production estimated at approximately 4,000 barrels per day.

    Under the revised programme, the Borr Grid drilling rig will move directly to Impala-2, with joint venture partners providing direct funding for the development well. The project will operate under a reduced cost cap of $60 million, an arrangement designed to limit Afentra’s exposure to cost overruns while allowing the company to benefit from early production revenues and the full capital expenditure uplift.

    Following completion of Impala-2, the rig is scheduled to return to the Pacassa SW discovery to undertake sidetrack drilling and well completion activities. First oil from Pacassa SW is expected during the first quarter of 2027, using existing production infrastructure.

    Afentra also anticipates revisions to resource estimates associated with both Impala and Pacassa SW as development work progresses. According to the company, Pacassa SW could potentially contribute approximately 70 million barrels of additional resources.

    The revised drilling sequence places Impala-2 ahead of Pacassa SW in the development schedule, with both projects targeting initial production during the first quarter of 2027. The company expects the developments to contribute to production volumes and cash flow as the wells are brought online.

    Afentra’s activities form part of its ongoing redevelopment programme in Angola, where the company is focused on increasing production from existing assets and progressing additional development opportunities within its portfolio.

    About Afentra plc

    Afentra plc is an upstream oil and gas company focused on production and development assets in Africa. The company holds interests in offshore and onshore oil and gas blocks in Angola, including producing Block 3/05 and additional exploration and development acreage in the Lower Congo and Kwanza basins. Its strategy includes acquiring and redeveloping existing energy assets in partnership with international oil companies and host governments.

  • Thruvision Maintains £8 Million FY27 Revenue Guidance as Order Backlog Reaches £2.6 Million

    Thruvision Maintains £8 Million FY27 Revenue Guidance as Order Backlog Reaches £2.6 Million

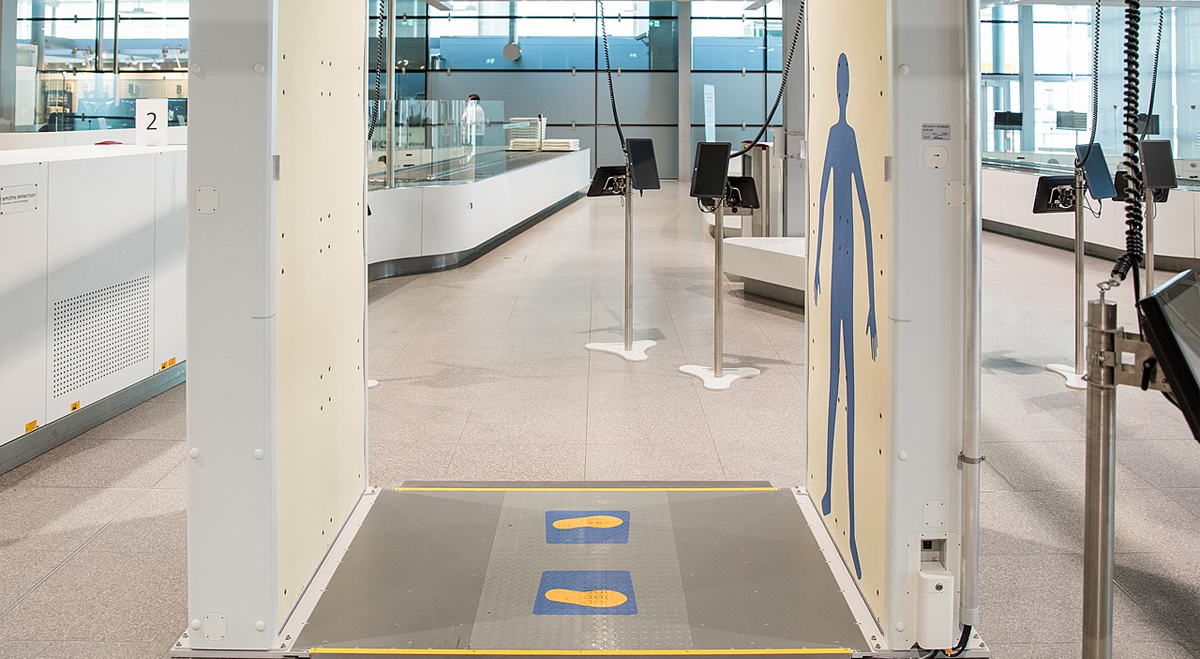
    Thruvision Group (LSE:THRU) reported first-half revenue of £2.6 million for the 2027 financial year, unchanged from the comparable period and in line with expectations, while its order backlog increased to £2.6 million. The security technology company maintained its full-year revenue guidance of £8 million, supported by existing orders and contracts scheduled for delivery during the second half.

    The company reported that its partner network accounted for almost 60% of first-half sales, reflecting an increased contribution from its distribution channels. Thruvision has expanded its network of value-added resellers in the UK and Benelux region and recruited additional sales personnel in the United States and UK.

    During the period, Thruvision secured further retail distribution agreements in Europe and added its first Canadian government customer. The company also reported a contract valued at more than £3 million to deploy its security screening systems across multiple airports in South-East Asia, with deployment planned for the second half of FY27.

    The airport agreement represents a significant component of the company’s reported contract activity and contributes to its order pipeline for the remainder of the financial year.

    Thruvision identified public space protection and transport hub security as areas of increasing demand for its technology. The company said its contract activity and distribution network expansion have improved revenue visibility, with management maintaining its expectations for continued growth into FY28.

    The company’s full-year revenue forecast remains unchanged at £8 million, compared with the £2.6 million recorded in the first half.

    About Thruvision Group plc

    Thruvision Group plc develops and manufactures walk-through security screening technology for government and commercial customers in more than 30 countries. Its AI-enabled systems are designed to detect concealed metallic and non-metallic objects in real time, including in locations with high pedestrian traffic. The company maintains offices and manufacturing operations in the UK and United States.

  • Citi Data Shows US Luxury Spending Declined 5% in Q3, Ending First-Half Growth

    Citi Data Shows US Luxury Spending Declined 5% in Q3, Ending First-Half Growth

    U.S. consumer spending on luxury brands declined 5% year over year in the third quarter of 2026, reversing the increases recorded during the first six months of the year, according to credit card data analysed by Citi.

    The bank reported a 6% annual decline in September, following reductions of 4% in July and August. September represented the largest monthly decrease of the quarter.

    The third-quarter contraction followed spending growth of 5% in the first quarter and 3% in the second, making it the first quarter of 2026 to record a year-over-year decline.

    Citi said the latest figures reflected a combination of continued geopolitical uncertainty and a more difficult comparison with spending levels a year earlier.

    The two-year stacked spending measure also declined, moving to negative 6% in September from negative 5% in August.

    Jewellery and Watches Record Larger Declines

    Spending trends varied across luxury product categories during September, according to Citi’s transaction analysis.

    Leather goods and ready-to-wear apparel showed sequential improvements, while jewellery and watch purchases declined more substantially.

    The bank noted that comparisons with tariff-related purchases made a year earlier contributed to the reduction in jewellery and watch spending.

    Average spending per transaction decreased by a low-single-digit percentage on an annual basis.

    The number of customers making purchases also remained below the previous year’s level, falling 5%, although the customer growth measure improved compared with earlier readings.

    These figures indicate that both transaction values and customer activity contributed to the annual reduction in spending during September.

    Consumer Surveys Point to Softer Sentiment

    Citi’s findings coincided with weaker consumer confidence readings in the United States.

    September surveys conducted by the Conference Board and the University of Michigan indicated less favourable views of business conditions and employment prospects, alongside continuing concerns about inflation.

    The bank said the latest transaction figures and commentary from luxury businesses suggest that U.S. spending patterns may be returning towards more normalised levels.

    However, Citi expects consumers in higher-income groups to remain comparatively resilient, with gains in equity market wealth continuing to support their financial position.

    The bank’s observations come ahead of the next round of corporate earnings announcements, when luxury companies are expected to provide updated information on regional demand.

    Citi Identifies Luxury Groups With Greater US Market Exposure

    Citi highlighted differences in the extent to which publicly traded luxury companies depend on U.S. consumers.

    Tapestry (NYSE:TPR), Capri Holdings (NYSE:CPRI), Watches of Switzerland (LSE:WOSG), Birkenstock (NYSE:BIRK) and EssilorLuxottica (EU:EL) were identified among the companies with the greatest U.S. exposure.

    Companies with comparatively lower exposure included Moncler (BIT:MONC), Prada Group (USOTC:PRDSY), Swatch Group (USOTC:SWGNF), Hermes (LSE:RMS) and Burberry (LSE:BRBY).

    The geographic distribution of sales provides context for assessing how changes in U.S. luxury spending may affect individual companies.

    Citi’s analysis uses selected credit card transaction records from a panel exceeding 10 million U.S. cardholders, meaning the results reflect the spending patterns of that sample rather than the entire luxury market.

    The findings show that U.S. luxury spending moved into negative annual growth during the third quarter, with differences across product categories and customer spending measures ahead of the upcoming earnings season.

  • AI and Technology Expected to Drive Two-Thirds of S&P 500 Earnings Growth in Q3

    AI and Technology Expected to Drive Two-Thirds of S&P 500 Earnings Growth in Q3

    Artificial intelligence-related companies are expected to account for much of the anticipated increase in U.S. corporate earnings during the third quarter of 2026, with analysts forecasting overall S&P 500 profit growth of approximately 31% compared with a year earlier.

    According to LSEG earnings and equity research head Tajinder Dhillon, around two-thirds of the projected increase is expected to come from the technology sector and AI-related companies, including Alphabet (NASDAQ:GOOG), Amazon.com (NASDAQ:AMZN) and Meta Platforms (NASDAQ:META).

    The earnings outlook follows a period of gains in technology shares that helped lift the S&P 500 to a record high this week.

    Investors are preparing for the quarterly reporting season, which is expected to begin next week with financial results from JPMorgan Chase (NYSE:JPM), Goldman Sachs (NYSE:GS) and other major banks.

    Sector Forecasts Show Differences in Earnings Growth

    Technology and AI-related businesses are expected to account for the largest share of third-quarter earnings expansion, although energy companies are also forecast to report substantial increases.

    Wells Fargo Investment Institute’s Sameer Samana estimates that technology and AI could contribute between 70% and 80% of overall earnings growth.

    Energy sector profits are projected to increase approximately 115% year over year, following a roughly 30% rise in U.S. oil prices during the third quarter amid the ongoing U.S.-Israeli war with Iran.

    Other sectors are expected to report considerably lower growth rates. Consumer staples and real estate are among the industries with the smallest projected increases in earnings compared with the same period last year.

    The sector forecasts suggest that aggregate S&P 500 earnings growth will depend heavily on the performance of companies associated with AI investment and energy markets.

    Third-Quarter Growth Forecast Below Previous Quarter

    The expected 31% increase in third-quarter earnings would represent a moderation from the second quarter, when S&P 500 profits rose nearly 54% year over year, according to LSEG.

    That was the highest reported growth rate since 2021.

    Excluding mark-to-market investment gains recorded by Alphabet and Amazon.com, second-quarter earnings increased approximately 35%, also representing the highest growth rate since 2021.

    Market strategists expect many companies to exceed analysts’ earnings estimates during the third-quarter reporting period, although questions remain about the sustainability of the current growth cycle.

    Anthony Saglimbene, chief market strategist at Ameriprise Financial, said continued investment in AI infrastructure has raised expectations for corporate performance.

    He noted that successive quarters of capital spending increase the financial performance required to sustain investor expectations, particularly among companies benefiting from AI development.

    Semiconductor Profit Growth Expected to Moderate

    Earnings among U.S. semiconductor manufacturers are forecast to increase approximately 136% compared with the third quarter of 2025, according to LSEG data.

    The projected growth rate is below the roughly 158% increase recorded in the second quarter.

    Nick Raich, chief executive of Earnings Scout, said upward revisions to earnings forecasts are beginning to slow, although AI infrastructure investment continues at a substantial pace.

    Raich cited recent results from Micron Technology (NASDAQ:MU) as an indication that companies supplying AI-related infrastructure continue to receive orders and investment commitments.

    Micron last month issued a quarterly revenue forecast above market expectations and reported that customer commitments under long-term supply agreements had reached $32 billion.

    Google also entered into a substantial power agreement with Constellation Energy this week, adding to developments associated with infrastructure spending.

    Rising Borrowing Costs Remain Under Review

    Alongside AI-related spending, investors are expected to focus on the effects of higher interest rates on corporate earnings.

    U.S. bond yields have increased amid inflation expectations, rising oil prices and concerns about public debt in France and other countries.

    Samana identified utilities and other companies that rely heavily on borrowing as potentially exposed to higher financing costs.

    The third-quarter reporting season will provide updated information on whether AI-related companies can maintain their recent earnings growth rates and how higher interest expenses are affecting other sectors.

    While the overall earnings outlook remains for substantial year-over-year growth, LSEG estimates indicate a slower pace than in the second quarter and continued concentration of profit increases among technology and AI-related businesses.

  • UBS Projects Gold at $5,400 by September 2027 Despite Near-Term Risk of $4,000 Retest

    UBS Projects Gold at $5,400 by September 2027 Despite Near-Term Risk of $4,000 Retest

    UBS has maintained its forecast for gold to reach $5,400 per ounce by September 2027, while warning that higher U.S. real interest rates and a firm dollar could lead to a short-term decline towards $4,000.

    UBS strategist Giovanni Staunovo said the current interest rate environment has increased the cost of holding non-yielding assets such as gold.

    Spot prices stood at $4,191 per ounce on Friday at the time of the original report, with the bank identifying $4,000 as a potential support level where longer-term buyers could enter the market.

    Staunovo attributed recent selling pressure partly to speculative investors reducing net long positions in gold futures and options.

    In contrast, investment flows into gold-backed ETFs have continued in recent weeks, with holdings remaining relatively stable despite movements in bond yields.

    Structural Demand Remains a Factor in UBS Outlook

    According to UBS, gold’s response to rising real yields has been less pronounced than in previous market cycles.

    Staunovo suggested that continued demand from central banks and other longer-term buyers has partly offset the effects of higher interest rates.

    The bank identified several factors supporting its gold outlook, including reserve diversification by central banks, concerns about public debt and borrowing costs, expectations for eventual dollar depreciation and demand from China.

    UBS also expects seasonal purchases in India to contribute to demand, particularly if prices decline during the country’s festival period.

    Preliminary September data showed China purchased 23 metric tons of gold, while Uzbekistan acquired 7 metric tons.

    The bank expects total annual central bank purchases to range between 750 and 1,000 metric tons.

    Interest Rate Expectations Differ From Market Pricing

    UBS noted that financial markets are currently anticipating slightly more than 75 basis points of Federal Reserve rate increases through 2027.

    The bank’s own forecast differs, calling for one further rate increase in 2026 followed by two quarter-percentage-point reductions in 2027.

    Staunovo expects changes in market expectations surrounding monetary tightening to influence gold prices, particularly if real interest rates begin to decline.

    UBS forecasts gold reaching $4,600 per ounce in December 2026, followed by $5,000 in March 2027 and $5,200 in June. Its September 2027 target stands at $5,400 per ounce.

    The projections reflect the bank’s expectation that demand from central banks and other investors will continue to influence the gold market even if higher interest rates create near-term price pressure.

    UBS Identifies $4,000 as Potential Buying Level

    Staunovo expects structural investment demand to provide support if gold prices move back towards $4,000 per ounce.

    The strategist considers declines towards that level potential opportunities to increase gold holdings, consistent with UBS’s longer-term price forecasts.

    He also recommends that investors interested in real assets consider allocating a mid-single-digit percentage of their portfolios to gold.

    The bank’s outlook therefore distinguishes between the possibility of further short-term price declines and its expectations for higher gold prices during 2027, with interest rates, currency movements and central bank purchases remaining principal factors in its projections.