Category: Market News

  • Jefferies Downgrades Watches of Switzerland as Valuation Upside Narrows (WOSG)

    Jefferies Downgrades Watches of Switzerland as Valuation Upside Narrows (WOSG)

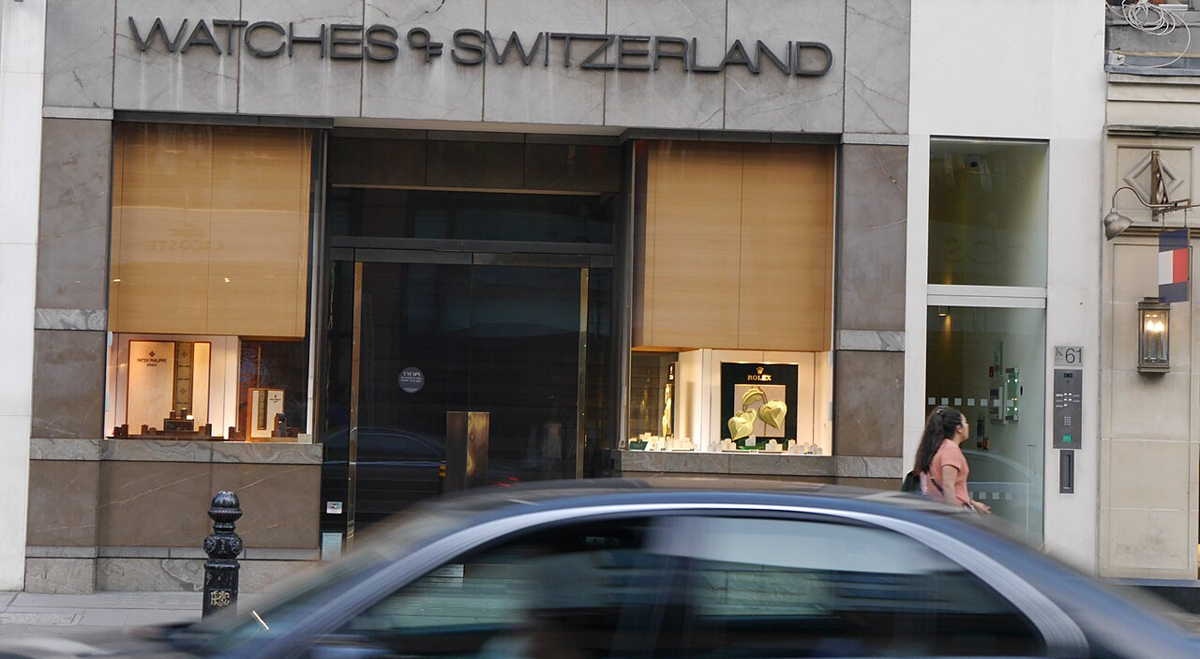
    Shares of Watches of Switzerland Group Plc (LSE) dropped more than 3% on Friday after Jefferies lowered its recommendation on the luxury watch retailer to “hold” from “buy,” arguing that the scope for further valuation expansion has become more limited. At the same time, the broker increased its price target to 740 pence from 440 pence.

    “Our downgrade to Hold reflects a reducing runway for valuation expansion (with today’s 13.1x cal 2027 PE comparing to a post COVID range of 7x to 14x) at a time when the US outlook will likely provide a reducing source of positive surprises,” Jefferies said.

    North America Remains Strong, but Valuation Appeal Weakens

    Jefferies expects the company’s full-year results, due on 14 July, to “confirm North American demand buoyancy,” although it believes “reducing valuation attractions and inflation tailwinds” justify a more cautious stance.

    The broker said its revised target price reflects “the dichotomy of UK maturity (on c.10x) and US potential (on c.16x), the latter sense-checked by the correlation to volatile equity markets.”

    Jefferies has also adopted a sum-of-the-parts valuation approach. Its previous target was based on a calendar 2026 price-to-earnings multiple of 10.3x, whereas the updated valuation rolls forward to 2027 earnings using a group multiple of 13.1x.

    The revised methodology applies a 10x multiple to the UK business, which the broker said is “aligned with the average for FTSE250 retailers,” while assigning a 16x multiple to the U.S. operations.

    U.S. Growth Expected to Moderate

    Commenting on the American business, Jefferies described it as delivering “an impressive US re-acceleration, but an unclear outlook.” The broker highlighted fiscal 2025/26 U.S. revenue growth excluding foreign exchange effects of 22.7% before the impact of the 53rd week, supported by approximately 20% growth at Coin and a 2.4% contribution from the four-month consolidation of D&D.

    Jefferies believes current market forecasts for U.S. revenue growth of around 14% in fiscal 2026/27 and 8.5% in fiscal 2027/28 “seems fair rather than too conservative,” compared with its own projections of 14.5% and 8%.

    The broker also noted that “now started lapping the heightened US price hikes pushed since Liberation Day by major brands,” with cumulative price increases of 12.6% across Patek Philippe, Rolex, Cartier and Omega. It added that pricing support “has started moderating since Sep 2025,” highlighting that Patek Philippe reduced prices by a high-single-digit percentage in February.

    UK Outlook Remains Challenging

    Turning to the UK market, Jefferies said “despite extensive industry lobbying, no evidence has emerged of a potential reintroduction of duty-free shopping,” adding that recent political developments suggest such an outcome “is a very remote one within this Parliament.”

    As a result, the broker believes the company remains exposed to “a mixed domestic demand outlook,” with the UK business expected to account for around 45% of group revenue by fiscal 2027/28, leaving it “vulnerable to a more pressured consumer.”

    Jefferies forecasts revenue of £1.80 billion in fiscal 2025/26, rising to £1.97 billion in fiscal 2026/27 and £2.10 billion in fiscal 2027/28, compared with £1.65 billion in fiscal 2024/25. It expects earnings per share to increase from 41.6 pence in fiscal 2024/25 to 43.0 pence, 53.6 pence and 58.3 pence over the following three financial years.

    According to the broker, risks to its valuation include lower product allocations from luxury watch brands, increased competition for acquisitions, the possibility of new U.S. tariffs and a shift in consumer spending away from the hard luxury segment.

  • FTSE 100 Rises as Diplomatic Hopes Lift Sentiment and Apollo Leads Race for easyJet (EZJ)

    FTSE 100 Rises as Diplomatic Hopes Lift Sentiment and Apollo Leads Race for easyJet (EZJ)

    UK equities traded higher on Friday as renewed diplomatic efforts between the United States and Iran helped calm concerns over tensions in the Middle East. Investors also continued to monitor the takeover battle for easyJet (LSE:EZJ), after Apollo Global (NYSE:APO) emerged with a higher £5.7 billion proposal.

    The FTSE 100 gained 0.23% by 03:25 ET (07:25 GMT). Elsewhere in Europe, Germany’s DAX advanced 0.24%, while France’s CAC 40 rose 0.21%. Sterling strengthened 0.14% against the U.S. dollar to trade at $1.3426.

    U.S. President Donald Trump said Washington would respond to Iranian-linked attacks on commercial shipping in the Strait of Hormuz while reiterating that Iran “can never possess a nuclear weapon.”

    Although the latest U.S. military action drew domestic criticism and heightened regional tensions, officials stressed that diplomatic engagement with Tehran remained a priority.

    Regional mediators, including Qatar, Saudi Arabia, Pakistan, Turkey and Egypt, subsequently intensified efforts to revive U.S.-Iran nuclear negotiations. At the same time, the United States and Israel reaffirmed their close security partnership.

    Iran denied allegations relating to activity in the Strait of Hormuz and maintained that its nuclear programme is intended solely for peaceful purposes, highlighting the continuing divide between military developments and diplomatic negotiations.

    The country also concluded several days of state funeral ceremonies for former Supreme Leader Ayatollah Ali Khamenei, whose burial at the Imam Reza shrine in Mashhad brought the official mourning period to a close amid ongoing regional uncertainty.

    In UK politics, Andy Burnham secured 322 nominations from Labour MPs on Thursday, leaving him just one nomination short of the 323 required to prevent a challenger from entering the leadership contest.

    The former Greater Manchester mayor is widely expected to be confirmed as Labour leader next week before taking office as prime minister on 20 July.

    Commodity markets moved lower, with Brent crude falling 0.84% to $75.66 per barrel and WTI crude down 0.78% at $71.52. Gold futures declined 0.44% to $4,122.40 an ounce, while spot gold slipped 0.25% to $4,113.65.

    UK Market Round-up

    Apollo Global overtook Castlelake in the contest for easyJet (LSE:EZJ), agreeing in principle to a £5.7 billion takeover proposal that values the airline at £7.15 per share.

    MJ Gleeson (LSE:GLE) said full-year profit is expected to meet market expectations but cautioned that geopolitical uncertainty and potential changes to UK government policy could affect its outlook for fiscal 2026.

    Vodafone (LSE:VOD) remained in focus after UAE telecoms group e& agreed to sell its 16.3% holding in the company to Vega, the investment vehicle backed by Xavier Niel, in a transaction worth $5.95 billion at a 13% premium.

    Hays (LSE:HAS) said it expects fiscal 2026 operating profit to come in at the upper end of market forecasts, as cost-saving initiatives continue to offset subdued recruitment activity.

  • St. James’s Place Shares Slide After Report of Potential Adviser Departure (STJ)

    St. James’s Place Shares Slide After Report of Potential Adviser Departure (STJ)

    St. James’s Place Plc (LSE:STJ) shares fell more than 6% in London trading on Friday following reports that Sovereign Wealth, one of the company’s largest partner firms, is in discussions about joining Swedish wealth management group Söderberg & Partners.

    According to the report, Sovereign Wealth oversees approximately £3 billion in assets under management and has a network of more than 50 advisers, making it one of St. James’s Place’s most significant partner firms.

    Quarterly Net Inflows Ease

    The wealth manager previously reported net inflows of £1.53 billion for the quarter ended 31 March 2026, compared with £1.69 billion during the same period a year earlier.

    The company said the lower inflows reflected a period of heightened market volatility and ongoing geopolitical uncertainty, as outlined in its results published on 29 April 2026.

  • RBC Cuts Wizz Air to “Underperform” as Profit Recovery Expectations Face Scrutiny (WIZZ)

    RBC Cuts Wizz Air to “Underperform” as Profit Recovery Expectations Face Scrutiny (WIZZ)

    RBC Capital Markets has downgraded Wizz Air Holdings (LSE:WIZZ) to “Underperform” from “Sector Perform”, arguing that the low-cost airline’s latest earnings were boosted by non-recurring factors and that the market may be too optimistic about the speed of its earnings recovery.

    The broker maintained its 900 pence price target, which implies roughly 20% downside from current trading levels. RBC added that its forecasts for fiscal 2027 and fiscal 2028 remain below consensus estimates, even after factoring in lower fuel costs.

    Lower Fuel Costs Unlikely to Drive Earnings Upgrades

    According to RBC, the recent decline in jet fuel prices is unlikely to trigger meaningful near-term earnings upgrades. The broker believes that weaker unit revenues, rising non-fuel operating costs and continued capacity expansion are likely to offset much of the benefit from cheaper fuel.

    The analysts also cautioned that revenue per available seat kilometre (RASK) could remain under pressure beyond the first quarter as airlines continue adding capacity across Central and Eastern Europe.

    One-Off Gains Boosted Fiscal 2026 Results

    RBC argued that the quality of Wizz Air’s fiscal 2026 earnings was weaker than headline results indicated. The broker noted that earnings benefited from approximately €542 million of other income, primarily linked to compensation payments and gains from sale-and-leaseback transactions, as well as €102 million in foreign exchange gains.

    The analysts expect these sources of income to diminish over the coming years, creating additional challenges for earnings growth, even as a reduction in grounded aircraft is expected to improve operational performance.

    Valuation Reflects Optimistic Recovery Expectations

    RBC also highlighted management’s increasing preference for aircraft ownership instead of sale-and-leaseback financing, citing the long-term cost advantages of owning aircraft outright.

    Although the broker continues to forecast earnings growth through fiscal 2030, it expects EBIT margins to remain around 6% to 7%, below the double-digit margins Wizz Air achieved before the pandemic.

    The analysts concluded that the current valuation implies investors are expecting a much sharper “hockey stick” recovery than RBC anticipates, leaving the shares exposed if future earnings fail to meet market expectations.

  • EnQuest Moves Closer to Completing Major Malaysian Acquisition (ENQ)

    EnQuest Moves Closer to Completing Major Malaysian Acquisition (ENQ)

    EnQuest PLC (LSE:ENQ) has received important regulatory approvals to advance its planned acquisition of a portfolio of Malaysian oil and gas assets. The company confirmed that existing production sharing contract (PSC) partners have waived their pre-emption rights over one of the licence packages, removing a key condition for the transaction.

    The proposed acquisition includes operated interests in the Balingian, SK8 and D35-D21-J4 production sharing contracts, together with a non-operated interest in the PM6-12 licence, subject to the remaining customary completion requirements.

    Reverse Takeover Process Continues

    The acquisition is structured across three separate transaction packages and is currently expected to complete on 31 December 2026.

    Given the scale of the deal, it qualifies as a reverse takeover under UK listing rules. EnQuest said it will publish a combined shareholder circular and prospectus in due course, allowing investors to review the transaction ahead of the required approvals. The acquisition would significantly expand the company’s presence in South East Asia and reshape its production portfolio.

    Financial Outlook Remains Mixed

    EnQuest’s investment outlook continues to reflect a combination of strengths and challenges. While the shares have maintained a strong upward trend, technical indicators suggest momentum is approaching overbought territory.

    Fundamentally, the company faces pressure from declining revenues, weaker earnings during 2025 and a relatively leveraged balance sheet. Valuation also remains demanding, with an exceptionally high price-to-earnings ratio only partly offset by the company’s dividend yield.

    More about EnQuest

    EnQuest PLC is an independent oil and gas company focused on acquiring, operating and extending the productive lives of mature energy assets in the UK North Sea and South East Asia.

    The company specialises in improving operational performance and extracting additional value from established fields through efficient asset management. Listed on the London Stock Exchange, EnQuest aims to support energy security while managing existing hydrocarbon resources as part of a broader transition towards a lower-carbon energy system.

  • Johnson Service Maintains Margin Guidance as Workwear Offsets Softer Hospitality Demand (JSG)

    Johnson Service Maintains Margin Guidance as Workwear Offsets Softer Hospitality Demand (JSG)

    Johnson Service Group (LSE:JSG) reported broadly unchanged first-half 2026 revenue of £258 million, with growth in its Workwear division largely offsetting weaker trading in the HORECA business as hospitality market conditions remained challenging. Overall organic revenue declined slightly, but the company said pricing discipline, operational improvements and careful management of labour and energy costs have supported continued margin expansion.

    Management remains on track to deliver an adjusted operating margin of at least 14% for the 2026 financial year.

    Share Buyback Progresses as Cash Generation Expected to Improve

    Johnson Service continues to execute its £55 million share buyback programme, having returned £17.3 million to shareholders so far. Although net debt has increased due to dividend payments, buybacks and capital expenditure, leverage remains towards the lower end of the company’s target range of 1.0x to 1.5x net debt to adjusted EBITDA.

    The group expects stronger cash generation during the second half of the year, supported by the seasonal recovery in HORECA demand. Management believes this will provide additional capacity to invest in the business, improve margins further and continue returning capital to shareholders.

    Outlook Remains Positive Despite Some Risks

    Johnson Service’s investment outlook is supported by improving profitability and solid operating cash flow generation.

    These strengths are balanced by higher leverage and fluctuations in free cash flow. Technical indicators continue to point to a positive trend, although overbought signals suggest the shares could face some short-term pressure. Valuation appears reasonable, with a moderate dividend yield offering some support, although it is not viewed as a major catalyst for further gains.

    More about Johnson Service

    Johnson Service Group is a leading provider of textile rental and laundry services across the UK and the Republic of Ireland. The company serves customers in the Workwear and HORECA sectors, supplying textile solutions to industrial, commercial and hospitality businesses.

    Its business model is built around recurring, cash-generative revenues supported by a modern operational network and disciplined cost management. Johnson Service aims to maintain net debt between 1.0x and 1.5x adjusted EBITDA while balancing investment in operational efficiency, selective acquisitions, progressive dividends and share buybacks to enhance shareholder returns.

  • GlobalData Unveils £30 Million Tender Offer to Return Capital to Shareholders (DATA)

    GlobalData Unveils £30 Million Tender Offer to Return Capital to Shareholders (DATA)

    GlobalData Plc (LSE:DATA) has announced plans to return up to £30 million to shareholders through a tender offer that will allow the company to repurchase up to 35,294,117 ordinary shares at 85 pence each. The offer price represents a 16% premium to the company’s latest closing share price.

    The tender offer will be open to eligible shareholders from 10 July until 10 August 2026. Each qualifying shareholder will receive a guaranteed entitlement equivalent to approximately 4.73% of their existing holding, with all shares acquired through the offer set to be cancelled, subject to shareholder approval at a general meeting scheduled for 6 August.

    Board Supports Capital Return Plan

    GlobalData’s board, which together owns around 61% of the company’s issued share capital, has unanimously recommended that shareholders vote in favour of the resolution required to implement the tender offer.

    However, the board has not advised shareholders whether they should participate in the tender itself, leaving that decision to individual investors. Management said the initiative forms part of the company’s broader capital allocation strategy, enabling surplus cash to be returned while maintaining financial flexibility and allowing shareholders to choose between receiving liquidity at a premium or retaining their investment.

    Outlook Balances Growth with Financial Risks

    GlobalData’s investment outlook continues to be supported by consistent business growth and dependable cash generation.

    These strengths are partly offset by a more leveraged balance sheet and lower shareholder equity. Technical indicators point to strong recent share price momentum, although overbought conditions and a share price that remains below the 200-day moving average suggest a more balanced near-term outlook. Valuation appears reasonable, with the stock trading on a price-to-earnings ratio in the mid-20s and offering a modest dividend yield.

    More about GlobalData

    GlobalData Plc is a London-listed provider of data, analytics and technology solutions serving corporate and financial market clients. The company delivers market intelligence and decision-support tools across multiple industries, helping customers identify trends, opportunities and competitive insights.

    Its business combines proprietary datasets with technology platforms to provide sector-specific research and analytics. Alongside its focus on operational growth, GlobalData seeks to enhance shareholder returns through disciplined capital allocation and initiatives such as share buybacks and capital return programmes.

  • LPA Group Secures Nearly £1 Million in UK Rail Aftercare Orders (LPA)

    LPA Group Secures Nearly £1 Million in UK Rail Aftercare Orders (LPA)

    LPA Group plc (LSE:LPA) has been awarded a series of UK rail aftercare contracts with a combined value of approximately £989,000, further strengthening its position in the rolling stock maintenance market. The contracts cover the supply of components together with jumper and shore supply systems, with deliveries scheduled to begin in October 2026.

    The largest awards were received from a major UK train operating company and a multinational train manufacturer, complemented by several smaller contracts.

    Contracts Strengthen Rail Maintenance Business

    The latest contract wins reinforce LPA’s strategy of expanding its presence in the rail refurbishment, overhaul and aftercare sector. By supplying equipment that supports long-term fleet maintenance and operational reliability, the company continues to strengthen relationships with customers across the UK rail industry.

    LPA specialises in engineering electronic and electro-mechanical systems for demanding applications where reliability, performance and lower lifetime operating costs are key priorities.

    Financial Outlook Remains Mixed

    Despite the new business wins, LPA’s investment outlook continues to be affected by weaker underlying financial performance. The company reported losses during 2024 and 2025, while operating and free cash flow turned sharply negative in 2025, offsetting the benefits of solid revenue growth.

    Its balance sheet remains relatively strong, with low leverage providing financial resilience. Technical indicators are more encouraging, with the shares trading above key moving averages and a positive MACD signalling improving momentum. However, an elevated RSI suggests the stock may be approaching overbought conditions. Valuation remains constrained as the company is loss-making and does not currently offer a dividend yield.

    More about LPA Group plc

    LPA Group plc is a UK engineering company that designs and manufactures electronic and electro-mechanical systems for the transport, defence, infrastructure and industrial sectors. Operating from four UK manufacturing sites, the group produces power supplies, LED lighting, electro-mechanical systems and value-added distribution solutions.

    With more than 160 years of engineering experience, LPA focuses on delivering high-reliability products for safety-critical and demanding operating environments, serving customers across the rail, aviation and wider industrial markets.

  • Impax Asset Management Grows Assets Under Management as Investment Performance Supports Quarter (IPX)

    Impax Asset Management Grows Assets Under Management as Investment Performance Supports Quarter (IPX)

    Impax Asset Management (LSE:IPX) reported that assets under discretionary and advisory management increased by 4.4% during its third fiscal quarter, reaching £23.3 billion as of 30 June 2026. Growth was driven by strong investment performance across its thematic equity, systematic equity and fixed income strategies, all of which outperformed their respective benchmarks.

    Although the company recorded net outflows during the period, these were largely attributed to a one-off Exit Tender at Impax Environmental Markets plc. Management also highlighted improving client flows through its largest distribution partner and continued net inflows into its U.S. systematic equities funds.

    European Product Expansion Planned

    Impax intends to broaden its sustainable investment offering by launching its first UCITS systematic equities strategy in Europe later this year, responding to growing demand from investors in the region.

    At the end of the quarter, the firm’s assets under management comprised £20.3 billion in listed equities, £2.3 billion in fixed income strategies and £0.6 billion in private markets, reflecting continued expansion across its core investment capabilities despite the impact of isolated redemption activity.

    Outlook Supported by Strong Balance Sheet

    Impax’s investment outlook continues to benefit from a robust financial position, characterised by low leverage, healthy operating margins and a strong balance sheet.

    However, these strengths are offset by declining revenue and weaker free cash flow trends. Technical indicators also remain cautious, with the shares trading below key moving averages and a negative MACD signalling subdued market momentum. Valuation remains supportive, aided by a relatively low price-to-earnings ratio and an attractive dividend yield, while management continues to focus on cost discipline despite ongoing pressure from client outflows.

    More about Impax Asset Management

    Impax Asset Management Group plc is an AIM-listed specialist investment manager focused on opportunities arising from the transition to a more sustainable global economy. The company manages a range of thematic and systematic equity strategies alongside fixed income and private market investments for institutional and retail clients across the UK, Europe and the United States.

    Its investment approach is centred on companies positioned to benefit from long-term environmental and sustainability trends, including decarbonisation, resource efficiency and the transition to cleaner technologies. Impax continues to expand its product range, including UCITS strategies, as it seeks to strengthen its presence in key international markets.

  • LondonMetric and Schroder Improve Proposed All-Share Offer for Picton (LMP)

    LondonMetric and Schroder Improve Proposed All-Share Offer for Picton (LMP)

    LondonMetric Property (LSE:LMP) and Schroder Real Estate Investment Trust (LSE:SREI) have improved the financial terms of their non-binding all-share proposal to acquire Picton Property Income. The revised proposal increases the Schroder Real Estate Investment Trust exchange ratio to 0.894 shares for each Picton share, while the LondonMetric exchange ratio remains unchanged.

    Based on the updated terms, the offer values Picton at approximately £397 million, representing a 6.8% premium to its latest closing share price while reflecting an 8.5% discount to its EPRA Net Tangible Assets (NTA). Picton’s board has reiterated its support for the proposal and said it would be minded to recommend the transaction once due diligence and final documentation have been completed.

    Revised Terms Increase Shareholder Benefits

    According to Picton’s board, the amended proposal delivers stronger financial benefits for shareholders, including pro forma earnings accretion of 39.4% and an immediate 47.4% increase in dividend income.

    The revised exchange ratio follows Schroder Real Estate Investment Trust’s latest financial results, which showed a modest decline in net asset value per share. The consortium continues to conduct due diligence and seek lender approvals, with the proposal remaining subject to several pre-conditions. No firm offer has yet been made, and there is no certainty that a binding transaction will proceed.

    Outlook Supported by Income and Valuation

    LondonMetric’s investment outlook continues to benefit from an attractive valuation, supported by a relatively low price-to-earnings ratio and a strong dividend yield. The company’s latest trading update also pointed to resilient rental income and continued dividend growth.

    These strengths are balanced against several risk factors, including higher leverage and weaker free cash flow growth over the most recent financial year. Technical indicators remain broadly neutral to slightly negative.

    More about LondonMetric Property

    LondonMetric Property is a UK-listed real estate investment trust focused on generating long-term income through investments in logistics, distribution and other high-quality commercial property assets.

    Schroder Real Estate Investment Trust invests across a diversified portfolio of UK commercial real estate, while Picton Property Income is another listed UK property investment company focused on income-producing assets. The proposed all-share combination would bring together three established participants in the UK commercial property sector, creating a larger and more diversified real estate investment platform.