Category: Top Story

  • ITM Power Reports 68% Revenue Growth to £43.6 Million and Targets £50 Million–£60 Million in FY2027

    ITM Power Reports 68% Revenue Growth to £43.6 Million and Targets £50 Million–£60 Million in FY2027

    ITM Power plc (LSE:ITM) reported record revenue of £43.6 million for the financial year ended 2026, an increase of 68% year on year, alongside a reduction in its adjusted EBITDA loss to £20.2 million.

    The UK-based electrolyser manufacturer ended the year with cash of £215.6 million and a contract backlog valued at £144.0 million, which the company said now predominantly comprises profitable contracts.

    During the period, ITM secured £40.0 million in equity investment from Great British Energy and a £46.5 million UK government grant to support the development of a 1 gigawatt (GW) Chronos electrolyser manufacturing line.

    The company also expanded its activities through the launch of Hydropulse, its build-own-operate (BOO) hydrogen business, and progressed several industrial-scale hydrogen projects.

    For FY2027, ITM expects revenue of £50 million to £60 million, alongside a further reduction in adjusted EBITDA losses.

    Revenue Increases 68% as Adjusted EBITDA Loss Narrows

    ITM reported annual revenue of £43.6 million, representing a 68% increase compared with the previous financial year.

    The company recorded an adjusted EBITDA loss of £20.2 million, reflecting a reduction in losses as revenue increased and the composition of its contract portfolio changed.

    At the year-end, ITM held £215.6 million in cash.

    Its contract backlog stood at £144.0 million, with management reporting that the majority of contracted work is now expected to be profitable.

    The backlog comprises projects involving the supply of proton exchange membrane (PEM) electrolyser technology and associated hydrogen production infrastructure.

    ITM said its operational priorities remain focused on contract execution, manufacturing efficiency and managing expenditure as it expands production capacity.

    Great British Energy Investment and Government Grant Support Chronos Expansion

    ITM secured £40.0 million in equity investment from Great British Energy and a £46.5 million UK government grant to support its manufacturing expansion.

    The funding is intended to facilitate development of a new Chronos production line with planned annual electrolyser manufacturing capacity of 1 GW.

    Chronos forms part of ITM’s electrolyser technology portfolio, which is designed for large-scale hydrogen production applications.

    The proposed manufacturing expansion is intended to increase the company’s ability to supply equipment for industrial hydrogen projects.

    The investment programme will require continued capital expenditure as the company develops the additional capacity.

    ITM said it intends to maintain financial discipline while progressing the Chronos manufacturing programme.

    RWE Lingen Project Reaches 100 MW Milestone

    Following the financial year-end, ITM reported progress at its 100 megawatt (MW) hydrogen production project in Lingen, Germany, developed for RWE.

    The company described the facility as the world’s largest PEM electrolyser installation following its completion.

    A second 100 MW unit at the site is also progressing towards completion.

    The Lingen project is among ITM’s principal reference installations for industrial-scale hydrogen production.

    The company has also secured contracts and project selections involving energy companies including RWE and Uniper, alongside grid-balancing applications in Germany.

    These projects form part of ITM’s efforts to expand deployment of its electrolyser systems in the European industrial and energy sectors.

    Hydropulse Introduces Build-Own-Operate Hydrogen Model

    ITM launched Hydropulse during the financial year as a business focused on developing, owning and operating hydrogen production facilities.

    The model differs from ITM’s existing equipment supply activities by providing for direct ownership and operation of hydrogen assets, with the intention of generating revenue through hydrogen supply agreements.

    The company also introduced the 50 MW Alpha 50 hydrogen plant as part of its project development activities.

    Hydropulse is progressing a proposed 150 MW hydrogen project associated with a refinery, extending ITM’s activities into the direct supply of hydrogen to industrial customers.

    The development of these projects remains subject to their respective commercial arrangements, investment decisions and construction requirements.

    The BOO model is intended to provide an additional source of revenue alongside electrolyser equipment sales.

    Partnerships Expand Industrial and Transport Activities

    ITM reported additional commercial relationships with Protium, Rheinmetall and Deutsche Bahn.

    These arrangements broaden the range of potential applications for the company’s hydrogen technology, including industrial production, transport and defence-related energy infrastructure.

    The company continues to pursue opportunities involving hydrogen production for industrial decarbonisation, grid-balancing applications and synthetic fuels.

    Its international project pipeline includes opportunities across Europe, Asia-Pacific and North America.

    The supplied update does not specify the financial value or contractual status of each partnership.

    FY2027 Revenue Guidance Set at £50 Million–£60 Million

    ITM expects revenue of £50 million to £60 million for FY2027, compared with the £43.6 million reported for FY2026.

    The company also anticipates a further reduction in adjusted EBITDA losses as it progresses contract delivery and manufacturing operations.

    Management said cash management will remain a priority during the investment phase associated with the Chronos manufacturing expansion.

    The £144.0 million contract backlog provides visibility over existing contracted work, although the timing of revenue recognition will depend on project delivery schedules.

    ITM’s priorities for the coming financial year include executing its existing contracts, advancing the Chronos production line, progressing Hydropulse projects and developing further commercial opportunities.

    The company enters FY2027 with £215.6 million in year-end cash, a £144.0 million contract backlog and revenue guidance indicating further growth from its FY2026 level.
  • Serica Energy Reports 44% Production Growth and $905 Million Revenue as Main Market Listing Plans Progress

    Serica Energy Reports 44% Production Growth and $905 Million Revenue as Main Market Listing Plans Progress

    Serica Energy plc (LSE:SQZ) reported a 44% year-on-year increase in average production to 37,100 barrels of oil equivalent per day (boepd) for the nine months ended 30 September 2026, while revenue more than doubled to $905 million.

    The UK North Sea oil and gas producer maintained its post-tax cash flow guidance of $450 million to $475 million, despite extended maintenance work at the Triton floating production, storage and offloading (FPSO) vessel.

    Current production is approximately 40,000 boepd, with Serica expecting output to increase to around 65,000 boepd once Triton returns to operation.

    The company reported net debt of $73 million and total liquidity of $685 million, while progressing drilling programmes across its existing portfolio and evaluating potential acquisitions.

    Serica is also preparing to transfer its listing from AIM to the London Stock Exchange’s Main Market.

    Nine-Month Production Rises 44% to 37,100 Boepd

    Serica reported average production of 37,100 boepd during the first nine months of 2026, an increase of 44% compared with the corresponding period of 2025.

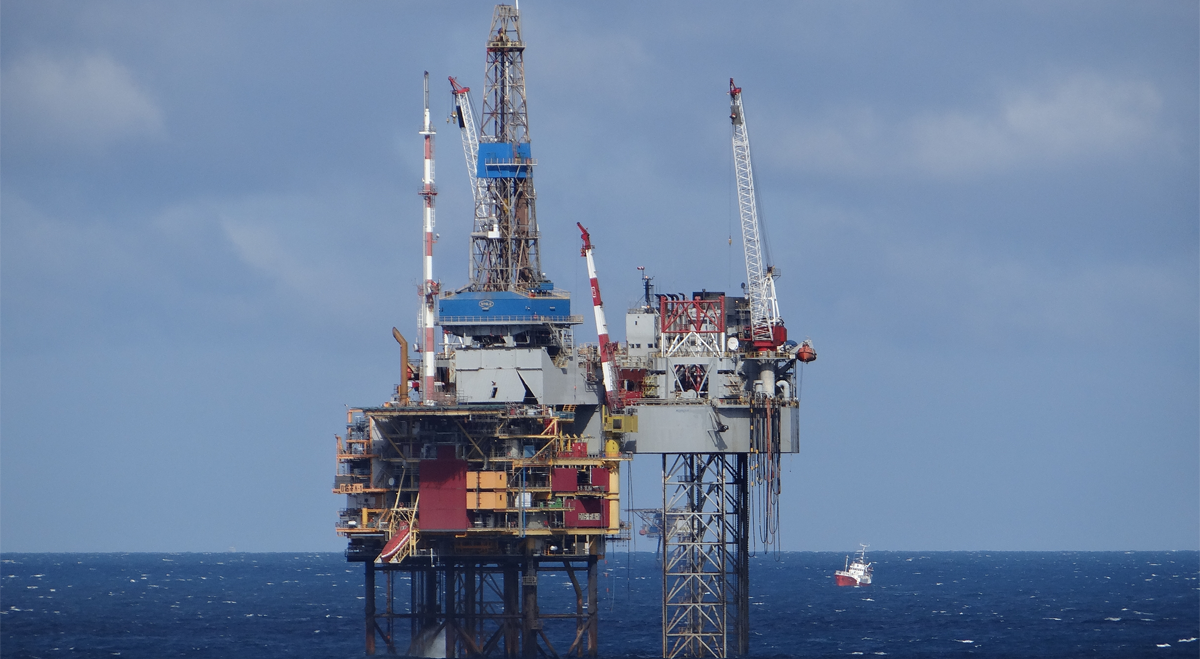
    The company operates oil and gas assets across the UK Continental Shelf, including the Bruce, Keith and Rhum fields in the Northern North Sea and interests connected to the Triton FPSO in the Central North Sea.

    Production during the period was affected by an extended maintenance programme at Triton, which has delayed the return of associated output.

    Serica said current production is approximately 40,000 boepd and expects this to increase to around 65,000 boepd following the return of Triton.

    The anticipated increase remains dependent on the completion of maintenance activities and the resumption of production from the affected fields.

    The company also holds operated and non-operated interests in other North Sea assets, including a developing position in the Southern North Sea gas basin.

    Revenue More Than Doubles to $905 Million

    Serica reported revenue of $905 million for the nine months to September, more than double the amount recorded in the corresponding period of the previous year.

    The increase accompanied higher average production across the group’s portfolio.

    The company maintained its post-tax cash flow guidance of $450 million to $475 million for 2026.

    At the reporting date, Serica recorded net debt of $73 million and total liquidity of $685 million.

    The company said its financial position reflected its approach to capital expenditure and shareholder distributions, including dividend payments.

    The reported liquidity provides financial resources for ongoing operations and planned investment activities, although future cash generation will remain dependent on production levels, commodity prices and expenditure.

    Drilling Programme Targets Existing North Sea Assets

    Serica is progressing an organic development programme across its operated and non-operated interests.

    The programme includes a multi-well drilling campaign at the Bruce field and other production hubs.

    The company is also planning infill drilling at several non-operated fields, targeting additional production from existing reservoirs and infrastructure.

    Alongside these activities, Serica is advancing the Skerryvore exploration well.

    The planned drilling operations are intended to evaluate additional resources and support future production from the group’s UK Continental Shelf portfolio.

    The scale and timing of any resulting production increases will depend on drilling outcomes, development decisions and operational performance.

    Tornado Gas Processing Discussions Continue

    Serica is holding discussions concerning the potential processing of gas from the Tornado field through the Shetland Gas Plant.

    The proposed arrangement would involve using existing processing infrastructure to handle production from Tornado.

    The company said the potential agreement could contribute to extending the operational life of the Shetland Gas Plant.

    Discussions remain ongoing, and no completed processing agreement has been announced in the supplied update.

    Any future arrangement would depend on the outcome of negotiations and the relevant technical and commercial requirements.

    North Sea and International Acquisitions Under Review

    In addition to its drilling and development programme, Serica is evaluating potential merger and acquisition opportunities.

    The company is reviewing assets in the North Sea and international markets as part of its wider growth strategy.

    Serica’s existing portfolio comprises a combination of operated and non-operated oil and gas interests, with production distributed across several UK offshore regions.

    The company has not announced a specific new acquisition or binding transaction arising from its current screening activities.

    Any future investments would be subject to the relevant commercial assessments and transaction conditions.

    Main Market Transfer Could Support FTSE 250 Eligibility

    Serica is preparing to transfer its stock market listing from AIM to the Main Market of the London Stock Exchange.

    The proposed move forms part of the company’s plans to broaden access to institutional investors and increase its visibility in the public equity market.

    A Main Market listing could also make Serica eligible for consideration for inclusion in the FTSE 250 index, subject to the applicable index requirements.

    Index inclusion would not be automatic following the transfer.

    The company has not provided a confirmed date for completion of the proposed listing change in the supplied update.

    Full-Year Cash Flow Guidance Maintained

    Serica maintained its 2026 post-tax cash flow guidance of $450 million to $475 million following the nine-month operational and financial update.

    The company expects production to increase from approximately 40,000 boepd to around 65,000 boepd once the Triton FPSO returns to operation.

    Its development priorities include the Bruce drilling programme, infill wells across non-operated assets, the Skerryvore exploration well and discussions concerning Tornado gas processing.

    Serica is also continuing its review of potential acquisitions while preparing for the proposed Main Market listing.

    The group enters the final quarter of 2026 with nine-month revenue of $905 million, average production of 37,100 boepd, net debt of $73 million and total liquidity of $685 million.

  • Volex Expects Record First-Half Revenue of at Least $710 Million and Raises FY2027 Profit Outlook

    Volex Expects Record First-Half Revenue of at Least $710 Million and Raises FY2027 Profit Outlook

    Volex plc (LSE:VLX) expects to report record revenue of at least $710 million for the six months ended 30 September 2026, following growth across all five of its end-markets.

    The manufacturer of power and data transmission products said first-half revenue is expected to increase by at least 21% year on year on an organic constant currency basis.

    Growth was supported by demand across Complex Industrial Technology, Electric Vehicles (EV) & Electrification and Consumer Electricals, alongside contributions from the acquisition of Kepler SignalTek (KST).

    The group also reported continued improvement in its underlying operating margin and now expects underlying operating profit for the financial year ending 2027 to be towards the upper end of market expectations.

    Volex anticipates second-half revenue broadly in line with the first six months.

    First-Half Revenue Expected to Reach at Least $710 Million

    Volex reported that trading during the first half of FY2027 resulted in expected revenue of at least $710 million, representing a record six-month performance for the group.

    On an organic constant currency basis, revenue growth is expected to be at least 21% compared with the corresponding period of the previous financial year.

    The company recorded growth across all five end-markets, with particular contributions from Complex Industrial Technology, EV & Electrification and Consumer Electricals.

    Trading also benefited from additional customer orders placed ahead of the planned consolidation of the group’s US manufacturing facilities.

    These orders contributed to first-half activity, although the company did not quantify their individual impact on revenue.

    The acquisition of Kepler SignalTek also contributed to the group’s reported performance.

    Growth Across Industrial, Electrical and EV Markets

    Volex supplies power and data transmission products to original equipment manufacturers (OEMs) and electronics manufacturing services (EMS) companies.

    Its operations are organised across five end-markets: Complex Industrial Technology, Consumer Electricals, EV & Electrification, Medical and Off-Highway.

    The company reported revenue growth across each of these markets during the six-month period.

    Complex Industrial Technology includes applications in areas such as aerospace, defence and other industrial equipment, while EV & Electrification covers products used in electric vehicle and related electrical infrastructure applications.

    Consumer Electricals includes components used in domestic and other electrical equipment.

    The group’s customer base spans multiple industries and geographical markets, with manufacturing operations supporting international supply requirements.

    Operating Margin Moves Towards 12% Target

    Volex reported further improvement in its underlying operating margin during the first half.

    The company attributed the increase to changes in its revenue mix, contributions from higher-margin activities acquired through Kepler SignalTek and continuing operational efficiency measures.

    Volex has established a medium-term underlying operating margin target of 12%.

    Management said the first-half performance represented further progress towards that objective.

    The company did not provide a specific first-half underlying operating margin figure in the supplied update.

    Its operational initiatives include the consolidation of US manufacturing facilities and continued efforts to improve production efficiency across its international operations.

    FY2027 Underlying Operating Profit Outlook Raised

    Following the first-half trading performance, Volex revised its expectations for full-year profitability.

    The group now anticipates underlying operating profit for FY2027 towards the upper end of current market expectations.

    The company expects revenue in the second half of the financial year to be broadly consistent with the first-half level.

    This outlook follows the expected first-half revenue performance of at least $710 million and the improvement in underlying operating margins.

    Volex did not specify the numerical range of market profit expectations in the supplied announcement.

    The revised guidance remains a management forecast and will depend on trading conditions and operational performance during the remainder of the financial year.

    Financial Position Supports Acquisition Strategy

    Volex reported that leverage remains low, with its available borrowing facilities largely undrawn.

    The company continues to pursue a strategy combining organic growth, operational improvements and acquisitions.

    Its acquisition of Kepler SignalTek has contributed to the group’s revenue mix and underlying operating margin performance.

    Volex said its financial position provides capacity to consider further acquisitions that meet its investment criteria.

    The company operates internationally, supplying power and data products for applications including industrial equipment, medical devices, electric vehicles and consumer electrical systems.

    Second-Half Revenue Expected to Match First-Half Levels

    Volex enters the second half of FY2027 expecting revenue broadly in line with the record first-half performance.

    The company has maintained its medium-term underlying operating margin target of 12% while raising its full-year profit outlook towards the upper end of market expectations.

    Its operational priorities include progressing the consolidation of US manufacturing sites, maintaining efficiency improvements and evaluating potential acquisitions.

    The group expects to report first-half revenue of at least $710 million, with organic constant currency growth of at least 21%, subject to the finalisation of its interim financial results.

  • GSK Reports 61% Response Rate for Ris-Rez in Phase Ib Small Cell Lung Cancer Trial

    GSK Reports 61% Response Rate for Ris-Rez in Phase Ib Small Cell Lung Cancer Trial

    GSK (LSE:GSK) has reported initial global clinical results for risvutatug rezetecan (Ris-Rez), an investigational B7-H3-targeted antibody-drug conjugate, showing a 61% objective response rate in patients with relapsed extensive-stage small cell lung cancer (ES-SCLC) at the selected 8 mg/kg dose.

    The findings come from the phase Ib EMBOLD PanTumour-101 trial, in which the treatment demonstrated what the company described as a manageable safety profile. The results support the dose selection for GSK’s ongoing global phase III EMBOLD SCLC-301 study.

    The latest data follow positive results from a pivotal clinical study conducted in China and form part of GSK’s broader development programme evaluating Ris-Rez in cancers with limited treatment options.

    Phase III Development Under Way

    GSK is advancing Ris-Rez through its EMBOLD clinical development programme, which has treated more than 1,000 patients across multiple solid tumour indications.

    Phase III studies are currently under way in patients with later-line extensive-stage small cell lung cancer and metastatic castration-resistant prostate cancer. The company also plans additional clinical trials evaluating the treatment in earlier disease settings.

    Ris-Rez is designed to target B7-H3, a protein associated with several tumour types. The investigational therapy belongs to the antibody-drug conjugate class, which combines an antibody targeting a specific protein with a cancer treatment payload.

    The global phase III EMBOLD SCLC-301 study will further evaluate Ris-Rez in relapsed ES-SCLC, building on the response and safety findings reported in the earlier clinical programme.

    Regulatory Designations and Oncology Strategy

    Ris-Rez has received several regulatory designations, including orphan drug and Breakthrough Therapy designations for small cell lung cancer in key markets.

    These designations form part of the treatment’s regulatory development pathway as GSK continues clinical testing across multiple cancer indications.

    The company is evaluating Ris-Rez in extensive-stage small cell lung cancer, where treatment options following relapse remain limited and no single established standard applies across all patients.

    GSK’s oncology development activities include targeted small molecules, antibody-drug conjugates and immunotherapies, with programmes covering haematological, lung, gastrointestinal, genitourinary and gynaecological cancers.

    The latest EMBOLD PanTumour-101 findings provide additional clinical response and safety data for Ris-Rez as the company progresses its phase III studies. Further trial results will be needed to establish the treatment’s efficacy and safety in the populations being evaluated.

  • NYSE Short Positions Exceed 21 Billion Shares as EPFR Identifies Contrarian Market Signal

    NYSE Short Positions Exceed 21 Billion Shares as EPFR Identifies Contrarian Market Signal

    The number of shares sold short on the New York Stock Exchange reached an all-time high in late September, with aggregate short interest exceeding 21 billion shares, according to EPFR.

    The firm’s global market intelligence team reported a 2.7% increase in short positions in its latest semi-monthly data, marking the first time the total has crossed the 21 billion-share level.

    EPFR said the continuing rise in short interest could be interpreted positively by investors who assess market positioning from a contrarian perspective.

    Record Short Interest Extends Longer-Term Trend

    The latest NYSE short-interest figures indicate that bearish positioning continued to increase during the second half of September.

    EPFR reported that the longer-term trajectory of short interest also remains upward.

    Short interest measures the number of shares investors have sold short and have not yet repurchased to close their positions. These transactions generally reflect expectations of lower share prices, although short positions may also be used for hedging purposes.

    EPFR characterised the record positioning as a potentially favourable contrarian indicator.

    The interpretation reflects the possibility that existing short positions could generate buying demand if investors subsequently repurchase shares to close their positions.

    The data, however, provide no indication of when such activity might take place or how it would affect broader equity indices.

    Nasdaq 100 Falls as Technology Stocks Retreat

    The increase in short interest coincided with a period of renewed selling in US technology equities.

    The Nasdaq 100 declined 2% on Wednesday, while futures linked to the index fell more than 1% in early Thursday trading.

    These movements extended a reversal in technology shares following gains earlier in the year associated with artificial intelligence investment.

    Questions about the sustainability of AI demand have featured in the broader market environment during the period.

    Although the NYSE short-interest figures and Nasdaq 100 declines occurred within the same general timeframe, the available information does not demonstrate that one development caused the other.

    Market Positioning Remains in Focus

    EPFR’s analysis places the record short-interest level within a longer-term increase in bearish market positioning.

    The firm’s contrarian interpretation differs from the conventional view that rising short interest reflects expectations of lower equity prices.

    Both interpretations concern investor positioning rather than confirmed future market movements.

    With more than 21 billion NYSE-listed shares held short at the end of the reporting period, the latest EPFR data provide a measure of positioning as US technology equities experience renewed price fluctuations.

  • JPMorgan Sees Wider Corporate Earnings Growth Supporting Q3 Equity Market Outlook

    JPMorgan Sees Wider Corporate Earnings Growth Supporting Q3 Equity Market Outlook

    JPMorgan expects third-quarter corporate earnings to provide a foundation for equity markets as profit growth extends beyond the technology companies that have accounted for a substantial share of recent US earnings expansion.

    Strategists led by Mislav Matejka said that while headline earnings forecasts appear elevated, underlying estimates suggest more moderate growth expectations across the wider market. The bank anticipates that corporate results could become a greater focus for investors following September’s market volatility.

    S&P 500 Earnings Estimates Vary Across Data Providers

    Consensus forecasts compiled by IBES indicate that S&P 500 earnings per share will increase 24% in the third quarter. FactSet and LSEG estimates put growth at 30%, reflecting an adjustment for a one-time tax charge involving Meta (NASDAQ:META).

    However, the projected increase declines to 15% when Nvidia (NASDAQ:NVDA) and Micron Technology (NASDAQ:MU) are excluded.

    The median S&P 500 constituent is expected to record earnings growth of 8%, indicating a difference between aggregate index performance and the results anticipated for individual companies.

    European companies are forecast to deliver earnings growth of 19%, according to consensus estimates. Removing the energy sector reduces the expected increase to 11%, while median earnings growth stands at 9%.

    Median revenue growth is projected at 7% for companies in both the S&P 500 and Stoxx 600 indices.

    These figures form part of JPMorgan’s assessment that earnings growth is extending across a wider range of companies.

    Global Economic Activity Supports Earnings Forecasts

    JPMorgan cited global purchasing managers’ indices as evidence supporting its earnings outlook. The indicators accelerated during the third quarter, reaching multi-year highs.

    The bank’s earnings lead indicator has also continued to rise. Historically, the measure has preceded changes in reported corporate earnings by approximately two quarters.

    Based on this relationship, JPMorgan expects earnings conditions to remain supportive over at least the next two reporting seasons.

    The strategists also observed that the proportion of global companies reporting accelerating earnings growth is close to a historical high.

    Artificial intelligence-related businesses remain important contributors to US earnings expansion, although JPMorgan identified an increasing contribution from companies operating outside that segment.

    European Earnings Outlook Includes Higher Margins

    JPMorgan expects European companies to benefit from further operating margin expansion, with earnings before interest and taxes projected to represent 14.4% of sales this year.

    That figure is 250 basis points above the corresponding level in 2019.

    The bank anticipates improvements across most sectors, excluding consumer staples, automotive businesses and software companies.

    Currency movements could also influence results. JPMorgan expects a weaker euro to provide some support for exporters, while energy companies may exceed current earnings forecasts.

    The strategists identified mining companies as a potential source of earnings risk. Businesses with exposure to China and consumer demand may also report more subdued results, while higher energy costs could feature in corporate commentary.

    JPMorgan Highlights Banks and Industrial Companies

    Semiconductor manufacturers and industrial companies are among the sectors JPMorgan expects to report results above market expectations.

    The bank also anticipates earnings support for European financial institutions, despite a reduction of more than 10% in banking-sector valuations during recent weeks.

    French equities have undergone valuation declines exceeding 15%, although JPMorgan said corporate earnings have remained comparatively stable.

    The strategists noted that companies in the CAC 40 generate approximately three-quarters of their revenue outside France, making international operations an important component of their financial performance.

    JPMorgan continues to favour European semiconductors, banks, chemicals and industrials within its sector positioning.

    Bond Market Developments Remain a Factor

    The bank’s equity outlook also considers recent movements in government bond yields.

    JPMorgan suggested that the increase in yields may be approaching an oversold condition, potentially limiting further upward movement.

    If bond yields stabilise as third-quarter earnings announcements begin, the strategists believe equity markets could advance towards year-end, with market activity reflecting greater appetite for risk.

    The bank’s broader assessment is that corporate earnings and economic fundamentals could regain prominence in investor decision-making as the reporting season progresses.

  • Wall Street Futures Steady After Market Rebound as Inflation Pressures Persist

    Wall Street Futures Steady After Market Rebound as Inflation Pressures Persist

    US stock index futures indicated a largely flat opening on Friday following a volatile period for Wall Street, with investors weighing the recovery in major indices against unexpectedly strong inflation data and continued uncertainty surrounding technology shares.

    The market staged a substantial turnaround on Thursday after an early decline pushed the Nasdaq Composite to its lowest intraday level in almost a month.

    The Dow Jones Industrial Average subsequently closed at its highest level in a month, supported by gains in several major companies, while falling Treasury yields helped improve market sentiment.

    Despite the rebound, futures showed little movement ahead of Friday’s opening bell.

    Dow Gains More Than 550 Points in Thursday Recovery

    Wall Street’s latest recovery followed a difficult period for technology stocks, which came under renewed selling pressure on Wednesday.

    The weakness continued into Thursday’s session before buyers returned, allowing the major US indices to reverse their earlier declines.

    The Dow Jones Industrial Average gained 556.21 points, or 1.1%, to finish at 52,177.69.

    Shares of Nike (NYSE:NKE), Salesforce (NYSE:CRM) and Home Depot (NYSE:HD) contributed to the index’s advance.

    The S&P 500 added 25.12 points, equivalent to 0.3%, closing at 7,744.06.

    The Nasdaq Composite, which had spent much of the session in negative territory, finished 20.16 points higher, or 0.1%, at 26,713.03.

    Its recovery from an intraday low not seen in almost a month suggested that some investors were prepared to buy technology shares following their recent declines.

    However, the sector’s performance remained uneven, with computer hardware companies continuing to lose ground.

    Artificial Intelligence Outlook Remains a Key Market Consideration

    Concerns surrounding the outlook for artificial intelligence investments contributed to the technology sector’s recent weakness.

    Investors have been reassessing expectations for companies involved in AI development and computing infrastructure following a period of strong interest in the sector.

    Comments from Federal Reserve Chair Kevin Warsh during the annual meetings of the International Monetary Fund and World Bank in Bangkok drew further attention to the technology’s economic significance.

    Warsh characterised artificial intelligence as “the most profound economic transformation of a lifetime”.

    His remarks highlighted the potential importance of AI for productivity and economic activity over the longer term.

    However, the Fed chair did not indicate how the development of artificial intelligence might influence the central bank’s immediate interest rate decisions.

    The absence of specific monetary policy guidance left investors focused on inflation figures and market expectations for the next Federal Reserve meeting.

    September Producer Prices Increase More Than Expected

    Inflation data released during the week showed that price pressures in the United States remained elevated.

    The Labor Department reported a 1.3% monthly increase in the producer price index for final demand in September.

    The rise followed an upwardly revised increase of 0.5% in August and substantially exceeded economists’ forecast of another 0.5% gain.

    Annual producer price inflation reached 6.3%, compared with an upwardly revised 5.6% in the previous month.

    The stronger figures suggested that inflationary pressures at the producer level had intensified.

    Separate data published on Friday showed that US import and export prices also rose by considerably more than expected in September.

    Nevertheless, stock index futures showed little reaction to the latest figures.

    Market pricing reflected in CME Group’s FedWatch Tool continued to indicate that the Federal Reserve was likely to keep interest rates unchanged at its upcoming October meeting.

    Falling Treasury Yields Support Equity Recovery

    The improvement in US equities on Thursday coincided with a sharp decline in government bond yields.

    The benchmark 10-year Treasury yield fell to a three-week low, despite the release of the stronger producer price inflation figures.

    Declining yields can make equities more attractive relative to fixed-income investments and reduce the financing costs faced by companies.

    They can also support valuations, particularly for businesses whose market prices depend heavily on expectations of future earnings.

    The fall in yields may therefore have helped offset some of the concerns surrounding inflation and technology sector valuations.

    However, the contrast between elevated inflation and lower bond yields highlighted the uncertainty surrounding the market’s near-term outlook.

    Gold Mining and Airline Shares Record Strong Gains

    Thursday’s recovery extended beyond the major stock indices, with several industry groups recording substantial advances.

    Gold mining companies benefited from an increase in the precious metal’s price.

    The NYSE Arca Gold Bugs Index jumped 4.7%, recovering after reaching its lowest closing level in more than two months during the previous session.

    Airline stocks also attracted buying interest.

    The NYSE Arca Airline Index rose 3.8%, following Wednesday’s decline to a six-month closing low.

    Housing-related shares advanced, lifting the Philadelphia Housing Sector Index by 3.6%.

    Biotechnology, healthcare and pharmaceutical companies also recorded notable gains.

    The broad improvement in these sectors contrasted with continued weakness among computer hardware stocks.

    The NYSE Arca Computer Hardware Index fell 2.5%, reaching its lowest closing level in well over a month.

    The divergence indicated that the market recovery was not equally distributed across all industries.

    Markets Look for Direction Ahead of Next Fed Decision

    Friday’s flat futures suggested that investors were reluctant to establish a clear market direction immediately after the sharp fluctuations earlier in the week.

    Thursday’s gains demonstrated that buying interest remained present, particularly in sectors that had experienced recent declines.

    However, the latest inflation figures reinforced uncertainty about the outlook for US interest rates.

    Although market expectations continued to favour unchanged Federal Reserve rates later in October, investors remained attentive to further economic releases and developments in the bond market.

    Technology sector performance is also likely to remain important after the Nasdaq’s recent volatility.

    The combination of inflation concerns, shifting Treasury yields and questions about AI-related valuations could continue to influence US equity trading in the near term.

  • European Shares Extend Gains as Corporate Earnings Strengthen and Bond Yields Ease: DAX, CAC, FTSE100

    European Shares Extend Gains as Corporate Earnings Strengthen and Bond Yields Ease: DAX, CAC, FTSE100

    European stock markets advanced on Friday, extending gains from the previous session as stronger corporate earnings and declining global bond yields supported investor sentiment. The latest increases followed Thursday’s trading, when regional equities reached their highest levels in more than two weeks.

    Technology shares recovered some of their recent losses, while positive company announcements provided support across aerospace, industrial manufacturing and renewable energy stocks.

    Germany’s DAX rose 0.9%, while France’s CAC 40 gained 0.3%. The UK’s FTSE 100 traded marginally below the unchanged level.

    Technology Stocks Recover as AI Sector Remains in Focus

    European technology stocks rebounded following a period of selling pressure, supported by comments from Nvidia Chief Executive Officer Jensen Huang regarding the financial position of AI computing infrastructure provider CoreWeave Inc.

    Huang defended CoreWeave’s financial health, helping to ease some concerns surrounding companies involved in the expansion of artificial intelligence infrastructure.

    AI also featured prominently in discussions at the annual meetings of the International Monetary Fund and World Bank.

    Federal Reserve Chair Kevin Warsh described artificial intelligence as the most consequential economic transformation of his lifetime for both the United States and the global economy.

    However, Warsh avoided offering specific guidance on forthcoming Federal Reserve interest rate decisions, leaving investors to assess the potential direction of monetary policy.

    Eurozone Inflation Rises to 3.8% in September

    Currency markets remained relatively stable, with the euro trading close to unchanged against the US dollar over the week.

    Preliminary economic figures showed that annual inflation in the eurozone accelerated to 3.8% in September, compared with 3.2% in August.

    The increase highlighted continued inflationary pressures across the currency bloc, even as global government bond yields eased.

    Lower bond yields can support equity valuations by reducing the discount rates applied to expected future corporate earnings.

    Nevertheless, the latest inflation figures remain relevant to expectations surrounding European monetary policy.

    Airbus Gains Following 75-Aircraft Order

    Airbus (EU:AIR) shares advanced in Paris after the aerospace manufacturer secured an order from Aviation Capital Group for 75 aircraft from the A320neo Family.

    The agreement adds to Airbus’s commercial aircraft order book and reflects continuing demand for narrow-body aircraft.

    The announcement provided support for the company’s shares during Friday’s European trading session.

    Alstom Secures 15-Year Greater Anglia Contract Extension

    Alstom (EU:ALO) also recorded gains after announcing a 15-year extension to its train services agreement with British rail operator Greater Anglia.

    The extended agreement covers Greater Anglia’s Class 720 Aventra fleet, continuing the relationship between the rolling stock manufacturer and the operator.

    The contract provides a longer-term framework for Alstom’s involvement in servicing the fleet.

    Financial terms of the extension were not disclosed in the announcement.

    Porsche Shares Rise Following Mission S Unveiling

    Porsche (TG:PAH3) shares climbed after the German sports car manufacturer presented its Mission S vision model.

    The concept showcases the company’s evolving design direction under its ‘Sportwagenschmiede ’35’ strategy.

    The presentation outlines elements of Porsche’s intended future design identity, although the company did not provide details of a production timetable for the concept.

    Nordex and AIXTRON Advance on Quarterly Updates

    Wind turbine manufacturer Nordex (TG:NDX1) recorded strong gains after publishing third-quarter results and increasing its profit margin forecast for 2026.

    The improved outlook supported investor interest in the renewable energy equipment manufacturer.

    Semiconductor equipment supplier AIXTRON (TG:AIXA) also moved sharply higher after reporting third-quarter order intake above market expectations.

    The stronger-than-anticipated intake provided a positive indication of demand for the company’s manufacturing equipment.

    Ithaca Energy Announces Planned CEO Retirement

    Ithaca Energy (LSE:ITH) shares advanced after the British oil and gas producer announced that Chief Executive Officer Luciano Vasques intends to retire by 31 March 2027.

    The announcement establishes a timetable for a forthcoming leadership transition at the company.

    Further details regarding succession arrangements were not included in the reported announcement.

    European Markets Supported by Earnings and Lower Yields

    Friday’s gains reflected a combination of corporate developments, improving technology sector sentiment and easing global bond yields.

    The DAX led the major European indices with a 0.9% increase, followed by the CAC 40’s 0.3% advance, while the FTSE 100 remained slightly negative.

    Investors continued to monitor inflation developments, central bank policy expectations and corporate earnings as markets assessed the sustainability of the recent recovery.

  • MedPal AI Builds Momentum at New Health as Customer Numbers and Repeat Revenue Grow

    MedPal AI Builds Momentum at New Health as Customer Numbers and Repeat Revenue Grow

    MedPal AI (LSE:MPAL) is demonstrating the growth potential of its digital healthcare platform, with its New Health business rapidly expanding its customer base in the UK GLP-1 market while increasing repeat business and investing in the infrastructure needed to support further growth.

    Since launching in July and beginning marketing activity in August, New Health has climbed from 3,048th to 29th in Eli Lilly’s Mounjaro supplier rankings in just three months. The platform has attracted more than 42,500 customers, highlighting the strong demand for its competitively priced digital healthcare services.

    For MedPal AI, the opportunity extends beyond acquiring customers. The company is focused on combining technology, operational efficiency and customer retention to build a scalable business capable of generating recurring revenue across multiple healthcare channels.

    Technology and competitive pricing drive customer acquisition

    MedPal AI’s CEO, Jason Drummond, attributes New Health’s rapid progress to the combination of an efficient service, competitive pricing and the use of artificial intelligence and robotics to reduce operating costs.

    By leveraging these technologies, the company aims to offer customers strong value while maintaining attractive returns on individual orders. This approach has helped New Health establish a competitive position in the growing UK market for GLP-1 treatments, including Mounjaro.

    The rapid rise through Eli Lilly’s supplier rankings provides a clear indication of the platform’s early commercial traction. With tens of thousands of customers already signed up, New Health has established a substantial base from which to develop its next phase of growth.

    Repeat business strengthens the revenue model

    While customer acquisition has been a major driver of New Health’s early success, MedPal AI is also reporting encouraging progress in customer retention.

    According to Drummond, repeat orders now account for more than 30% of New Health’s revenue, up from approximately 20% in the previous month. This growing contribution from returning customers is an important development as the company works to establish a more sustainable and predictable revenue model.

    Drummond highlighted the importance of retaining customers across the business, explaining that attracting large numbers of new users is only part of the equation. Converting those customers into repeat purchasers is central to building long-term value.

    This focus on repeat revenue extends across MedPal AI’s broader healthcare operations, including NHS prescribing, care home services and New Health’s GLP-1 offering. Together, these activities provide the company with opportunities to develop customer relationships and generate ongoing demand across different areas of digital healthcare.

    Infrastructure supports the next stage of expansion

    Supporting rapid growth requires operational capacity as well as customer demand. MedPal AI has invested millions of pounds in its Sarus Court distribution hub in the north of England, providing infrastructure designed to accommodate the growing volume of orders.

    The investment reflects the company’s focus on building the operational foundations required to support its expanding customer base. As New Health continues to develop, fulfilment capacity and efficiency will remain important factors in delivering a consistent service while managing costs.

    The combination of an established distribution facility, technology-led operations and an increasing proportion of repeat revenue gives MedPal AI a platform from which to pursue further growth.

    Building a scalable digital healthcare business

    New Health’s progress illustrates MedPal AI’s wider strategy of applying technology and operational efficiency to healthcare services with recurring customer demand.

    The business has moved quickly from launch to a position among the leading Mounjaro suppliers by ranking, while the increase in repeat revenue suggests that its proposition is gaining traction beyond initial customer sign-ups.

    For MedPal AI, the next phase will centre on maintaining customer growth, encouraging repeat orders and ensuring its infrastructure can support expanding demand. The company’s broader healthcare activities also provide additional avenues for developing recurring revenues.

    With more than 42,500 New Health customers, repeat business contributing over 30% of revenue and significant investment already made in distribution capacity, MedPal AI is building the foundations for its next stage of development.

    The challenge now is to sustain that momentum, converting early commercial success into a growing, efficient and repeat-revenue-led digital healthcare business.

  • Market Open: Iofina Q3 Iodine Output, ECR Commissions Maddens Plant

    Market Open: Iofina Q3 Iodine Output, ECR Commissions Maddens Plant

    FTSE 100 dips as Middle East tensions keep Brent above $100, while Iofina reports Q3 iodine output and ECR Minerals commissions Maddens gold plant.

    Market Overview

    London opened almost flat, with the FTSE 100 down 0.010 per cent at 10,839.22. Middle East tensions are keeping oil prices high, and Iran’s army chief has said the Strait of Hormuz will stay closed. Continental markets were firmer. The Euronext 100 rose 0.025 per cent to 1,863.20 and the DAX gained 0.411 per cent to 25,487.05, as European stocks headed for their best week since August. Sovereign yields have eased from recent multi-decade highs and technology shares have recovered from Thursday’s AI and semiconductor sell-off. On Wall Street, the Nasdaq 100 closed down 0.05 per cent at 29,935.60, while the S&P 500 rose 0.33 per cent to 7,744.06. Inflation and the outlook for US interest rates remain the main concern.

    Brent crude edged lower. Investors are weighing reports that Washington may lift sanctions on some shadow-fleet tankers to bring down record freight rates, alongside the International Energy Agency’s agreement to release the rest of its emergency stocks. Analysts say a significant risk premium remains while there is no US-Iran agreement. Gold eased slightly from elevated levels, copper edged higher and natural gas firmed marginally ahead of winter. Bitcoin rose against sterling. The pound was marginally softer at the open against the dollar, euro, Swiss franc, yen and Australian dollar. Sentiment in the UK is also being shaped by the 28 October Budget, where the Chancellor is expected to raise taxes on banks.

    Market Numbers

    FTSE 100: Down (-0.01%), 10,839.22
    Euronext 100: Up (+0.02%), 1,863.20
    DAX: Up (+0.41%), 25,487.05
    NASDAQ: Down (-0.05%), 29,935.60
    S&P 500: Up (+0.33%), 7,744.06


    In the Headlines

    Q3 production update – Iofina (LSE:IOF)
    Iofina reported third-quarter iodine production of 205.2 tonnes and said it is advancing work on new plants. The update gives investors a view of operating output as the company works to expand its production base.

    Plant commissioning – ECR Minerals (LSE:ECR)
    ECR Minerals has commissioned its Maddens gold processing plant, and underground development is progressing. This moves the company closer to processing ore on site while gold prices remain historically high.

    Currencies (vs GBP)

    USD: Down (-0.005%), $1.3271
    CHF: Down (-0.022%), Fr.1.0984
    EUR: Down (-0.0008%), €1.1836
    JPY: Down (-0.019%), ¥209.865
    AUD: Down (-0.008%), $1.9182
    Bitcoin (BTC/GBP): Up (+0.28%), £61,641.0

    Commodities

    Copper: Up
    Gold: Down
    Brent Crude: Down
    Natural Gas: Up