Category: Top Story

  • Market Open: Dunelm Sales Rise, Anglo Asian Copper Output

    Market Open: Dunelm Sales Rise, Anglo Asian Copper Output

    FTSE 100 rises as Dunelm reports sales growth and Anglo Asian Mining confirms copper output. European shares weaken while Brent crude declines.

    Market Overview

    The FTSE 100 opened higher on Thursday, gaining 0.18 per cent to 10,742.59, as stronger-than-expected UK GDP data helped offset concerns surrounding technology stocks and US inflation. European markets weakened, with the Euronext 100 falling 0.73 per cent and Germany’s DAX declining 0.37 per cent. On Wall Street, the Nasdaq closed lower at 26,692.87, while the S&P 500 fell to 7,718.94, reflecting pressure on technology shares and renewed inflation concerns.

    Commodity markets were mixed, with copper declining while gold advanced. Brent crude and natural gas both moved lower, as oil traders assessed the global supply outlook alongside continuing geopolitical tensions in the Middle East. Bitcoin edged down against sterling. In currency markets, the pound strengthened against the US dollar, Japanese yen and Australian dollar but weakened against the Swiss franc and euro, as investors assessed inflation risks and the outlook for monetary policy.


    Market Numbers

    FTSE 100: Up (+0.18%), 10,742.59

    Euronext 100: Down (-0.73%), 1,852.85

    DAX: Down (-0.37%), 25,204.26

    NASDAQ: Down, 26,692.87

    S&P 500: Down, 7,718.94


    In the Headlines

    Quarterly Sales Growth – Dunelm Group (LSE:DNLM)
    UK homewares retailer Dunelm reported a 1.1 per cent increase in first-quarter FY27 sales to £433 million, with trading improving towards the end of the period following a slower start. The company maintained its full-year adjusted profit outlook despite subdued consumer demand and expectations of lower first-half profitability.

    Copper Production Update – Anglo Asian Mining (LSE:AAZ)
    Anglo Asian Mining reported third-quarter copper production of 5,514 tonnes and reaffirmed its production guidance for 2026. The update provides investors with an indication of operational progress as the mining group continues developing its copper production activities.


    Currencies (vs GBP)

    USD: Down (-0.13%), $1.3248

    CHF: Up (+0.12%), Fr.1.0991

    EUR: Up (+0.02%), €1.1815

    JPY: Down (-0.15%), ¥209.2865

    AUD: Down (-0.69%), $1.909

    Bitcoin (BTC/GBP): Down, £61,261.94


    Commodities

    Copper: Down

    Gold: Up

    Brent Crude: Down

    Natural Gas: Down

  • Wall Street Futures Slide as AI Financing Risks Persist Despite Strong Anthropic and TSMC Results: Dow Jones, S&P, Nasdaq

    Wall Street Futures Slide as AI Financing Risks Persist Despite Strong Anthropic and TSMC Results: Dow Jones, S&P, Nasdaq

    US equity futures declined on Thursday as investors continued to reduce exposure to technology stocks amid concerns about artificial intelligence spending, corporate debt and the prospect of further monetary tightening by the Federal Reserve.

    Reports of substantial revenue growth at Anthropic (NASDAQ:ANTP) and record earnings from Taiwan Semiconductor Manufacturing Company (NYSE:TSM) provided evidence of continued demand for AI technology, but failed to offset broader concerns about valuations and financing costs.

    At 02:54 ET (06:54 GMT), Dow Jones futures gained 27 points, or 0.1%, while S&P 500 futures dropped 38 points, equivalent to 0.5%. Nasdaq 100 futures fell 407 points, or 1.4%.

    The moves followed Wednesday’s sharp decline on Wall Street, when stronger-than-expected US inflation figures triggered a rise in Treasury yields and increased expectations of a possible interest rate increase later this month.

    The S&P 500 and Nasdaq Composite both recorded their largest daily declines since July.

    Higher Borrowing Costs Put AI Investment Plans Under Scrutiny

    Investors have become increasingly concerned about the financial implications of the substantial capital expenditure required to develop artificial intelligence infrastructure.

    Technology companies are investing heavily in data centres, advanced computing equipment and related facilities, with some relying on significant borrowing to fund expansion.

    The latest US inflation figures intensified those concerns by increasing expectations that interest rates could remain elevated or rise further.

    Higher financing costs may place additional pressure on companies whose investment programmes depend on access to debt markets.

    US Treasury yields initially rose sharply following the inflation report, although the sell-off in government bonds moderated later in Wednesday’s session.

    Analysts suggested that the subsequent improvement in Treasury prices partly reflected a shift away from riskier AI-related investments towards government securities.

    CoreWeave (NASDAQ:CRWV) was among the companies most affected by the change in sentiment.

    Shares in the AI cloud infrastructure provider fell more than 15%, while some of its outstanding bonds declined to new lows in secondary trading.

    The movements reflected growing investor attention to the balance between expected AI revenue growth and the borrowing required to support infrastructure development.

    Anthropic Revenue Growth Slows Despite Reported 45% Increase

    Anthropic (NASDAQ:ANTP) reportedly disclosed third-quarter revenue of approximately $16.8 billion during a meeting with institutional investors on Wednesday.

    The figure represented a 45% increase from the previous quarter’s $11.6 billion, according to The Wall Street Journal.

    The publication reported that the developer of the Claude chatbot had generated less than $5 billion in revenue during the first quarter.

    Although the latest figures indicated continued strong demand for Anthropic’s products, they also suggested that its quarterly growth rate was moderating.

    Analysts at Vital Knowledge highlighted the contrast between the company’s reported performance and the unusually high expectations surrounding AI businesses.

    They observed that the growth would be impressive “in any normal world”, but that investors accustomed to exceptionally rapid expansion might respond negatively to signs of slowing momentum.

    “In the land of AI, where investors are used to parabolic figures, a slowdown in growth undercuts sentiment,” the analysts wrote.

    The reported results come amid speculation about a potential initial public offering by Anthropic.

    According to The Wall Street Journal, the company is considering raising as much as $100 billion at a valuation of approximately $2 trillion.

    The timing of any listing remains uncertain, although additional operational disclosures could emerge in IPO-related documentation over the coming weeks.

    TSMC Delivers Record Quarterly Earnings

    Taiwan Semiconductor Manufacturing Company (NYSE:TSM) reported a 69% increase in quarterly net profit to NT$763.06 billion for the three months ended 30 September.

    The result exceeded the NT$746.3 billion consensus estimate based on LSEG figures cited by Reuters.

    Revenue increased 50% year-on-year to NT$1.49 trillion, reflecting continued demand for advanced semiconductor manufacturing.

    The company reported a gross margin of 66.4%, an operating margin of 58.7% and a net profit margin of 51.1%.

    TSMC also indicated that it had considered additional manufacturing facilities in the United States, including a potential expansion into Texas.

    The plans reflect efforts to increase capacity as customers continue investing in the computing technology required for artificial intelligence applications.

    TSMC’s financial performance provided a contrast to the broader sell-off in AI-related shares.

    While semiconductor demand remained strong, investors continued to question whether all companies participating in the AI investment cycle would generate sufficient returns to justify their valuations and capital commitments.

    Producer Price Inflation Could Influence Fed Expectations

    Attention was also turning to the forthcoming US producer price index report for September.

    Economists expected producer prices for final demand to increase 0.6% from August, compared with the previous month’s 0.4% rise.

    Annual producer price inflation was forecast to ease slightly to 5.3% from 5.4%.

    The figures follow Wednesday’s consumer inflation report, which showed a larger-than-expected increase in prices amid higher energy costs linked to the conflict involving Iran.

    The inflation readings are expected to influence market expectations ahead of the Federal Reserve’s policy meeting on 27–28 October.

    Investors will also assess US retail sales and initial jobless claims data for further evidence of economic resilience and labour market conditions.

    Crude Oil Retreats as Traders Assess Shipping Disruptions

    Oil futures moved lower on Thursday despite continuing uncertainty surrounding energy shipments through the Middle East.

    At 03:35 ET, Brent crude futures declined 1.9% to $104.02 per barrel, while West Texas Intermediate fell 1.1% to $94.04.

    According to Reuters, maritime officials reported that two commercial vessels had sunk near the Strait of Hormuz during the preceding 24 hours following separate projectile strikes.

    The incidents added to concerns about the security of energy shipments through one of the world’s most important maritime routes.

    Fighting involving Saudi Arabia and Houthi forces in Yemen has also raised questions about the safety of shipping through the Bab el-Mandeb Strait, which connects the Red Sea with the Gulf of Aden.

    Meanwhile, reports suggested that US President Donald Trump was considering easing sanctions affecting certain vessels associated with the so-called shadow fleet.

    These ships are used to transport oil and petroleum products from countries subject to sanctions, including Russia, Iran and Venezuela.

    A relaxation of restrictions could potentially reduce shipping costs and improve the movement of crude oil supplies.

    Nevertheless, continued geopolitical disruption has kept energy prices elevated, adding another source of uncertainty for inflation expectations and financial markets.

  • European Stocks Decline as US Inflation Data Triggers Global Technology Sell-Off: DAX, CAC, FTSE100

    European Stocks Decline as US Inflation Data Triggers Global Technology Sell-Off: DAX, CAC, FTSE100

    European stock markets moved lower on Thursday as a global sell-off in technology shares and higher-than-expected US inflation data weighed on investor sentiment, increasing concerns about interest rates and equity valuations.

    The pan-European Stoxx Europe 600 index declined approximately 0.35%, reversing its modest gains from Wednesday as semiconductor and other growth-oriented stocks came under pressure.

    Germany’s DAX fell 0.5%, while France’s CAC 40 declined 0.2%. London’s FTSE 100 slipped 0.1%, reflecting broader weakness across European equities.

    The declines followed selling on Wall Street that extended into Asian markets before reaching Europe, with technology companies particularly affected by renewed concerns about borrowing costs and the outlook for artificial intelligence-related investments.

    Semiconductor Stocks Lead European Market Declines

    European semiconductor companies recorded some of the largest losses during Thursday’s trading, reversing the improvement in sentiment that followed ASML Holding’s third-quarter results a day earlier.

    ASML Holding (EU:ASML) shares fell 6.4%, despite the company’s previously announced outlook for stronger fourth-quarter sales.

    ASM declined 9.8%, while STMicroelectronics (BIT:STMMI) lost 7.1%. German semiconductor manufacturer Infineon (TG:IFX) fell 8.6%.

    BE Semiconductor Industries (EU:BESI) was also among the companies affected by the sector-wide sell-off, although the reported figures did not specify the size of its decline.

    The weakness extended beyond semiconductor manufacturers to equipment suppliers and other technology businesses, as investors reassessed valuations following the latest US inflation figures.

    ASML’s third-quarter announcement had initially provided some support to European technology shares on Wednesday. However, the improvement proved temporary as broader economic concerns returned to the forefront.

    US Inflation Data Raises Concerns About Interest Rates

    The market decline followed the release of US consumer price data showing that headline inflation accelerated to 3.7% year-on-year, while core inflation reached 2.6%.

    The figures prompted a reassessment of interest rate expectations, contributing to higher US government bond yields and increased pressure on technology stock valuations.

    The benchmark US 10-year Treasury yield rose to 5.266%, according to the market figures cited during the session.

    Higher government bond yields can make equities less attractive relative to fixed-income investments, particularly for growth-oriented companies whose valuations depend heavily on expectations of future earnings.

    The resulting pressure was particularly evident in semiconductor and technology shares, which have attracted substantial investor interest amid increased spending on artificial intelligence infrastructure.

    The latest inflation figures also added to uncertainty about the Federal Reserve’s future monetary policy decisions.

    European Earnings Season Provides Mixed Signals

    Investors were also assessing early third-quarter corporate results for indications of how European companies are performing amid elevated financing costs and uncertain consumer demand.

    French luxury goods group LVMH (EU:MC) reported weaker-than-expected third-quarter sales earlier in the week, raising concerns about demand in China and the outlook for discretionary consumer spending.

    The results added to uncertainty surrounding the luxury sector, which remains sensitive to changes in consumer confidence and economic conditions in major international markets.

    Meanwhile, ASML’s quarterly update provided a more positive near-term outlook for semiconductor equipment demand, supported by its fourth-quarter sales forecast.

    However, the company also narrowed its full-year 2026 sales target, highlighting differences in demand trends between AI-related applications and other semiconductor markets.

    The contrasting company updates illustrated the uneven performance emerging during the European reporting season.

    Bond Yields and Economic Uncertainty Weigh on Equities

    Elevated borrowing costs remained a concern for European equity investors as central banks continued to assess persistent inflationary pressures.

    European Central Bank President Christine Lagarde has maintained a cautious position on monetary policy and rejected suggestions that the ECB would intervene specifically to support French sovereign debt.

    Government bond yields and differences in borrowing costs across eurozone countries have remained important considerations for investors assessing equity valuations.

    Higher financing costs can affect corporate profitability, investment decisions and the relative attractiveness of shares compared with bonds.

    The latest market movements also reflected uncertainty surrounding energy prices and geopolitical developments, which continue to influence inflation expectations.

    European equities therefore remained sensitive to economic data and company earnings announcements, with Thursday’s decline demonstrating the impact of changing interest rate expectations on technology stocks and wider market sentiment.

  • FTSE 100 Edges Higher as UK GDP Growth Exceeds Forecasts Despite US Inflation Concerns

    FTSE 100 Edges Higher as UK GDP Growth Exceeds Forecasts Despite US Inflation Concerns

    The FTSE 100 edged higher on Thursday as stronger-than-expected UK economic growth figures provided support for London equities, despite weakness in global technology stocks, higher US inflation and continued tensions in the Middle East.

    London’s benchmark index gained 0.06% by 08:25 BST, while European markets recorded mixed performances. France’s CAC 40 advanced 0.05%, while Germany’s DAX declined 0.40%.

    Sterling strengthened against the US dollar, rising 0.44% to $1.3250 following the release of UK economic data that exceeded market expectations.

    UK Economy Grows 0.1% in August

    Figures published by the Office for National Statistics showed that the UK economy expanded by 0.1% in August, compared with economists’ expectations for a 0.1% contraction.

    Growth over the three months to August reached 0.7%, exceeding forecasts of 0.5%, while annual economic growth stood at 2.1%.

    The figures provided an indication of economic activity ahead of the government’s forthcoming Budget, as policymakers assess the outlook for growth, public finances and inflation.

    ONS economic statistics director Liz McKeown identified computer programming as the largest contributor to growth over the three-month period.

    The stronger-than-expected figures coincided with an increase in sterling, although the FTSE 100’s advance remained limited amid broader international market uncertainty.

    US Inflation Adds to Interest Rate Concerns

    Global equity markets remained under pressure following the release of US consumer inflation figures that exceeded expectations.

    US core consumer price inflation increased by 0.3% in September, compared with forecasts for a 0.2% rise.

    The data contributed to concerns that persistent inflation could influence the Federal Reserve’s future interest rate decisions, including the possibility of further monetary tightening.

    Technology shares were particularly affected by the wider market sell-off, with weakness in Asian semiconductor stocks adding to pressure on international equities.

    The inflation figures also provided a contrasting backdrop to the stronger UK economic data, leaving European stock markets mixed during early trading.

    Strait of Hormuz Disruption Continues Amid Middle East Conflict

    Developments in the Middle East remained a focus for commodity and financial markets as attacks on commercial shipping continued near the Strait of Hormuz.

    Two vessels reportedly sank near the strategic shipping route, while maritime security incidents disrupted commercial traffic.

    The United Kingdom Maritime Trade Operations organisation recorded 15 attacks between 6 October and 14 October, the highest reported frequency since the conflict began in February.

    Shipping data from Kpler indicated that approximately 2.9 million barrels of oil passed through the Strait of Hormuz on 11 October, compared with nearly 20.8 million barrels on 8 October.

    Iranian Parliament Speaker Mohammad Bagher Ghalibaf said Tehran did not seek an indefinite conflict or prolonged negotiations with the United States but would continue military operations until its demands were met.

    US President Donald Trump, speaking at a rally in Bullhead City, Arizona, claimed that Washington had established control over the strait and suggested that the conflict could end soon.

    US Central Command has also stated that American forces control the waterway, while Iran has accused Washington of imposing a blockade on its ports.

    Separately, attacks attributed to Houthi forces have affected airports in Saudi Arabia.

    The International Monetary Fund warned that Gulf economies were unlikely to return quickly to their economic trajectories before the conflict.

    The competing claims and continuing disruptions have contributed to uncertainty over regional security and energy transportation.

    Oil Prices Decline While Gold Advances

    Oil prices moved lower during Thursday’s trading despite the continuing disruption to shipping in the Middle East.

    Brent crude futures declined 1.83% to $104.07 per barrel, while West Texas Intermediate crude fell 1.24% to $93.91 per barrel.

    Precious metals moved in the opposite direction, with gold futures rising 1.38% to $4,164.80 an ounce.

    Spot gold increased 0.93% to $4,143.26 an ounce as investors assessed inflation developments, geopolitical risks and the outlook for monetary policy.

    The contrasting movements in oil and gold reflected differing trading conditions across commodity markets during the session.

    UK Corporate News

    TotalEnergies (LSE:TTE) said it expects its third-quarter refining margin to increase to $33.20 per barrel, compared with $8.40 in the corresponding period last year. The energy group attributed the improvement to changes in global energy supply conditions associated with the conflict involving Iran.

    Jupiter Fund Management (LSE:JUP) reported third-quarter net inflows of £700 million, compared with £300 million a year earlier. Assets under management increased 51% to a record £75.9 billion.

    Travis Perkins (LSE:TPK) reported a 1.3% decline in third-quarter like-for-like sales, reflecting subdued construction activity and weaker consumer demand. The building materials distributor continues to operate against a challenging backdrop in the UK construction market.

    British Land (LSE:BLND) said it expects first-half underlying profit and rental income to increase, supported by demand for London office space and retail parks, alongside cost savings. The property group indicated that these factors were helping offset higher interest costs and reduced lease surrender premiums.

    Dunelm (LSE:DNLM) reported a 1.1% increase in first-quarter sales to £433 million and maintained its full-year profit outlook. However, the home furnishings retailer warned that first-half profit was expected to decline compared with the corresponding period last year.

    The FTSE 100’s modest advance followed a combination of stronger domestic economic data and company-specific trading updates, while US inflation, weakness in technology stocks and developments in the Middle East continued to influence market sentiment.

  • EasyJet Shares Rise as £5.7 Billion Apollo Takeover Advances Towards Shareholder Vote

    EasyJet Shares Rise as £5.7 Billion Apollo Takeover Advances Towards Shareholder Vote

    EasyJet (LSE:EZJ) shares rose on Thursday after the airline confirmed that its proposed £5.7 billion acquisition by Apollo Global Management (LSE:JUP) remains on schedule for completion before the end of the first quarter of 2027.

    The budget airline’s shares traded at 684.6p during the session, approaching their 52-week high, following the publication of a scheme document setting out the terms and timetable of the recommended cash offer.

    The document outlines the next stages of the proposed acquisition, including shareholder approval, court proceedings and regulatory requirements that must be satisfied before the transaction can complete.

    EasyJet has scheduled court and shareholder meetings for the week beginning 9 November 2026, with voting expected to take place on 11 November.

    The meetings will allow shareholders to consider the proposed transaction and form part of the court-sanctioned scheme of arrangement through which the acquisition is intended to proceed.

    If completed, the deal would result in EasyJet leaving the London Stock Exchange after more than 25 years as a publicly traded company.

    European Airline Ownership Rules Remain a Key Consideration

    One of the principal outstanding issues concerns compliance with European aviation ownership and control requirements.

    EasyJet and Apollo are working to demonstrate to aviation regulators that the proposed ownership arrangements would preserve the airline’s majority European ownership and effective control.

    European aviation regulations impose ownership and control conditions on airlines operating under relevant European licences, making the proposed structure an important element of the approval process.

    The companies must satisfy regulators that EasyJet would continue to meet the applicable requirements following completion of the acquisition.

    The proposed transaction therefore remains subject to regulatory considerations in addition to the shareholder and court approvals required under the scheme.

    European Employee Representatives Raise Concerns

    The scheme document also identifies objections to the proposed acquisition from employee representatives across Europe.

    According to the document, several unions have expressed concerns about the transaction, while EasyJet’s European Works Council has opposed the proposed takeover.

    The Works Council cited concerns over the employment commitments offered in connection with the acquisition, which it said covered a period of 12 months and were not legally binding.

    The objections introduce an additional issue for the companies as they progress the transaction, although the supplied update does not indicate that they have altered the expected completion timetable.

    Completion Targeted for First Quarter of 2027

    EasyJet continues to expect the acquisition to complete before the end of the first quarter of 2027, subject to the necessary approvals and satisfaction of the transaction conditions.

    The immediate next stage is the shareholder vote scheduled for 11 November, followed by the remaining court and regulatory processes.

    The publication of the scheme document provides shareholders with further information ahead of the meetings and establishes the timetable for consideration of Apollo’s recommended offer.

    Completion would transfer EasyJet into private ownership and end its listing on the London Stock Exchange.

    However, the transaction has not yet been completed, and its final timetable remains dependent on the required approvals, including the resolution of European aviation ownership and control requirements.

    About EasyJet

    EasyJet (LSE:EZJ) is a UK-based low-cost airline operating passenger services across Europe and other destinations within its route network.

    The airline provides scheduled air travel services through a network of airports, serving leisure and business passengers.

    Its operations are subject to aviation safety, licensing and regulatory requirements, including applicable airline ownership and control rules.

  • Anglo Asian Mining Reports Q3 Copper Production of 5,514 Tonnes and Reaffirms 2026 Guidance

    Anglo Asian Mining Reports Q3 Copper Production of 5,514 Tonnes and Reaffirms 2026 Guidance

    Anglo Asian Mining (LSE:AAZ) has reported copper production of 5,514 tonnes for the third quarter of 2026, supported by increased output from its Demirli mine in Azerbaijan, while maintaining its full-year production guidance for copper, gold and silver.

    The AIM-listed mining company said copper production for the first nine months of 2026 reached 14,354 tonnes, its highest reported output for a nine-month period.

    The increase reflects the continued ramp-up of operations at Demirli, which forms part of Anglo Asian Mining’s strategy to expand copper production across its portfolio.

    The company is transitioning towards a production mix in which copper accounts for the majority of its output, alongside its existing gold and silver operations.

    Gold and silver production remained broadly unchanged compared with the corresponding period last year, according to the company’s quarterly operational update.

    Anglo Asian Mining also confirmed that mining activities had resumed at the Ugur deposit, adding to production operations across its Azerbaijan assets.

    Copper Concentrate Sales Generate $80.5 Million

    The company reported sales of 28,987 tonnes of copper concentrate during the third quarter, generating revenue of $80.5 million.

    The sales figures reflect the increasing contribution of copper to the group’s operations as production at Demirli continues to expand.

    Anglo Asian Mining also sold 5,733 ounces of gold bullion during the quarter, with average realised gold prices substantially higher than in the comparative period.

    The company did not specify the average realised gold price in the supplied update.

    Copper concentrate sales and gold bullion transactions remain principal sources of revenue for the group as it develops its production portfolio.

    Cash Balance Reaches $56.5 Million

    Anglo Asian Mining ended the third quarter with a cash balance of $56.5 million, following a net cash outflow during the reporting period.

    The company attributed the cash movement to dividend distributions, tax payments and temporary working capital requirements.

    In addition to its reported cash holdings, Anglo Asian Mining held unsold inventory valued at approximately $27.0 million at the end of the quarter.

    The inventory represents material available for future sale, subject to processing, commercial arrangements and prevailing market conditions.

    The company continues to manage its cash resources and working capital requirements alongside production activities and investment in its mining operations.

    Full-Year Production Guidance Maintained

    Following the third-quarter operational performance, Anglo Asian Mining reaffirmed its existing 2026 production guidance for copper, gold and silver.

    The company said the continued increase in production at Demirli remains a central component of its operational plans for the remainder of the year.

    The resumption of mining at Ugur also forms part of the group’s wider programme to develop and operate multiple mineral deposits in Azerbaijan.

    Anglo Asian Mining is pursuing a strategy to become a mid-tier, multi-asset copper and gold producer by 2030.

    The company’s development plans include bringing additional mines into production and increasing the contribution from copper across its portfolio.

    The third-quarter update reflects higher copper output, increased concentrate sales and continued investment in mining operations, alongside cash outflows associated with dividends, taxation and working capital.

    Management continues to target its previously announced production levels for 2026 while progressing the development of its mining assets.

    About Anglo Asian Mining

    Anglo Asian Mining (LSE:AAZ) is an AIM-listed mining company engaged in the production and exploration of copper, gold and silver in Azerbaijan.

    The group operates a portfolio of mining and development assets, including the Demirli mine and the Ugur deposit.

    Its activities encompass mineral extraction, processing, concentrate production and precious metals sales.

    Anglo Asian Mining is implementing a development strategy intended to expand its production base and establish the company as a mid-tier, multi-asset copper and gold producer by 2030.

    The strategy includes increasing copper output, developing additional mining operations and continuing exploration across its mineral portfolio.

  • Entain Reports 2% Rise in Q3 Net Gaming Revenue and Maintains FY26 EBITDA Guidance

    Entain Reports 2% Rise in Q3 Net Gaming Revenue and Maintains FY26 EBITDA Guidance

    Entain plc (LSE:ENT) has reported a 2% increase in group net gaming revenue (NGR) for the third quarter of 2026, supported by growth in its UK and Ireland operations, while trading in Brazil and customer-favourable sports betting results affected performance in other markets.

    The international sports betting and gaming group recorded 3% growth in online NGR during the period, with gaming activity contributing to revenue growth despite the impact of sports results that favoured customers.

    Entain’s UK and Ireland business reported an 8% increase in overall NGR, including 14% growth in online revenue.

    The company said the performance reflected increased activity across its domestic operations and contributed to market share gains during the quarter.

    Online operations in New Zealand, Spain and Canada also recorded double-digit revenue growth, providing additional contributions to the group’s international trading performance.

    However, Entain reported a substantial decline in Brazil, which offset part of the growth achieved elsewhere in the business.

    The company also identified customer-favourable sports betting outcomes as a factor affecting revenue during the quarter.

    Full-Year 2026 Guidance Maintained

    Following the third-quarter trading performance, Entain reaffirmed its financial guidance for the year ending December 2026.

    The group continues to expect online net gaming revenue growth of between 4% and 6% for the full year.

    Underlying EBITDA is forecast to be towards the lower end of the previously announced range of £910 million to £960 million.

    The guidance reflects management’s current expectations for trading across its online and retail businesses, including the effects of differing market conditions and sports betting results.

    Entain also confirmed that BetMGM, its US joint venture, expects its full-year revenue and EBITDA to be towards the lower end of its respective guidance ranges.

    The supplied update did not specify the monetary values of BetMGM’s guidance ranges.

    Central and Eastern European Portfolio Restructuring

    Entain reported further progress in its planned phased withdrawal from Central and Eastern European (CEE) operations.

    The group confirmed a divestment involving a 20% ownership stake as part of its strategy to reduce its exposure to the region.

    The transaction forms part of Entain’s wider portfolio management activities, which include reviewing its geographical operations and allocating resources across its remaining markets.

    The company did not provide additional financial terms or a detailed timetable for completing the wider CEE exit in the supplied update.

    UK Gambling Tax Developments

    Entain also addressed the potential implications of further increases in UK gambling taxation.

    Management warned that additional tax rises could affect the financial viability of retail betting shops, particularly where operating costs and tax obligations increase relative to revenue.

    The company operates a substantial retail betting estate in the United Kingdom, alongside its online sports betting and gaming businesses.

    Entain said changes to the UK gambling tax framework could influence the economics of its retail operations and future business decisions.

    The group continues to monitor regulatory and fiscal developments while maintaining its existing financial guidance.

    Management also reiterated its focus on long-term cash generation, supported by the group’s online operations, retail network and international gaming activities.

    The third-quarter update reflects revenue growth in several markets, particularly the UK and Ireland, alongside lower revenue in Brazil and the impact of customer-favourable sports results.

    About Entain plc

    Entain plc (LSE:ENT) is an international sports betting and gaming company operating online and retail businesses across the United Kingdom, Ireland and other international markets.

    The group’s activities include sports wagering, online casino gaming and retail betting services.

    Entain operates through a portfolio of consumer brands and maintains a presence in regulated gambling markets.

    Its operations also include BetMGM, a joint venture focused on the United States sports betting and gaming market.

    The company’s business strategy encompasses digital gaming operations, retail betting, regulatory compliance and the management of its international portfolio.

  • Travis Perkins Reports 1.6% Decline in Q3 Revenue as UK Construction Demand Remains Subdued

    Travis Perkins Reports 1.6% Decline in Q3 Revenue as UK Construction Demand Remains Subdued

    Travis Perkins plc (LSE:TPK) has reported a 1.6% decline in group revenue for the third quarter of 2026, reflecting reduced activity across parts of the UK construction market, particularly the new-build residential sector.

    The building materials distributor said trading conditions remained affected by macroeconomic uncertainty, with lower construction volumes influencing demand across its Merchanting businesses.

    The group continues to focus on managing profitability through pricing measures, cost controls and adjustments to its customer and product mix.

    Within Merchanting, Travis Perkins is prioritising higher-margin trade while maintaining credit risk management measures in response to current market conditions.

    The company said its businesses have continued passing through input cost inflation where appropriate, helping to offset some of the effects of lower sales volumes on profitability.

    However, demand across the construction sector remains subdued, with the new-build residential market identified as a particular area of reduced activity.

    The group is also continuing to manage its exposure to customer credit risk, alongside measures intended to maintain operating margins during the period of lower market activity.

    Toolstation UK Records Revenue Growth

    Trading performance differed across Travis Perkins’ Toolstation operations during the third quarter.

    Toolstation UK reported revenue growth during the period, with the business continuing its expansion programme in line with management’s expectations.

    The division supplies tools, building materials and related products to professional tradespeople and other customers through its retail and distribution network.

    In contrast, Toolstation Benelux continued to experience trading pressures, prompting the group to undertake a strategic review of the business.

    The review is intended to assess the challenges facing the Benelux operations and determine potential measures to address their performance.

    Travis Perkins has not disclosed the potential outcomes of the review or provided a timetable for any resulting decisions in the supplied update.

    Cost Management and Cash Flow Remain Priorities

    Alongside its divisional trading activities, Travis Perkins is continuing to implement cost management and operational efficiency measures across the group.

    The company said these initiatives are intended to support profitability, improve free cash flow generation and maintain its financial position.

    Management remains focused on balancing operating costs with current trading volumes while maintaining the group’s ability to serve customers across its Merchanting and Toolstation businesses.

    The measures include ongoing efforts to improve operational efficiency and manage expenditure in response to conditions in the UK construction market.

    Travis Perkins also continues to monitor input cost inflation and customer demand, particularly within the residential construction and repair, maintenance and improvement sectors.

    The group expects to provide a more detailed update on its strategy alongside its preliminary financial results in March 2027.

    The third-quarter trading update reflects differing performances across the business, with revenue growth at Toolstation UK contrasting with lower construction-related demand in Merchanting and continued trading pressures at Toolstation Benelux.

    About Travis Perkins plc

    Travis Perkins plc (LSE:TPK) is a UK-based distributor of building materials, tools and associated products serving professional tradespeople and construction customers.

    The group operates through its Merchanting businesses and Toolstation retail network, supplying products used in residential and commercial construction, refurbishment and property maintenance.

    Its activities cover the new-build construction and repair, maintenance and improvement markets.

    Toolstation operates in the United Kingdom and the Benelux region, providing tools, accessories and building supplies through its retail and distribution operations.

    Travis Perkins focuses on building materials distribution, trade customer services and operational efficiency across its businesses.

  • MedPal AI Reports Over 42,500 New Health Customers as Mounjaro Supply Ranking Reaches 29th in UK

    MedPal AI Reports Over 42,500 New Health Customers as Mounjaro Supply Ranking Reaches 29th in UK

    MedPal AI plc (LSE:MPAL) has reported that its New Health weight management business has exceeded 42,500 customers, while rising to 29th place among UK Mounjaro suppliers by volume, according to rankings provided by pharmaceutical company Eli Lilly.

    The company said New Health had moved from 3,048th position in July 2026 to 29th place within approximately three months, following the launch of its initial marketing campaign in July.

    The latest customer figure compares with more than 33,000 reported at the end of September 2026, reflecting continued growth in the business’s customer base during October.

    Based on an estimated UK market of approximately two million people using GLP-1 weight management medications, MedPal AI calculates that New Health accounts for around 2.1% of the market.

    The estimate draws on information submitted by Novo Nordisk to the House of Commons Health and Social Care Committee in August 2025, which indicated that more than 90% of UK patients using GLP-1 medications for weight management obtained their treatment privately.

    MedPal AI said the latest Eli Lilly rankings place New Health among the UK’s 30 largest Mounjaro providers by supply volume. The rankings measure the volume of medication supplied rather than revenue, earnings or profitability.

    The company’s directors consider the improvement in its ranking an indication of New Health’s rate of expansion within the UK private weight management market.

    Repeat Orders Increase to More Than 30% of Revenue

    MedPal AI also reported an increase in the proportion of New Health revenue generated from repeat customer orders.

    Repeat purchases now account for more than 30% of revenue, compared with 22% in September 2026.

    The company said the increasing contribution from returning customers is relevant to its operating model because repeat purchases do not carry the same direct customer acquisition costs as initial orders.

    The change in revenue composition follows the expansion of New Health’s customer base and the continued use of its prescription and fulfilment services by existing customers.

    Chief Executive Jason Drummond attributed the increase in repeat-order activity partly to the company’s customer acquisition strategy and its underlying Health OS technology platform.

    The company has not disclosed the profitability of New Health’s operations or the financial contribution associated with the increase in repeat orders.

    Expanded Fulfilment Facility Targeted for October

    To accommodate higher prescription volumes, MedPal AI is preparing to open an enlarged GLP-1 fulfilment line at its Sarus Court facility.

    The company expects the expanded operation to become operational by the end of October 2026, increasing its processing capacity to 14,000 orders per day.

    The additional infrastructure is intended to support New Health’s existing prescription activity and provide capacity for further increases in customer orders.

    The planned expansion forms part of MedPal AI’s investment in pharmacy fulfilment and technology infrastructure supporting its digital healthcare operations.

    Drummond reiterated management’s objective of establishing New Health among the UK’s three largest GLP-1 providers.

    This remains a company target, with future progress dependent on customer acquisition, retention, fulfilment capacity and trading conditions.

    The latest update follows New Health’s expansion since July, with the company reporting increases in customer numbers, Mounjaro supply volumes and the proportion of revenue generated from repeat orders.

    MedPal AI’s immediate operational priorities include commissioning the enlarged Sarus Court fulfilment line and continuing the development of its Health OS platform.

    About MedPal AI plc

    MedPal AI plc (LSE:MPAL) is a UK digital healthcare and pharmacy group combining pharmacy services, online healthcare operations and artificial intelligence-based technology.

    Its businesses include NHS Distance Selling Pharmacy hubs, the New Health GLP-1 weight management service and a business-to-business pharmacy supply operation serving care homes.

    The group also develops eMARx electronic medication administration record software and Juno, an artificial intelligence-based health companion.

    MedPal AI is developing its Health OS platform to integrate pharmacy operations, healthcare services and digital technology across its businesses.

  • Dunelm Reports 1.1% Rise in Q1 FY27 Sales to £433 Million and Maintains Full-Year Profit Outlook

    Dunelm Reports 1.1% Rise in Q1 FY27 Sales to £433 Million and Maintains Full-Year Profit Outlook

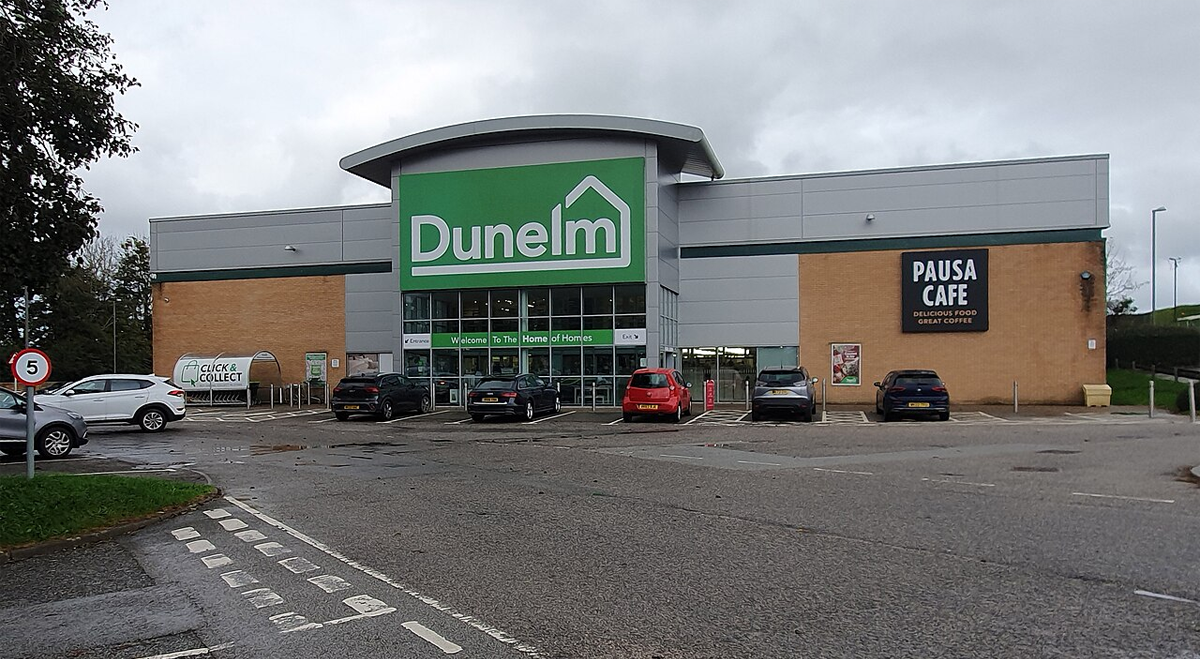
    Dunelm Group plc (LSE:DNLM) has reported a 1.1% increase in sales to £433 million for the first quarter of its 2027 financial year, with trading improving during the latter part of the period following an initially slower start.

    The UK homewares retailer attributed the early trading slowdown partly to exceptionally warm weather, which affected demand across certain product categories.

    Store-enabled like-for-like sales declined by 0.8% compared with the corresponding period last year, while total sales increased, reflecting contributions from the group’s wider retail operations.

    Dunelm reported a 10 basis point improvement in gross margin during the quarter, supported in part by favourable foreign exchange movements.

    The company said its sales performance continued to exceed that of the wider homewares market, which it characterised as subdued during the reporting period.

    Trading varied across product categories, with made-to-measure services recording double-digit sales growth.

    The cook-and-dine category also benefited from recent product range reviews and the introduction of updated merchandise, according to the company.

    Digital sales accounted for 41% of total revenue during the quarter, an increase of one percentage point compared with the same period last year.

    The higher digital contribution reflects continued activity across Dunelm’s online shopping, home delivery and Click & Collect services, which operate alongside its physical store network.

    Customer satisfaction scores improved by 0.5 percentage points during the period, according to the retailer’s reported measures.

    Alongside its trading activities, Dunelm continued implementing its Winning Hearts & Homes strategy, which includes investment in stores, digital capabilities and operational processes.

    The group progressed its store renewal programme and new store openings, including a substantial refurbishment of its Doncaster location.

    Dunelm also expanded the use of radio-frequency identification (RFID) technology across selected product categories, with the aim of improving inventory visibility, stock availability and operational efficiency.

    In addition, the company introduced artificial intelligence-enabled tools within its customer contact centre to support customer service operations.

    The investments form part of Dunelm’s programme to integrate its physical retail network with digital services and improve internal operating processes.

    Looking ahead, management maintained its expectations for adjusted profit before tax for FY27, which is forecast to remain broadly in line with the previous financial year.

    The company expects first-half profitability to be lower than the corresponding period last year, with the anticipated financial benefits from its strategic initiatives weighted towards the second half.

    Dunelm said it remains focused on implementing its store, digital and operational investment programmes while monitoring trading conditions across the UK homewares market.

    About Dunelm Group plc

    Dunelm Group plc (LSE:DNLM) is a UK homewares retailer offering furniture, bedding, curtains, blinds, kitchenware, lighting and home accessories, alongside specialist made-to-measure services.

    Founded in 1979 and headquartered in Leicester, the company operates 204 stores across the UK and Ireland and employs approximately 12,000 people.

    Its retail operations combine physical stores with online shopping, home delivery, Click & Collect services and the Dunelm mobile application.

    The group’s product offering consists predominantly of own-brand merchandise across a range of home furnishing and household categories.

    Dunelm’s Winning Hearts & Homes strategy focuses on developing its homewares offering, expanding digital capabilities, improving customer services and investing in operational technology.