British Land Company plc (LSE:BLND) has reported a 12% increase in like-for-like net rental income for the six months ended 30 September 2026, supported by leasing activity across its London campus properties and retail park portfolio.
The UK commercial property group expects underlying earnings per share (EPS) of 16.1p for the first half of its 2027 financial year, representing a 5% increase compared with the corresponding period last year.
British Land also reaffirmed its full-year guidance for underlying EPS growth of at least 6%, reflecting its expectations for rental income and operational performance across the portfolio.
Property valuations increased by 1.5% during the reporting period, alongside a 3% rise in estimated rental values (ERV), which measure the rental income properties could achieve under prevailing market conditions.
The company completed approximately 1.4 million square feet of leasing activity during the first half, with agreements secured at rents above both estimated rental values and previous contracted rental levels.
Its London campus portfolio recorded 25% like-for-like rental growth, reflecting leasing activity and rental adjustments across its office and mixed-use properties.
Meanwhile, occupancy across British Land’s retail park portfolio reached 99%, with the company continuing to report demand for space from retail occupiers.
Alongside its operational activities, British Land continued to adjust its property portfolio through acquisitions and disposals.
The group completed £247 million of asset sales during the period, with transactions taking place broadly in line with the properties’ reported book values.
British Land also acquired Telford Bridge Retail Park and completed its purchase of Life Science REIT, adding assets to its existing commercial property holdings.
The transactions form part of the company’s capital recycling strategy, which involves disposing of selected properties and reallocating proceeds towards assets aligned with its investment priorities.
British Land continues to concentrate its investment activities on London campuses and retail parks, using property development, leasing and asset management initiatives to support rental income and portfolio performance.
The company said its first-half results and current trading expectations support its existing forecast for at least 6% underlying earnings per share growth in FY27.
About British Land Company plc
British Land Company plc (LSE:BLND) is a UK commercial property investment and development company with a portfolio valued at approximately £15.8 billion.
The group’s principal activities focus on London office and mixed-use campuses, alongside retail parks across the United Kingdom.
British Land manages its properties through leasing, development, refurbishment and asset management programmes, while undertaking acquisitions and disposals as part of its portfolio strategy.
The company focuses on generating rental income and long-term property returns through its commercial real estate holdings, with investment decisions centred on occupier demand, asset performance and capital allocation.
Gulf Keystone Petroleum Ltd. (LSE:GKP) has confirmed receipt of its first allocation of top-up oil barrels from Iraq’s State Oil Marketing Organisation (SOMO), marking the commencement of payments intended to reconcile export revenues with international oil prices.
The allocation forms part of interim export arrangements established for international oil companies operating in the Kurdistan Region of Iraq. Under these agreements, additional oil barrels are provided to compensate producers for differences between their export sales proceeds and their contractual entitlements.
The first top-up cargo relates to Gulf Keystone’s oil exports from the fourth quarter of 2025 and represents an initial payment against the company’s outstanding top-up receivables.
According to Gulf Keystone, the mechanism is designed to align export sales entitlements with international oil prices, in accordance with amendments to Iraq’s federal budget law and the production-sharing contracts governing operations in the Kurdistan Region.
The company said the receipt of the first cargo represents progress in implementing the interim export arrangements between the relevant Iraqi and Kurdistan authorities and international oil producers.
Chief executive Jon Harris described the commencement of top-up payments as a milestone for Gulf Keystone and the wider Kurdistan oil industry.
Harris said the arrangements establish a mechanism for recognising producers’ contractual entitlements under the amended Iraqi budget framework and existing production-sharing agreements.
The company also indicated that implementation of the payment mechanism could support cooperation between the Kurdistan Regional Government and Iraq’s federal authorities, while providing greater clarity over export revenue arrangements for international operators.
Gulf Keystone continues to focus on the development of the Shaikan Field in the Kurdistan Region, where its operations are centred on oil production and the management of the field’s resource base.
The company considers the implementation of the top-up arrangements relevant to its ongoing development plans and the broader investment framework for oil production in Kurdistan.
The supplied announcement did not specify the volume or monetary value of the first top-up cargo, the total outstanding receivables or a timetable for further allocations.
About Gulf Keystone Petroleum Ltd.
Gulf Keystone Petroleum Ltd. (LSE:GKP) is an independent oil and gas exploration and production company focused on the Kurdistan Region of Iraq.
The company’s principal asset is the Shaikan Field, where it undertakes oil production and development activities.
Gulf Keystone is listed on the London Stock Exchange and the Oslo Stock Exchange under the ticker GKP.
Its operations are focused on developing the Shaikan Field’s oil resources and supplying production to export markets under the applicable contractual and regulatory arrangements.
Seraphim Space Investment Trust (LSE:SSIT) has increased its investment in Xona Space Systems, making the company its second-largest portfolio holding after ICEYE. Xona is developing next-generation satellite navigation technology designed to deliver greater accuracy, security and resilience as demand for reliable positioning data continues to grow.
The global space economy is evolving beyond traditional launch services and satellite communications into a broader range of critical infrastructure applications. Defence and national security, autonomous vehicles, robotics and industrial automation are among the sectors increasingly reliant on advanced space technology.
For Seraphim Space Investment Trust, Xona represents an opportunity to gain exposure to a business developing technology with potential applications across multiple large and expanding markets.
Xona Becomes a Major Portfolio Holding
Following SSIT’s latest investment, its existing holding in Xona was valued at $106 million, equivalent to approximately £80.6 million at the exchange rate used for the valuation. A further $15 million investment through SSIT’s C share class brought the combined holding to $121 million, or approximately £91.9 million on the same basis.
This makes Xona SSIT’s second-largest portfolio company, highlighting the growing importance of positioning, navigation and timing technology within the global space economy.
Satellite navigation underpins a wide range of modern applications, from everyday transport and logistics to advanced industrial systems and defence capabilities. However, conventional GPS typically provides accuracy within approximately one to 10 metres, depending on conditions, and can be vulnerable to interference and spoofing.
These limitations create demand for alternative technologies capable of delivering greater precision and resilience, particularly in applications where dependable positioning information is essential.
Xona is developing a low Earth orbit satellite constellation designed to deliver centimetre-level positioning accuracy alongside enhanced resilience. Its technology aims to address the requirements of markets where increasingly sophisticated systems depend on precise, secure and reliable navigation.
Potential applications include autonomous vehicles, drones, robotics, defence modernisation, advanced mobility and industrial automation. As these technologies develop, accurate positioning data is becoming an increasingly important component of the infrastructure supporting them.
For SSIT, Xona illustrates the potential of investing in space technology businesses whose capabilities can serve several substantial markets rather than relying on a single application.
Xona also demonstrates Seraphim’s approach to identifying promising space technology companies and supporting their development as they mature.
Seraphim identified Xona at an early stage, supported the business through its accelerator programme and subsequently provided funding through its private space venture funds. As Xona progressed and reached a more advanced stage of development, Seraphim began investing through SSIT.
This approach enables Seraphim to build familiarity with businesses as they develop, with the objective of gaining exposure to companies that have demonstrated their technical capabilities and are increasingly focused on commercial growth.
SSIT’s investment strategy provides exposure to space technology companies at different stages of development, with an emphasis on businesses that Seraphim believes can address substantial market opportunities.
The progression of Xona highlights how early engagement and continued investment can provide exposure to companies developing technologies with the potential to become increasingly important to the wider economy.
C Share Portfolio Targets Mission-Critical Technologies
Beyond Xona, Seraphim continues to identify opportunities across an expanding space technology market.
Key areas of interest include defence and national security, resilient communications, positioning and navigation, Earth observation, climate intelligence and autonomous systems.
These markets reflect the growing recognition that space technology is no longer simply experimental or supplementary. Increasingly, it is becoming essential infrastructure for governments, businesses and critical industries.
SSIT is concentrating on later-stage, higher-growth companies that have demonstrated their technical capabilities and reduced much of their underlying technology risk. The focus is on businesses with the potential to translate technological progress into commercial traction and expansion.
Xona provides an example of this opportunity, combining a significant potential addressable market with technology designed to support several major growth trends.
As demand for resilient infrastructure increases, companies capable of delivering practical solutions across multiple applications could play an important role in the next phase of space sector development.
Continued Investment Across the Space Economy
SSIT’s C share portfolio is playing an important role in expanding the trust’s exposure to emerging opportunities.
Since May, SSIT has made significant investments through its C share class, with further capital deployment expected over the following quarter.
The emphasis remains on businesses considered strategically important, with growth potential and the ability to establish positions within the global space economy.
Governments and businesses are increasingly focused on improving resilience across navigation, communications and national security. At the same time, advances in autonomous systems, Earth observation and other space-enabled technologies are creating new commercial applications.
This combination of technological development and growing demand is broadening the range of potential investment opportunities across the sector.
For SSIT, continued capital deployment provides an opportunity to back businesses developing technologies that could become increasingly important to the global economy.
Positioning for the Next Phase of Space Technology
The developments at Xona highlight the expanding role of space infrastructure in everyday life and critical economic activity.
With SSIT’s combined Xona holding valued at $121 million following the latest investment, the trust has established a substantial position in a company developing technology for more precise and secure satellite navigation.
Alongside this investment, the continued deployment of capital through SSIT’s C share portfolio reflects the trust’s ambition to identify and support the next generation of space technology businesses.
As the sector expands across defence, autonomous systems, communications and Earth observation, SSIT is seeking to provide investors with exposure to companies developing technologies that could help shape the future of the global space economy.
FTSE 100 flat as DAX gains ahead of US CPI; Great Portland Estates lifts London rents, Thor Explorations trims guidance and copper edges higher.
Market Overview
European markets opened mixed and cautious as investors waited for US September inflation data. The FTSE 100 was little changed, slipping 0.0033 per cent to 10,649.97, while the Euronext 100 edged up 0.0317 per cent to 1,859.18. The DAX was the stronger performer, opening 0.4934 per cent higher at 25,384.54 after a recent technical breakout, although resistance remains just above current levels. In the US, the Nasdaq 100 closed 0.3105 per cent lower at 30,569.48 and the S&P 500 finished down 0.02 per cent at 7,805.45. US headline CPI is expected to rise from 3.4 per cent, and markets fully price a Federal Reserve rate rise in December. In the UK, Bank of England chief economist Huw Pill said he was sceptical that all of the rate rises priced by markets would be needed, and Governor Andrew Bailey said the pass-through of the energy shock to UK prices had so far been more subdued.
Commodities were mostly steady. Copper moved higher and natural gas edged up, while gold was flat. Brent crude dipped slightly but stayed inside its recent trading range. Fading hopes of a diplomatic breakthrough with Iran and continued disruption in the Strait of Hormuz kept energy markets in focus, although higher Iraqi exports offered some offset. Bitcoin traded modestly higher against sterling. Sterling was unchanged against the US dollar and the euro, slightly weaker against the Australian dollar and the yen, and fractionally firmer against the Swiss franc, as investors weighed the Bank of England’s rate path ahead of the US data.
Market Numbers
FTSE 100: Down (-0.003%), 10,649.97 Euronext 100: Up (+0.031%), 1,859.18 DAX: Up (+0.493%), 25,384.54 NASDAQ: Down (-0.310%), 30,569.48 S&P 500: Down (-0.02%), 7,805.45
In the Headlines
Lettings strength – Great Portland Estates (LSE:GPE) Great Portland Estates signed 40 leases and renewals worth £19.0 million in annual rent in the six months to 30 September, 4.1 per cent above March estimated rental values. It also completed its fully pre-let 30 Duke Street scheme in St James’s on time and on budget. The results point to continued demand for prime managed space in central London ahead of interim results in November.
Guidance trimmed – Thor Explorations (LSE:THX) Thor Explorations poured 15,515 ounces of gold at its Segilola mine in Nigeria in the third quarter and reported revenue of about US$81.7 million. Heavy rainfall led it to cut 2026 production guidance to 70,000–72,000 ounces. Cost guidance and the quarterly dividend were both maintained, which may help limit the impact of the lower output target on investor sentiment.
Currencies (vs GBP)
USD: Unchanged (0.00%), $1.3257 CHF: Up (+0.0009%), Fr.1.104 EUR: Unchanged (0.00%), €1.1835 JPY: Down (-0.0057%), ¥209.884 AUD: Down (-0.0084%), $1.8982 Bitcoin (BTC/GBP): Up (+0.29%), £62,868.62
Commodities
Copper: Up Gold: Unchanged Brent Crude: Down Natural Gas: Up
MAX Power Mining Corp. (CSE:MAXX), (USOTC:MAXXF) (FSE:89N) is strengthening its leadership team as it prepares for a pivotal phase of natural hydrogen testing at its Lawson discovery in Saskatchewan. With a large-scale geological system identified, independent technical modelling underway, a proprietary AI-assisted exploration platform in development and US capital markets opportunities under evaluation, the company is advancing its strategy to assess the commercial potential of natural hydrogen.
MAX Power is entering a significant new chapter in its development, appointing former Saskatchewan cabinet minister Rob Norris as Chief Executive Officer as it moves towards the next stage of technical evaluation and potential commercialisation.
The appointment comes as the company prepares to begin completions testing at its Lawson and Bracken discoveries in the second half of October 2026. The programme is intended to provide important information about the characteristics and potential commercial viability of the natural hydrogen systems identified through drilling.
Alongside the technical work, MAX Power is advancing its proprietary MAXX LEMI exploration platform, evaluating a potential US stock exchange listing and exploring strategic partnerships to support further development.
The company’s wider proposition combines a substantial permitted land position, a confirmed subsurface natural hydrogen system, associated helium potential and a technology-led approach to identifying additional exploration targets.
Experienced Leadership for the Next Phase
Rob Norris brings experience in government, energy policy, innovation and international partnerships to his new role. A former Saskatchewan cabinet minister, he has held responsibilities spanning SaskPower, innovation, advanced education and employment, giving him relevant experience as MAX Power seeks to develop its natural hydrogen opportunity within the province.
Norris has served on the company’s board since June 2025. His appointment as CEO follows Ran Narayanasamy’s transition to the newly created position of Managing Director, Innovation and International Strategy.
The move allows MAX Power to maintain continuity in its technical and strategic development while placing increased emphasis on commercialisation, partnerships and capital markets.
The company has also strengthened its technical leadership with the appointments of Tom Kishchuk as Chief Technology Officer and Dr Brendan Bishop as Chief Geochemist.
Kishchuk brings more than 30 years of technical and business leadership experience, while Bishop contributes specialist expertise in geochemistry and hydrogen and helium isotopes.
Together, the appointments strengthen the team’s commercial, technical and scientific capabilities as MAX Power prepares to evaluate the next stage of its discoveries.
Lawson: From Discovery Towards Commercial Evaluation
MAX Power’s flagship Lawson project represents the central focus of its natural hydrogen strategy.
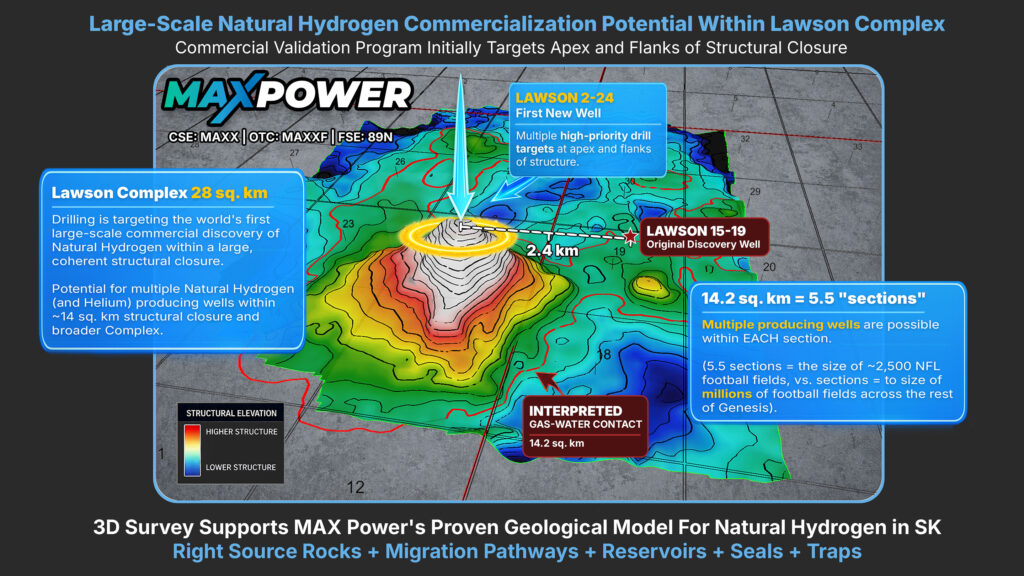
The company has confirmed a subsurface natural hydrogen system through deep drilling, with data validated by three independent laboratories. Subsequent three-dimensional seismic work has helped define the underlying geological structure, providing a framework for follow-up drilling and further assessment.
According to the company’s IBN profile, seismic interpretation has identified a 14.2-square-kilometre structural closure within a broader 28-square-kilometre system.
These findings provide a more detailed geological picture of the opportunity, moving the project beyond an isolated drilling result towards the evaluation of a larger subsurface system.
The next important milestone is completions testing, which is expected to help establish how the system performs under test conditions. Key considerations include hydrogen concentrations, flow rates, reservoir characteristics and deliverability.
The results will be important in assessing whether Lawson could support commercially viable production.
MAX Power has also reported significant natural hydrogen readings from its third and fourth Lawson wells, with the drilling programme aimed at understanding the scale and continuity of the system.
The company has engaged GLJ Ltd., an independent energy consulting firm, to undertake reservoir characterisation, modelling and development scenario analysis. This work is intended to help assess the broader Lawson Complex’s resource potential and provide a stronger technical foundation for future development decisions.
While commercial production has not yet been established, the combination of drilling, seismic interpretation and independent technical analysis represents an important stage in evaluating the discovery.
A 475-Kilometre Exploration Trend Creates Further Potential
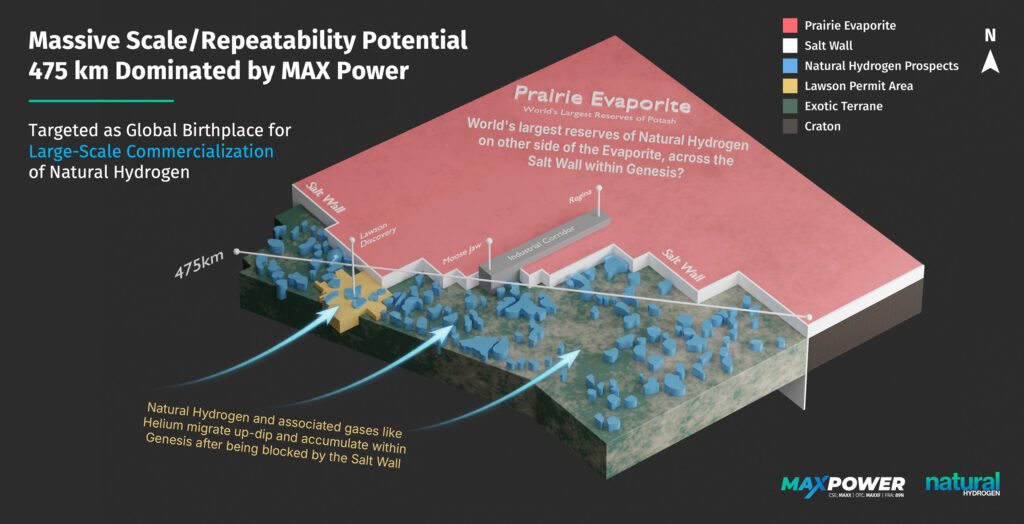
Beyond Lawson itself, MAX Power is investigating the potential of the broader Genesis Trend, a geological corridor extending approximately 475 kilometres through Saskatchewan towards North Dakota.
The company’s permitted land position has expanded to approximately 2.5 million acres, giving it a substantial area in which to investigate additional natural hydrogen targets.
The wider exploration strategy is based on determining whether geological features identified at Lawson can be recognised elsewhere along the trend and across other parts of the company’s acreage.
One important element is the Bracken target, located approximately 325 kilometres southwest of Lawson. Drilling at Bracken has identified multiple prospective natural hydrogen and helium zones, with further completions and testing planned.
Investigating both Lawson and Bracken provides an opportunity to assess natural hydrogen systems in different geological settings and determine whether the wider Saskatchewan land position could host additional discoveries.
MAX Power is also evaluating other targets, including Lawson South, as it continues to build its understanding of the region’s geology.
The potential significance is that successful follow-up work could expand the company’s opportunity beyond a single discovery. However, the scale, continuity and commercial viability of any additional accumulations will need to be established through further technical work.
Natural Hydrogen and the Emerging Energy Opportunity
Natural hydrogen is attracting increasing interest as energy users explore alternative sources of lower-emission energy for industrial applications and infrastructure.
Unlike manufactured hydrogen, which requires an industrial production process, natural hydrogen is generated through geological processes and may accumulate within the subsurface. If it can be discovered, extracted and delivered economically, it could offer an alternative source of energy for selected applications.
The potential economics are a key part of the industry’s appeal. Natural hydrogen could avoid some of the energy-intensive production requirements associated with manufactured hydrogen, although actual costs will depend on geology, extraction, processing, infrastructure and other project-specific factors.
MAX Power’s Lawson discovery is strategically positioned near Saskatchewan’s industrial corridor, where existing industrial activity and proposed hydrogen infrastructure could provide potential future demand.
The region is also attracting interest in energy-intensive infrastructure, including proposed AI and data-centre developments. Such projects could increase the importance of reliable energy supplies, although any future supply relationship involving MAX Power would depend on successful technical validation, commercial arrangements and the development of suitable infrastructure.
For MAX Power, the immediate priority remains demonstrating the performance of its natural hydrogen systems. Establishing commercially viable production would be a critical step towards turning the broader energy opportunity into a development proposition.
MAXX LEMI: Applying AI to Natural Hydrogen Exploration
A further differentiator is MAX Power’s proprietary MAXX LEMI platform, an AI-assisted geological exploration framework designed to integrate seismic information, drilling results, structural interpretation and historical subsurface datasets.
The objective is to improve the identification and assessment of potential drilling targets by bringing multiple sources of geological information into a unified analytical framework.
This approach could support the company’s exploration strategy by helping refine target selection, improve understanding of subsurface structures and assess similarities between known discoveries and prospective areas.
MAX Power has engaged global technology services provider Kyndryl to develop a commercialisation strategy and go-to-market plan for the platform.
The potential applications extend beyond the company’s own acreage. If the technology proves effective, MAXX LEMI could potentially have applications across other natural hydrogen exploration districts, creating opportunities for partnerships, licensing or broader commercial adoption.
The platform was also recognised as a runner-up in the Digital Innovator category at the 2026 Canadian Hydrogen Convention in Edmonton, according to the IBN company profile.
That recognition provides additional visibility for the technology as MAX Power explores how data-led targeting could contribute to a developing natural hydrogen industry.
The commercial opportunity remains to be demonstrated, but the platform adds a technology dimension to the company’s exploration strategy.
A Second Asset in Critical Minerals
MAX Power also holds a portfolio of critical minerals properties, including the Willcox Playa Lithium Project in southeast Arizona.
The company’s US subsidiary owns the project, where earlier diamond drilling identified lithium-rich clays over a broad area.
The asset provides exposure to a separate sector linked to battery materials and US critical minerals supply chains.
MAX Power is considering a proposed spinout of its critical minerals portfolio. If progressed, such a transaction could allow the company to sharpen its strategic focus on natural hydrogen while giving the separate assets a more dedicated development pathway.
Any potential spinout, its structure and its implications for shareholders would depend on the company’s plans and the relevant approvals and conditions.
The portfolio nevertheless represents an additional component of MAX Power’s asset base as it works to define its longer-term priorities.
Expanding Investor Reach and US Market Opportunities
Alongside its operational programme, MAX Power is evaluating a potential dual listing on a US stock exchange.
The objective would be to broaden the company’s investor base, improve visibility among US investors and potentially increase trading liquidity. Any listing would remain subject to exchange requirements, regulatory considerations and the company’s final decision.
The company has also entered into a syndicated communications agreement with InvestorBrandNetwork (IBN), effective 9 October 2026 for an initial 90-day period ending 7 January 2027.
The agreement is valued at US$500,000, payable in cash from working capital. The services include content creation and syndication, press release enhancement, recap-style coverage, a CEO podcast interview, social media support and monthly reporting.
The campaign is intended to raise awareness of MAX Power among investors as it progresses its natural hydrogen programme and evaluates capital markets opportunities. It is an investor communications initiative rather than evidence of technical progress or commercial validation, and the associated expenditure is a relevant consideration for shareholders.
Taken together, the company’s investor outreach and potential US listing form part of a broader effort to increase market awareness as the operational programme advances.
The Next Milestones
MAX Power’s latest leadership changes reflect a shift in emphasis towards commercial evaluation, with Lawson completions testing expected to provide an important next set of technical information.
The company is also progressing work at Bracken, assessing the wider Genesis Trend, developing its MAXX LEMI platform and considering how its capital markets strategy can support its ambitions.
The combination of a confirmed natural hydrogen system, a substantial permitted land position, associated helium potential and additional exploration targets gives MAX Power several avenues through which to pursue its strategy.
The key test now is whether the upcoming work can demonstrate the technical performance and commercial characteristics required to advance Lawson towards potential development.
For investors following the emerging natural hydrogen sector, the coming months could be important in determining how the company’s exploration results translate into a clearer picture of resource potential and possible commercial applications.
With a strengthened leadership team and several technical and corporate initiatives progressing in parallel, MAX Power is positioning itself for the next phase of its natural hydrogen journey.
The opportunity remains at the exploration and evaluation stage, and commercial production has not yet been established. Future progress will depend on testing results, technical assessments, financing, infrastructure and the ability to develop commercially viable projects.
NatWest (LSE:NWG) shares advanced on Tuesday after Barclays upgraded the UK banking group to “overweight” from “equal weight” and increased its price target, citing stronger earnings prospects supported by higher interest rates, business expansion and potential benefits from the acquisition of Evelyn.
The shares gained 3.3% to 675.20p in London trading, outperforming the FTSE 100, which rose approximately 0.7%.
Barclays raised its price target for NatWest to 850p from 740p, an increase of nearly 15%. The revised target represents potential upside of approximately 26% from the quoted share price.
Higher Interest Rates Expected to Support Earnings
Barclays identified NatWest as a potential beneficiary of higher UK interest rates and a steeper yield curve, which could improve the bank’s revenue and profitability over the coming years.
The analysts increased their long-term Bank Rate assumption by 50 basis points to 4.25%, estimating that the change could lift NatWest’s earnings per share by approximately 5% in 2028.
The positive effect could eventually reach 10% as the bank’s structural hedge matures and higher interest rates are progressively reflected in returns.
Barclays also increased its earnings-per-share forecasts by as much as 7% across 2026 to 2028, primarily reflecting expectations of stronger revenue generation.
However, the analysts acknowledged that increased competition for customer deposits could partially offset the benefits of higher interest rates.
Despite this risk, Barclays does not anticipate a repeat of the significant shift towards more expensive deposit products experienced in 2023.
The bank suggested that households may be approaching the point at which further transfers of savings into higher-cost fixed-term deposits become less likely, potentially limiting additional pressure on NatWest’s funding costs.
Barclays also highlighted potential earnings benefits from NatWest’s integration of Evelyn, the wealth management business acquired by the lender.
According to the analysts, the integration is progressing positively and could create opportunities to expand relationships with existing wealth management clients.
In particular, NatWest may be able to offer additional banking products and services to Evelyn customers, supporting revenue growth across the combined business.
Barclays suggested that these cross-selling opportunities could allow NatWest to generate revenue synergies above its existing expectations over time.
The acquisition represents another potential source of earnings growth alongside the bank’s core lending and deposit operations.
UK Banking Tax Risks Remain Ahead of Budget
While Barclays adopted a more positive outlook for NatWest, it acknowledged uncertainty surrounding possible changes to UK banking taxation ahead of the forthcoming Budget.
Any increase in taxes affecting the banking sector could create additional costs and place pressure on profitability.
However, Barclays expects the potential financial impact to remain manageable.
The analysts also suggested that much of the uncertainty surrounding possible tax changes is already reflected in NatWest’s current share price.
As a result, Barclays considers the bank’s valuation relatively attractive despite the outstanding policy risks.
Valuation Discount Supports Barclays’ Positive Outlook
Barclays pointed to NatWest’s valuation discount relative to European banking peers as another reason for its upgraded recommendation.
The analysts argued that the combination of stronger earnings forecasts, potential benefits from higher interest rates and additional revenue opportunities from Evelyn was not fully reflected in the lender’s market valuation.
The revised 850p price target incorporates Barclays’ more favourable expectations for NatWest’s earnings performance and longer-term growth prospects.
Although deposit competition and potential tax changes remain risks, Barclays considers the bank well positioned to benefit from its existing operations and wealth management expansion.
Tuesday’s share price increase reflected a positive market response to the upgrade, with NatWest outperforming the broader London equity market.
US equity futures showed contrasting movements on Tuesday as investors prepared for major bank earnings, assessed disappointing sales from luxury group LVMH and reconsidered the financial outlook for companies exposed to artificial intelligence.
Energy market developments and geopolitical tensions added to uncertainty, while upcoming US inflation figures remained an important consideration for expectations surrounding Federal Reserve interest rate policy.
At 02:48 ET (06:48 GMT), Dow Jones Industrial Average futures were up 225 points, or 0.4%. S&P 500 futures edged down six points, equivalent to 0.1%, while Nasdaq 100 futures dropped 237 points, or 0.8%.
The relative weakness of Nasdaq futures followed renewed selling among technology companies, particularly semiconductor manufacturers and businesses associated with large-scale AI infrastructure investment.
The main US stock indices had ended Monday’s session mixed, with investors responding to higher energy prices, questions about technology valuations and weaker-than-expected trading figures from LVMH.
Semiconductor Losses Highlight Uncertainty Over AI Spending
Artificial intelligence remained a significant influence on market sentiment after US semiconductor shares declined sharply at the beginning of the week.
A sector index tracking chip manufacturers lost 2.7% on Monday, reflecting growing investor caution about the relationship between substantial AI-related expenditure and future profitability.
Technology shares in South Korea subsequently experienced considerable selling pressure.
Reports of advances by Chinese memory chip producer ChangXin Memory Technologies contributed to concerns about the competitive position of established semiconductor manufacturers.
The developments raised questions about whether Chinese companies could make further progress in narrowing the technological gap with US suppliers.
Investor uncertainty has also been influenced by scrutiny of revenue expectations surrounding OpenAI, the company behind ChatGPT.
Demand for AI services and infrastructure remains strong, but investors are increasingly examining the returns that technology businesses may generate from their capital expenditure programmes.
Large technology companies are investing heavily in data centres, computing equipment and networking infrastructure, with debt financing contributing to some projects.
The scale of these commitments has prompted closer examination of future cash generation, operating margins and the period required for investments to become profitable.
Technology sector valuations may therefore remain sensitive to evidence of whether commercial AI adoption can generate sufficient revenue to support continued expansion.
LVMH Revenue Misses Forecasts as Fashion Division Contracts
LVMH (USOTC:LVMUY) came under pressure in Paris after reporting third-quarter sales that fell short of analysts’ estimates.
The luxury goods group generated revenue of €18.5 billion, representing a 1% organic increase from the corresponding quarter of the previous year.
The performance was below the 1.3% growth forecast in the Visible Alpha consensus cited by Reuters.
Results from the company’s fashion and leather goods division were particularly weak.
Organic revenue in the segment declined 5%, compared with expectations for a 1.8% fall.
The division accounts for approximately half of LVMH’s total revenue, making its performance an important measure of demand for the group’s core luxury brands.
Growth in watches and jewellery also slowed.
Regional figures showed a 5% year-on-year decline in Asian sales, with China remaining a significant source of weakness.
Luxury spending in the Chinese market has been affected by weaker consumer demand and increased tax scrutiny of wealthy individuals.
Higher costs associated with geopolitical developments have added further challenges for the sector.
The results raised questions about the strength of demand for premium products and the pace at which Chinese luxury consumption might recover.
LVMH’s performance could also influence market expectations for other European luxury companies preparing to publish financial updates.
US Banks Begin Quarterly Reporting Season
A series of earnings announcements from major US financial institutions was scheduled to begin later on Tuesday.
JPMorgan Chase (NYSE:JPM), Goldman Sachs (NYSE:GS), Wells Fargo (NYSE:WFC) and Citigroup (NYSE:C) were due to report third-quarter results.
Bank of America (NYSE:BAC), Morgan Stanley (NYSE:MS) and BlackRock (NYSE:BLK) were expected to follow on Wednesday.
The releases will provide investors with updated information about the profitability of lending activities, deposit costs, credit performance and investment banking revenue.
Higher government bond yields have become an important consideration for financial institutions because of their potential effect on asset valuations and net interest margins.
Analysts at Vital Knowledge indicated that banking results could broadly match expectations, while identifying several possible sources of pressure.
These included increased funding costs, volatility in financial markets and slower securities issuance, which could reduce fee income from capital markets activities.
The analysts also highlighted potential weakness in revenue associated with residential mortgages.
Investors will examine whether merger and acquisition activity, initial public offerings and other corporate financing transactions are contributing to investment banking earnings.
The results will also provide evidence about household and corporate borrowing conditions, particularly through credit loss provisions and loan performance.
Separately, Deutsche Bank forecast third-quarter earnings growth of 34% for the S&P 500.
Its analysts argued that market expectations may underestimate corporate earnings resilience.
“The consensus is once again assuming too sharp a slowdown, leaving room for another quarter in which companies exceed forecasts more frequently than usual,” the analysts said.
The start of the earnings season will therefore be an important test of whether corporate profitability can support current US equity market valuations.
Crude Oil Falls Following Russian Diesel Export Comments
Oil futures declined on Tuesday as the possibility of increased Russian diesel exports partially offset concerns about disruptions to energy supplies in the Middle East.
Brent crude fell 1.5% to $105.09 per barrel by 03:54 ET, while West Texas Intermediate dropped 1.8% to $92.08.
The retreat followed gains on Monday, when Brent reached its highest closing level since 15 September.
Russian Deputy Prime Minister Alexander Novak said the country could increase diesel exports beyond the volumes outlined in a supply agreement announced by US President Donald Trump.
The comments followed a temporary easing of US restrictions on Russian fuel.
Trump also announced an “energy ceasefire” between Russia and Ukraine, although reports of further strikes against Ukrainian energy infrastructure raised questions about the arrangement’s effectiveness.
Elsewhere, tensions in the Middle East continued to threaten regional energy transport.
Attacks attributed to Iran-backed Houthi forces against Saudi Arabia’s international airport and strikes involving tankers in the Strait of Hormuz contributed to concerns about the security of oil shipments.
The waterway is a critical route for international crude exports, making any interruption potentially significant for global supply.
While expectations of additional Russian exports weighed on prices, uncertainty surrounding Middle Eastern shipping routes continued to support a geopolitical risk premium.
The competing supply developments left oil markets sensitive to further announcements and regional security developments.
For equity investors, attention will remain divided between the start of the US earnings season, forthcoming inflation data and the financial outlook for artificial intelligence investment.
Bank results will provide an early indication of corporate earnings conditions, while LVMH’s weaker sales and volatility in semiconductor stocks have highlighted potential risks to market valuations.
Oil prices and geopolitical developments will remain additional factors influencing inflation expectations and the broader direction of financial markets.
European stock markets moved higher on Tuesday, resisting broader weakness in global technology shares as investors focused on the start of the third-quarter earnings season and continued strength in energy-related stocks.
The pan-European Stoxx Europe 600 index gained 0.3% in early trading, outperforming technology-heavy markets in Asia and the United States, where concerns about artificial intelligence valuations weighed on investor sentiment.
European equity markets have relatively less exposure to the largest AI-focused technology companies than the Nasdaq and several Asian semiconductor markets, helping to limit the impact of the latest sector sell-off.
Germany’s DAX rose 0.2%, while France’s CAC 40 advanced 0.5%. London’s FTSE 100 gained 0.8%, and Spain’s IBEX 35 increased 0.4%, supported by its substantial exposure to banking stocks.
The gains reflected a more favourable performance among financial and energy companies, which helped offset weakness in technology, industrial and consumer-related shares.
Energy Shares Supported by Elevated Oil and Gas Prices
European energy stocks attracted investor interest as crude oil and natural gas prices remained close to their highest levels in two weeks.
Concerns about shipping security in the Middle East, particularly around the Strait of Hormuz, continued to influence energy markets.
Attacks on commercial vessels and uncertainty surrounding maritime transport routes have contributed to higher perceived supply risks, supporting oil and gas prices.
European natural gas futures remained above €82 per megawatt-hour, while crude oil prices also held firm.
Higher energy prices can support revenues and earnings expectations for oil and gas producers, although their effect varies depending on production costs, contractual arrangements and market conditions.
Energy companies listed in London, Oslo and other European markets consequently helped support regional equity indices.
Utilities also attracted attention, although the impact of higher energy prices on individual companies depends on their generation portfolios, fuel purchasing arrangements and regulatory exposure.
The strength of energy-related shares provided some protection against declines elsewhere in the market, particularly among industrial and consumer discretionary businesses.
US Banking Results Set to Influence Market Sentiment
Investors were also preparing for the start of the third-quarter earnings season, with several major US banks scheduled to publish their financial results.
JPMorgan Chase (NYSE:JPM), Goldman Sachs Group (NYSE:GS), Citigroup (NYSE:C) and Wells Fargo (NYSE:WFC) were among the institutions expected to report during Tuesday’s session.
Their results will provide investors with information about profitability, lending conditions, credit quality and activity across financial markets.
Particular attention will be paid to net interest income and the relationship between lending yields and deposit funding costs.
Elevated interest rates can support returns on certain banking assets, but competition for deposits and higher funding expenses may limit the benefits.
Investors will also examine provisions for credit losses and loan charge-off rates to assess whether households and businesses are experiencing greater difficulty servicing debt.
These indicators could provide insight into the effects of higher borrowing costs on the wider US economy.
Investment banking revenue will be another area of focus, including advisory fees, underwriting activity and the outlook for mergers and acquisitions.
Changes in dealmaking activity can offer an indication of corporate confidence and companies’ willingness to pursue investment or expansion plans.
Given the international operations of major US banks, their results may also influence expectations for European financial institutions and broader equity markets.
ASML and EQT Among Upcoming European Earnings Reports
Alongside US banking results, investors are preparing for important European corporate updates later in the week.
Dutch semiconductor equipment manufacturer ASML (EU:ASML) is scheduled to report third-quarter earnings on Wednesday.
The company’s results will provide information about demand for advanced semiconductor manufacturing equipment and capital expenditure trends among global chip producers.
ASML’s performance is closely followed because of its role in supplying lithography systems used in semiconductor production.
Investors will be assessing order intake, revenue trends and management commentary on demand from customers investing in advanced chip manufacturing.
The results may also help clarify whether spending associated with artificial intelligence infrastructure is translating into sustained demand for semiconductor production equipment.
Swedish investment group EQT is also expected to publish a corporate update later in the reporting period.
Its figures will provide insight into private equity investment activity, fundraising conditions and the deployment of institutional capital.
Investors will be monitoring developments in portfolio valuations, transaction activity and private credit markets, particularly as financing conditions continue to influence corporate transactions.
The upcoming reports will offer additional information about business confidence and investment trends across European and international markets.
European equities began Tuesday’s session on a positive footing despite the global technology sell-off, supported by gains in banking and energy-related shares.
However, market direction will remain sensitive to corporate earnings, geopolitical developments and changes in expectations surrounding artificial intelligence investment.
The results from major US banks and European companies, including ASML, will provide further evidence of how businesses are performing against a backdrop of elevated energy prices and uncertain global market conditions.
FTSE 100 rises as BP flags impairments and Whitbread reports lower profit. European markets are mixed, while Brent crude and gold decline.
Market Overview
The FTSE 100 opened higher on Tuesday, rising 0.86 per cent to 10,748.00, with commodity-related stocks providing support despite broader concerns over global technology shares. European markets were mixed, with the Euronext 100 slipping 0.13 per cent to 1,864.14, while Germany’s DAX gained 0.30 per cent to 25,353.91. On Wall Street, the Nasdaq closed lower at 27,245.90, while the S&P 500 declined to 7,807.24, reflecting continued pressure on technology stocks. European investors are also monitoring the start of the US bank earnings season.
Commodity markets showed mixed performance, with copper advancing while gold and natural gas declined. Brent crude edged lower as prospects for additional Russian diesel supplies counterbalanced concerns about disruptions to Middle Eastern energy exports. Bitcoin strengthened against sterling, while the pound weakened against the US dollar, Swiss franc and Australian dollar but strengthened against the euro and Japanese yen. Energy supply uncertainty and corporate earnings remain important influences on market sentiment.
Market Numbers
FTSE 100: Up (+0.86%), 10,748.00
Euronext 100: Down (-0.13%), 1,864.14
DAX: Up (+0.30%), 25,353.91
NASDAQ: Down, 27,245.90
S&P 500: Down, 7,807.24
In the Headlines
Q3 Impairments and Debt Reduction – BP (LSE:BP.) Energy major BP expects third-quarter post-tax impairment charges of between $3.0 billion and $4.5 billion, primarily affecting its gas and low-carbon businesses. Net debt is expected to fall to between $13.5 billion and $14.5 billion from $22.3 billion at the end of June, with the reduction providing an important balance sheet development ahead of its quarterly results.
First-Half Profit Decline – Whitbread (LSE:WTB) Hotel operator Whitbread reported a decline in first-half FY27 statutory profit as it continued expanding its Premier Inn business and implementing cost-saving measures. Investors are assessing the impact of its expansion strategy and operating efficiencies on future profitability.
London’s FTSE 100 outperformed major European equity benchmarks on Tuesday, rising 0.8% as gains among energy producers, mining companies and banks helped offset weaker sentiment across international stock markets.
The UK’s blue-chip index benefited from its substantial exposure to commodity-related businesses and financial services, while technology shares faced selling pressure in the United States and Asia.
Higher energy prices provided support for London-listed oil and gas producers, while major UK banks advanced ahead of third-quarter earnings announcements from leading US financial institutions.
The gains contrasted with a more cautious backdrop across global equity markets, where declines in technology stocks contributed to broader concerns about valuations and market positioning.
The FTSE 100’s composition played a significant role in its relative performance, with energy, mining and banking companies accounting for a substantial proportion of the index.
These sectors responded to different market factors from those affecting technology-heavy benchmarks, allowing London shares to advance despite weakness elsewhere.
Energy companies were among the contributors to the FTSE 100’s gains as crude oil and European natural gas prices remained elevated.
Shell (LSE:SHEL) and BP (LSE:BP.) attracted buying interest as Brent crude traded close to two-week highs.
European natural gas futures also remained above €82 per megawatt-hour, providing additional support for sentiment towards energy producers.
Higher commodity prices can influence revenue and earnings expectations for oil and gas companies, although the eventual financial impact depends on production levels, operating costs and individual companies’ trading arrangements.
The performance of Shell and BP was particularly relevant to the FTSE 100 because of their significant index weightings.
Mining stocks also contributed to the benchmark’s advance, supported by relatively stable industrial metals prices.
Rio Tinto (LSE:RIO) and Glencore (LSE:GLEN) moved higher as investors assessed commodity market conditions and adjusted their exposure to different equity sectors.
The gains came amid a broader rotation away from some highly valued technology shares, with investors showing increased interest in companies linked to physical commodities and established cash-generating businesses.
Mining companies remain sensitive to changes in global industrial activity, demand for raw materials and movements in metals prices.
Financial services provided another source of support for London’s equity market.
Shares in HSBC (LSE:HSBA), Barclays (LSE:BARC) and Lloyds Banking Group (LSE:LLOY) advanced ahead of the publication of third-quarter results from major Wall Street banks.
Investors were assessing the outlook for banking profitability, particularly the ability of lenders to maintain net interest margins as interest rate expectations evolve.
Net interest margins measure the difference between interest income generated by banks and the cost of funding their lending activities, relative to interest-earning assets.
The upcoming US bank results were expected to provide further information about lending conditions, profitability and financial market activity.
UK banking shares benefited from expectations that interest income could remain relatively resilient, although the outlook continues to depend on monetary policy, funding costs and credit demand.
In currency markets, sterling strengthened modestly against the US dollar.
The pound rose approximately 0.14% to trade around $1.322, supported by stabilising UK government bond yields.
Currency traders continued to assess the Bank of England’s near-term monetary policy outlook ahead of forthcoming inflation figures.
Movements in gilt yields and expectations for UK interest rates remained important influences on sterling, particularly as investors evaluated the timing and scale of potential monetary policy changes.
The relative strength of the pound came alongside gains in UK equities, although currency movements can have different implications for companies depending on the geographical distribution of their earnings.
Many FTSE 100 constituents generate substantial revenue outside the UK, making exchange rate fluctuations an additional consideration for investors.
Tuesday’s market performance highlighted the influence of sector composition on major equity benchmarks.
While technology-related selling affected markets in the United States and Asia, London’s greater exposure to energy, mining and banking companies provided support.
The FTSE 100’s 0.8% advance reflected gains across several of its largest sectors, rather than a broad improvement in international investor sentiment.
Attention will now turn to upcoming corporate earnings announcements, developments in commodity prices and UK inflation data, which could influence expectations for interest rates and the outlook for listed companies.
For London equities, the immediate market direction will remain sensitive to energy prices, banking sector results and changes in global risk appetite.