Category: Top Story

  • Market Open: Hays Net Fees Decline, Thruvision Holds Guidance

    Market Open: Hays Net Fees Decline, Thruvision Holds Guidance

    FTSE 100 rises as Hays reports lower net fees and Thruvision maintains revenue guidance. European stocks advance while Brent crude edges higher.

    Market Overview

    The FTSE 100 moved higher after opening to 10,609.67, gaining 0.55 per cent as oil supply concerns eased despite continuing tensions in the Middle East. European equities also advanced, with the Euronext 100 rising 0.52 per cent and Germany’s DAX gaining 0.55 per cent, supported by cautious optimism surrounding Russia-Ukraine ceasefire developments. On Wall Street, the Nasdaq closed higher at 27,366.17, while the S&P 500 advanced to 7,811.54.

    Commodity markets showed mixed movements, with copper, gold and natural gas declining, while Brent crude edged higher as investors continued to assess Middle Eastern supply risks. Bitcoin strengthened against sterling, while the pound gained against the US dollar, Swiss franc, euro, Japanese yen and Australian dollar. Geopolitical developments remained a key influence on energy markets and broader investor sentiment.


    Market Numbers

    FTSE 100: Up (+0.55%), 10,609.67

    Euronext 100: Up (+0.52%), 1,869.82

    DAX: Up (+0.55%), 25,224.38

    NASDAQ: Up, 27,366.17

    S&P 500: Up, 7,811.54


    In the Headlines

    First-Quarter Net Fees Decline – Hays (LSE:HAS)
    Global recruitment group Hays reported a 3 per cent like-for-like decline in first-quarter net fees as permanent hiring remained subdued, while restructuring savings reached £125 million. The update highlights continuing recruitment market pressures alongside the company’s efforts to reduce costs and protect profitability.

    Revenue Guidance Maintained – Thruvision (LSE:THRU)
    Security screening technology company Thruvision maintained its £8 million revenue guidance for FY2027, supported by an order backlog reaching £2.6 million. The backlog provides greater visibility over future revenue as the company works towards meeting its full-year expectations.


    Currencies (vs GBP)

    USD: Down (-0.10%), $1.3242

    CHF: Down (-0.25%), Fr.1.1015

    EUR: Down (-0.06%), €1.1821

    JPY: Down (-0.28%), ¥209.811

    AUD: Down (-0.11%), $1.8975

    Bitcoin (BTC/GBP): Up, £63,605.00


    Commodities

    Copper: Down

    Gold: Down

    Brent Crude: Up

    Natural Gas: Down

  • FTSE 100 Rises as Oil Prices Decline Amid Middle East Developments

    FTSE 100 Rises as Oil Prices Decline Amid Middle East Developments

    The FTSE 100 moved higher on Monday as oil prices declined, while investors assessed developments in the Middle East following attacks on airports in Saudi Arabia and statements concerning negotiations over the Strait of Hormuz.

    London’s benchmark index gained 0.49% as of 07:20 GMT, broadly matching advances across major European markets. Germany’s DAX rose 0.49%, while France’s CAC 40 increased 0.50%. Sterling strengthened 0.08% against the US dollar to $1.3243.

    Oil prices moved lower despite continued uncertainty surrounding regional security. Brent crude futures declined 0.50% to $104.21 per barrel, while US West Texas Intermediate crude fell 0.65% to $91.25.

    Iranian security chief Mohsen Rezaei said the United States had accepted some of Tehran’s seven conditions for reopening the Strait of Hormuz, although other conditions remained unresolved.

    Speaking to state-owned Press TV, Rezaei described the US response as inadequate and warned that data centres and communications cables in the Gulf could become targets if hostilities resumed.

    His comments followed attacks attributed to Houthi forces against airports in Saudi Arabia over the weekend.

    An attack on Riyadh’s King Khalid International Airport on Saturday reportedly killed 13 people and injured more than 300. A second attack on Sunday left one person dead and 11 injured.

    Australia and New Zealand joined the United States, United Kingdom, Canada, Japan and South Korea in issuing travel warnings concerning Saudi Arabia.

    US President Donald Trump indicated that Washington could participate in Saudi military operations against the Houthis, although no decision was confirmed.

    Separately, Trump announced an agreement under which Russia would supply approximately 13.5 million barrels of diesel, alongside a temporary easing of US sanctions on Russian diesel.

    He also announced an energy-related ceasefire between Russia and Ukraine.

    ING said confirmation of the ceasefire was still required from both countries. Ukrainian President Volodymyr Zelenskiy indicated that Ukraine was prepared to participate if Russia stopped its attacks.

    Market analysts also commented on the diplomatic developments. Jefferies strategist Mohit Kumar suggested that a ceasefire would serve the interests of both Iran and the United States.

    Stephen Innes of SPI Asset Management indicated that financial markets were assigning less of a geopolitical risk premium to individual developments than previously.

    Beyond geopolitical developments, investors are awaiting US inflation figures scheduled for release later this week.

    The data follows a rise in US Treasury yields, with the benchmark 10-year yield exceeding 5.36% last week, reaching its highest level since 2002.

    The Securities Industry and Financial Markets Association has recommended that the US Treasury market close for Columbus Day, while US equity markets are scheduled to operate normally.

    Precious metals also traded lower during the session. Gold futures declined 0.20% to $4,208.26 per ounce, while spot gold fell 0.24% to $4,184.33.

    UK Corporate News

    Hays (LSE:HAS) reported a 3% decline in first-quarter net fees on a like-for-like basis, reflecting reduced permanent recruitment activity alongside relatively stable demand for temporary and contracting services.

    The recruitment group said it expects market conditions to remain broadly stable in the near term.

  • Hays Reports 3% Decline in First-Quarter Net Fees as Restructuring Savings Reach £125 Million

    Hays Reports 3% Decline in First-Quarter Net Fees as Restructuring Savings Reach £125 Million

    Hays (LSE:HAS) reported a 3% decline in group net fees on a like-for-like basis for the first quarter of its 2027 financial year, with the recruitment company expecting market conditions to remain broadly stable in the near term. The group also reported further cost reductions under its Momentum restructuring programme.

    For the three months ended 30 September 2026, net fees declined 5% on an actual basis, partly reflecting country disposals completed earlier in the year. The rate of decline moderated during the quarter, with September net fees falling 2%.

    Temporary and contracting recruitment continued to outperform permanent placements. Net fees from temporary and contracting operations decreased 1% on a like-for-like basis, with volumes remaining sequentially stable. Permanent recruitment net fees fell 7%, reflecting a 12% reduction in placement volumes.

    Regional performance varied across the group’s markets. Germany recorded a 6% decline in net fees, while the United Kingdom and Ireland reported a 5% reduction. Australia and New Zealand experienced a 3% decrease, while the Rest of World division recorded flat net fees, supported by growth in the Americas and Asia.

    Chief executive Mark Dearnley attributed the moderation in the group’s net fee decline to growth in temporary and contracting recruitment across several countries. He also reported a return to growth in permanent placement activity in North America.

    Consultant net fee productivity increased 8% during the quarter, marking the twelfth consecutive quarter of improvement on a seasonally adjusted basis. Productivity rose 11% in Germany and 10% in the UK and Ireland.

    Hays continued implementing its Momentum restructuring strategy, which targets approximately £50 million in annual structural cost savings during the current financial year.

    The company achieved around £10 million of additional annualised savings during the first quarter, bringing cumulative structural cost savings to approximately £125 million per annum since the beginning of FY2024.

    The group’s net debt position stood at approximately £45 million at 30 September 2026, compared with net cash of £20.1 million at 30 June 2026. Hays attributed the change to seasonal cash flow movements and share purchases associated with its all-colleague share award.

    Looking ahead, Hays expects recruitment market conditions to remain broadly stable in the near term, with temporary and contracting activity continuing to demonstrate greater resilience than permanent hiring.

    The company also said it does not anticipate any material impact from differences in working days during the second quarter.

    About Hays plc

    Hays plc is a global specialist recruitment company providing permanent, temporary and contracting recruitment services across multiple industries and professional sectors.

    The group operates internationally, connecting employers with qualified professionals through its recruitment network. Its activities cover major markets including Germany, the United Kingdom, Ireland, Australia, New Zealand and other territories across Europe, the Americas and Asia.

  • KEFI Gold and Copper Resumes Tulu Kapi Development Following Fatal Incident and Safety Review

    KEFI Gold and Copper Resumes Tulu Kapi Development Following Fatal Incident and Safety Review

    KEFI Gold and Copper (LSE:KEFI) has resumed development activities at its Tulu Kapi Gold Project in Ethiopia following a suspension associated with the fatal Genji Incident. The decision follows safety reviews and consultations with local communities and government authorities at multiple levels.

    The company has outlined a phased approach to restarting work, beginning with electricity connections and access road development. The next stage will involve community resettlement, followed by construction activities within the mining licence area, including security infrastructure, bulk earthworks and accommodation facilities for workers.

    KEFI said the revised development programme incorporates findings from the reviews conducted after the incident. The company is also prioritising the use of experienced local contractors as part of its approach to sourcing labour and services within Ethiopia.

    According to KEFI, project lenders remain supportive as the company updates its development schedule and associated funding drawdown arrangements to reflect the revised sequence of activities.

    The company also reported continued engagement with Ethiopian stakeholders, including government representatives and local communities. Management reiterated its commitment to workplace safety, environmental and social standards, and community participation as development progresses.

    KEFI has invested more than US$150 million in Tulu Kapi to date. Once operational, the mine is expected to provide direct employment for approximately 1,000 local workers.

    The project also includes plans for infrastructure improvements, including roads and electricity connections, alongside education and healthcare facilities. KEFI expects the development to create opportunities for local businesses supplying goods and services to the mining operation.

    The resumption of activities marks the next stage in the company’s development programme at Tulu Kapi, with initial work focused on infrastructure and community arrangements before construction progresses within the mining licence area.

    About KEFI Gold and Copper

    KEFI Gold and Copper is a mineral exploration and development company focused on the Arabian-Nubian Shield, with projects in Ethiopia and Saudi Arabia.

    Its principal development asset is the Tulu Kapi Gold Project in Ethiopia, where the company is working towards establishing a producing gold mine. KEFI’s development plans include local employment, infrastructure investment and community engagement, alongside environmental and social management measures.

  • Afentra Revises Angola Drilling Programme as Impala-2 First Oil Targeted for January 2027

    Afentra Revises Angola Drilling Programme as Impala-2 First Oil Targeted for January 2027

    Afentra (LSE:AET) has revised its drilling programme at Block 3/05 offshore Angola, prioritising development of the Impala-2 well ahead of further work at the Pacassa SW discovery. The company now expects first oil from Impala-2 in January 2027, with initial gross production estimated at approximately 4,000 barrels per day.

    Under the revised programme, the Borr Grid drilling rig will move directly to Impala-2, with joint venture partners providing direct funding for the development well. The project will operate under a reduced cost cap of $60 million, an arrangement designed to limit Afentra’s exposure to cost overruns while allowing the company to benefit from early production revenues and the full capital expenditure uplift.

    Following completion of Impala-2, the rig is scheduled to return to the Pacassa SW discovery to undertake sidetrack drilling and well completion activities. First oil from Pacassa SW is expected during the first quarter of 2027, using existing production infrastructure.

    Afentra also anticipates revisions to resource estimates associated with both Impala and Pacassa SW as development work progresses. According to the company, Pacassa SW could potentially contribute approximately 70 million barrels of additional resources.

    The revised drilling sequence places Impala-2 ahead of Pacassa SW in the development schedule, with both projects targeting initial production during the first quarter of 2027. The company expects the developments to contribute to production volumes and cash flow as the wells are brought online.

    Afentra’s activities form part of its ongoing redevelopment programme in Angola, where the company is focused on increasing production from existing assets and progressing additional development opportunities within its portfolio.

    About Afentra plc

    Afentra plc is an upstream oil and gas company focused on production and development assets in Africa. The company holds interests in offshore and onshore oil and gas blocks in Angola, including producing Block 3/05 and additional exploration and development acreage in the Lower Congo and Kwanza basins. Its strategy includes acquiring and redeveloping existing energy assets in partnership with international oil companies and host governments.

  • Thruvision Maintains £8 Million FY27 Revenue Guidance as Order Backlog Reaches £2.6 Million

    Thruvision Maintains £8 Million FY27 Revenue Guidance as Order Backlog Reaches £2.6 Million

    Thruvision Group (LSE:THRU) reported first-half revenue of £2.6 million for the 2027 financial year, unchanged from the comparable period and in line with expectations, while its order backlog increased to £2.6 million. The security technology company maintained its full-year revenue guidance of £8 million, supported by existing orders and contracts scheduled for delivery during the second half.

    The company reported that its partner network accounted for almost 60% of first-half sales, reflecting an increased contribution from its distribution channels. Thruvision has expanded its network of value-added resellers in the UK and Benelux region and recruited additional sales personnel in the United States and UK.

    During the period, Thruvision secured further retail distribution agreements in Europe and added its first Canadian government customer. The company also reported a contract valued at more than £3 million to deploy its security screening systems across multiple airports in South-East Asia, with deployment planned for the second half of FY27.

    The airport agreement represents a significant component of the company’s reported contract activity and contributes to its order pipeline for the remainder of the financial year.

    Thruvision identified public space protection and transport hub security as areas of increasing demand for its technology. The company said its contract activity and distribution network expansion have improved revenue visibility, with management maintaining its expectations for continued growth into FY28.

    The company’s full-year revenue forecast remains unchanged at £8 million, compared with the £2.6 million recorded in the first half.

    About Thruvision Group plc

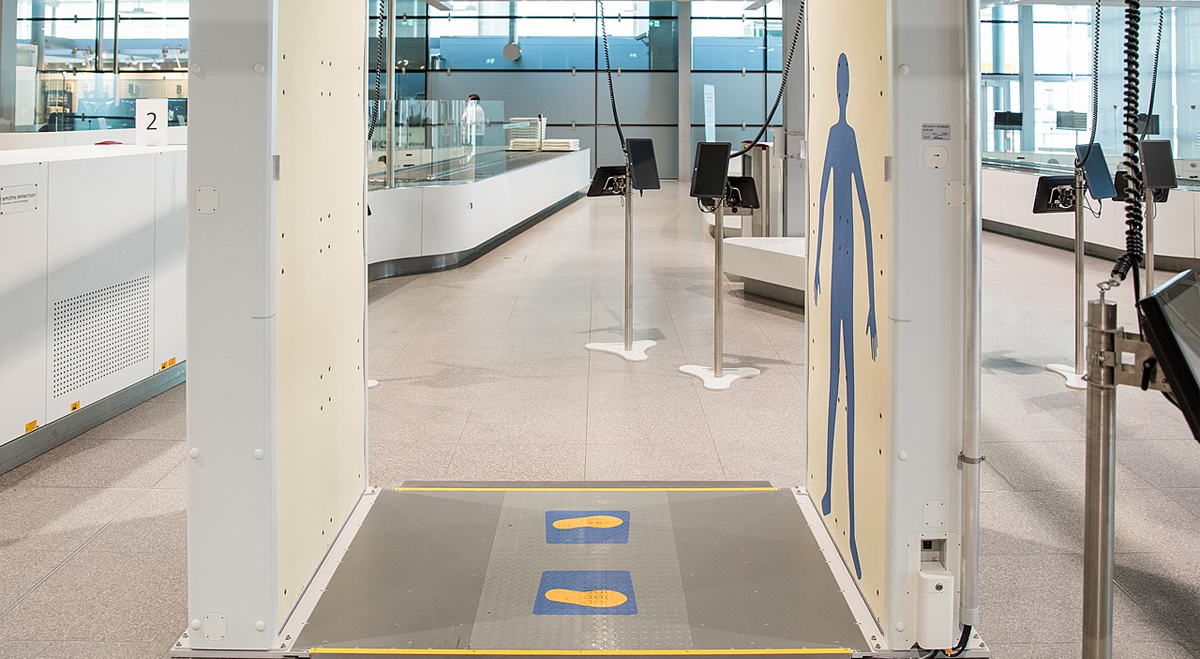
    Thruvision Group plc develops and manufactures walk-through security screening technology for government and commercial customers in more than 30 countries. Its AI-enabled systems are designed to detect concealed metallic and non-metallic objects in real time, including in locations with high pedestrian traffic. The company maintains offices and manufacturing operations in the UK and United States.

  • US Stock Futures Climb as Tech Shares Seek Recovery Following Nasdaq Sell-Off: Dow Jones, S&P, Nasdaq, Wall Street

    US Stock Futures Climb as Tech Shares Seek Recovery Following Nasdaq Sell-Off: Dow Jones, S&P, Nasdaq, Wall Street

    US stock index futures advanced on Friday as investors looked towards a potential recovery in technology shares following a difficult session on Wall Street, while lower crude oil prices helped ease concerns about inflation.

    Nasdaq 100 futures gained 0.7%, suggesting that technology stocks could lead early gains after Thursday’s decline, which was intensified by reports raising questions about OpenAI’s revenue performance.

    Despite the setback, investor interest in artificial intelligence remains an important source of support for technology shares, although concerns about valuations and earnings expectations have increased.

    Oil prices also moved lower after geopolitical developments helped reduce fears of an immediate military escalation involving Iran.

    However, a rebound in US Treasury yields threatened to limit buying interest as traders prepared for next week’s inflation reports and the beginning of the quarterly earnings season.

    Investors Await US Inflation Figures and Major Bank Results

    The upcoming economic calendar includes reports on consumer and producer prices from the US Labor Department.

    Both releases will be closely watched for evidence of whether inflationary pressures are easing or remaining elevated.

    The figures could influence expectations for Federal Reserve interest rate policy, particularly following recent volatility in Treasury yields and energy markets.

    Attention will also turn to quarterly earnings announcements from major financial institutions.

    Citigroup (NYSE:C), JPMorgan Chase (NYSE:JPM), Wells Fargo (NYSE:WFC) and Bank of America (NYSE:BAC) are among the banks scheduled to release their results.

    Their financial performance and management forecasts will provide investors with further information about lending conditions, consumer activity and the broader economic outlook.

    Daniela Hathorn, senior market analyst at Capital.com, said the relationship between earnings growth and inflation would be important for the direction of equities.

    “Strong earnings combined with moderating inflation would offer the most supportive backdrop for equities,” Hathorn said.

    She warned that disappointing company forecasts alongside persistent inflation could increase market vulnerability.

    “Conversely, persistent price pressures alongside disappointing corporate guidance could expose the vulnerability of a market increasingly dependent on a relatively small group of technology companies to sustain its rally.”

    The remarks highlighted concerns that recent market strength has relied heavily on a limited number of major technology companies.

    Nasdaq Retreats Further From Record High

    US equities closed mostly lower on Thursday as technology stocks came under renewed selling pressure.

    The Nasdaq Composite fell 345.35 points, or 1.3%, to 27,193.34, extending its retreat from Tuesday’s record closing level.

    The S&P 500 declined 36.41 points, equivalent to 0.5%, ending the session at 7,765.36.

    The Dow Jones Industrial Average performed slightly better, adding 51.77 points, or 0.1%, to finish at 51,231.64.

    Although the Nasdaq recovered from its lowest levels of the day, technology shares remained under pressure as investors reacted to geopolitical developments and concerns surrounding artificial intelligence companies.

    The declines followed modest losses in the previous session, suggesting that market participants were becoming more cautious ahead of important economic and corporate announcements.

    Oil Market Volatility Adds to Investor Uncertainty

    Energy prices played a significant role in Thursday’s trading after crude oil futures surged on reports of possible renewed US military action against Iran.

    NBC News reported that President Donald Trump and members of his national security team had discussed options for restarting large-scale military operations in the coming weeks.

    The report cited a US official and another person familiar with the discussions, indicating that potential strikes before next month’s midterm elections were among the options considered.

    Oil prices subsequently eased after Trump denied that the United States would attack Iran before the elections.

    His comments briefly helped US stocks recover as investors reassessed the immediate risk of military escalation.

    Nevertheless, crude prices remained sharply higher during Thursday’s session.

    Continuing attacks on tankers in the Middle East and the possibility of hurricane-related disruptions to oil production in the Gulf of Mexico maintained concerns about supply.

    The developments highlighted the potential for geopolitical events and weather-related disruptions to influence inflation expectations through energy prices.

    OpenAI Revenue Concerns Trigger Technology Sector Losses

    Technology stocks faced additional pressure after the Financial Times reported that OpenAI’s annualised revenue was approximately $20 billion below the level previously indicated by the company.

    The newspaper cited financial documents shared with investors as the basis for its report.

    The information prompted renewed scrutiny of revenue expectations within the artificial intelligence sector, where investors have anticipated substantial growth from continued spending on AI infrastructure and services.

    Semiconductor shares were particularly affected.

    The Philadelphia Semiconductor Index dropped 3.4%, reflecting widespread selling among chip-related companies.

    Computer hardware stocks also declined, with the NYSE Arca Computer Hardware Index losing 2.5%.

    Networking companies and biotechnology stocks recorded notable losses, adding to the weakness across technology and growth-oriented sectors.

    Energy producers, meanwhile, benefited from the increase in crude prices, with oil-related shares moving higher despite the broader market decline.

    Treasury Yields and Earnings Outlook Remain Key Risks

    Friday’s rise in US futures indicated that investors were considering a return to technology shares after the previous day’s losses.

    Lower crude prices provided additional support, although higher Treasury yields remained a potential constraint on market gains.

    Rising bond yields can make equities less attractive relative to fixed-income investments and place particular pressure on highly valued growth companies.

    With inflation data and major bank earnings approaching, traders may remain reluctant to make substantial commitments before receiving clearer evidence about economic conditions and corporate profitability.

    The coming reports will also test whether earnings growth can support equity valuations amid concerns about inflation and the concentration of market gains.

    For now, US futures suggest a stronger start to Friday’s session, but the sustainability of any rebound will depend on developments in energy markets, interest rates and the outlook for corporate earnings.

  • European Stocks Rebound as Oil Prices Fall and French Bond Yields Ease: DAX, CAC, FTSE100

    European Stocks Rebound as Oil Prices Fall and French Bond Yields Ease: DAX, CAC, FTSE100

    European stock markets advanced sharply on Friday, recovering from two consecutive sessions of losses as declining oil prices and easing French government bond yields helped improve investor sentiment.

    The rebound followed comments from US President Donald Trump indicating that Washington would not launch military strikes against Iran before next month’s midterm elections and that discussions with Tehran remained productive.

    The remarks helped ease immediate concerns about a potential escalation in the Middle East, contributing to a decline in crude oil prices and supporting European equities.

    Investors also welcomed a retreat in French government bond yields, which had previously reached their highest levels in several decades amid concerns about the country’s fiscal outlook.

    Germany’s DAX climbed 1.3%, while the UK’s FTSE 100 gained 1.2%. France’s CAC 40 advanced 1%, reflecting broad-based gains across major European markets.

    Energy Prices and Inflation Remain in Focus

    The decline in oil prices provided some relief to European markets, where concerns about energy costs and inflation have weighed on sentiment.

    Bank of France Governor Emmanuel Moulin attributed inflationary pressures across the Eurozone entirely to energy-related shocks, describing their contribution as “100 percent”.

    Moulin also said he had not observed second-round inflationary effects, suggesting that higher energy prices had not yet triggered broader increases in wages and other prices.

    His comments highlighted the importance of energy markets in shaping the region’s inflation outlook and expectations for monetary policy.

    A sustained decline in oil prices could help reduce inflationary pressures, although the broader outlook remains sensitive to geopolitical developments and energy supply conditions.

    French Fiscal Concerns Ease but Remain a Market Risk

    French government bonds also attracted attention after yields retreated from recent multi-decade highs.

    The decline helped ease pressure on European financial markets, although concerns about France’s public finances remain unresolved.

    Speaking at a news conference on Thursday, European Economic Commissioner Valdis Domrovskis urged France to adopt a fiscally responsible budget for 2027.

    He said prudent fiscal planning would be important for reassuring financial markets ahead of the country’s presidential election next year.

    The comments underscored continued scrutiny of France’s fiscal position, particularly after the recent increase in government borrowing costs.

    While lower bond yields supported Friday’s recovery, investors remain attentive to the country’s budget negotiations and the potential implications for European debt markets.

    Porsche Shares Rise Despite Decline in Vehicle Deliveries

    Among individual stocks, German sports car manufacturer Porsche (TG:PAH3) recorded gains despite reporting weaker global vehicle deliveries.

    The company said deliveries during the first nine months of 2026 declined 16% compared with the corresponding period a year earlier.

    Although the figures pointed to weaker vehicle sales volumes, Porsche shares advanced alongside the broader recovery in European equities.

    The announcement did not provide additional details explaining the positive share price reaction.

    Hexagon Gains After $535 Million Rocscience Acquisition

    Swedish industrial technology group Hexagon AB (TG:0QJ0) also rallied after announcing an agreement to acquire Canadian software company Rocscience.

    The transaction values Rocscience at $535 million on a cash-free, debt-free basis.

    The acquisition will expand Hexagon’s portfolio of industrial technology and software capabilities.

    Investors responded positively to the announcement, with Hexagon shares advancing during Friday’s session.

    The companies did not provide additional financial details about the expected earnings contribution or integration costs in the information released.

    Sika and Tryg Advance on Corporate Developments

    Swiss specialty chemicals manufacturer Sika (TG:SIKA) posted strong gains after announcing the acquisition of British landscaping products company Azpects Group.

    The transaction adds another business to Sika’s operations, although financial terms were not disclosed in the announcement.

    Scandinavian insurer Tryg (TG:T2V1) also moved sharply higher following the release of its third-quarter financial results.

    The company reported pre-tax profit above analysts’ expectations, supporting investor confidence in its earnings performance.

    The gains across Porsche, Hexagon, Sika and Tryg contributed to the positive tone in European equity markets.

    European Markets Recover After Two-Day Decline

    Friday’s advance reflected a combination of easing geopolitical concerns, lower energy prices and reduced pressure in government bond markets.

    Comments suggesting that US-Iran discussions remain productive helped calm immediate fears of military escalation, while the pullback in French bond yields provided additional support.

    Corporate developments also influenced trading, with acquisitions and stronger-than-expected earnings attracting investor interest.

    Despite the rebound, markets remain exposed to uncertainty surrounding Middle Eastern tensions, European inflation and France’s fiscal outlook.

    Investors will continue to assess whether the improvement in sentiment can be sustained as political and economic developments unfold.

  • US Futures Edge Higher as OpenAI Revenue Outlook, Delta Results and Economic Data Take Centre Stage: Dow Jones, S&P, Nasdaq, Wall Street

    US Futures Edge Higher as OpenAI Revenue Outlook, Delta Results and Economic Data Take Centre Stage: Dow Jones, S&P, Nasdaq, Wall Street

    US stock index futures advanced modestly on Friday as investors weighed fresh reports about OpenAI’s revenue expectations, prepared for quarterly earnings from Delta Air Lines and awaited an update on American consumer confidence.

    Developments in the Middle East and a major wireless spectrum agreement involving SpaceX also attracted attention following a mixed session on Wall Street.

    At 03:04 ET (07:04 GMT), futures on the Dow Jones Industrial Average were 33 points higher, representing a 0.1% increase. S&P 500 futures gained 25 points, or 0.3%, while Nasdaq 100 futures rose 243 points, equivalent to 0.8%.

    The advance followed Thursday’s trading session, when the Dow Jones gained 0.1%, but the S&P 500 declined 0.47% and the Nasdaq Composite dropped 1.25%.

    OpenAI Revenue Reports Put AI Investment Outlook in Focus

    Technology shares came under pressure after the Financial Times reported that OpenAI (NASDAQ:OAI) had generated approximately $50 billion in annualised revenue by the end of September.

    That figure was below a previously indicated level of $70 billion, prompting renewed scrutiny of the company’s growth trajectory.

    A subsequent Bloomberg News report presented a more optimistic year-end outlook, stating that OpenAI expects annualised revenue to reach or exceed $70 billion by the end of 2026.

    According to Bloomberg, the company’s enterprise operations are expected to provide a substantial contribution to that growth.

    The reported September revenue level and projected December figure relate to different periods and should not necessarily be interpreted as conflicting measurements.

    Annualised revenue has become an important benchmark for investors assessing the commercial adoption of artificial intelligence and the infrastructure expenditure required to meet demand.

    Nevertheless, OpenAI’s financial outlook remains subject to uncertainty.

    Recent reports indicate that the company is still expected to record a full-year loss, despite its expanding revenue base.

    OpenAI has also reportedly projected cumulative cash consumption of $280 billion by 2030, reflecting the scale of investment associated with computing infrastructure and AI development.

    These figures have added to broader market discussions about the sustainability of AI-related capital expenditure and the growing use of debt financing to support technology infrastructure projects.

    Delta Air Lines Earnings Expected Before Market Open

    Delta Air Lines (NYSE:DAL) is among the companies scheduled to report quarterly earnings on Friday.

    Analysts surveyed by Bloomberg expect the airline to announce third-quarter adjusted revenue of $17.66 billion and adjusted earnings of $1.82 per share.

    Delta reaffirmed its annual profit guidance in July and issued third-quarter projections that exceeded analysts’ expectations at the time.

    The carrier also indicated that it expected to sustain higher ticket prices introduced in response to rising fuel costs.

    However, management estimated that fuel expenditure would increase by approximately $4 billion this year compared with the previous year.

    The effect of higher energy prices on operating margins is therefore likely to remain an important consideration when investors assess the airline’s latest financial performance and outlook.

    University of Michigan Consumer Sentiment Figures Due

    Another focus for investors is the University of Michigan’s preliminary October consumer sentiment survey.

    Economists expect the headline index to fall to 47.5 from September’s reading of 48.1, which represented a four-month low.

    The report is expected to provide additional insight into household attitudes towards inflation, economic conditions and spending as the year-end shopping period approaches.

    September’s survey showed continued concern about rising prices, although assessments of conditions for buying durable goods improved slightly.

    Joanne Hsu, director of the university’s Surveys of Consumers, attributed part of that improvement to “a perception that completing such purchases now would help consumers avoid higher prices in the future.”

    One-year inflation expectations increased to their highest level since June.

    The survey also reported “broad agreement across the political spectrum” that the economic outlook had weakened since the beginning of the year.

    The October figures could help investors assess whether concerns about inflation and household finances are continuing to influence consumer behaviour.

    Middle East Developments Keep Oil Markets Volatile

    Energy prices remained another source of uncertainty after Brent crude futures recorded their largest daily increase in two weeks on Thursday.

    The rise followed concerns that further military action in the Middle East could disrupt energy production or transport routes.

    Oil subsequently surrendered part of its gains after US President Donald Trump described discussions with Iran as “positive” and indicated that Washington would not carry out military strikes against the country before November’s midterm elections.

    Earlier media reports had suggested that the Pentagon was considering potential military action before the vote.

    The possibility of higher energy costs has contributed to concerns about inflation and interest rates, particularly as government bond markets have experienced substantial volatility.

    SpaceX Spectrum Purchase Lifts US Tower Operators

    Shares in major US mobile communications infrastructure companies rose in extended trading after SpaceX (NASDAQ:SPCX) agreed to purchase nationwide low-band wireless spectrum.

    American Tower (NYSE:AMT), Crown Castle (NYSE:CCI) and SBA Communications (NASDAQ:SBAC) advanced between 3% and 4.5% following the regular session.

    The Wall Street Journal reported that SpaceX would pay approximately $8 billion in cash to digital infrastructure investor Grain Management.

    The acquisition is intended to strengthen Starlink’s satellite-to-mobile services by providing frequencies capable of supporting connectivity in areas where satellite signals face physical obstacles.

    Bernstein said the transaction preserved the possibility that SpaceX could establish a terrestrial wireless network alongside its satellite operations.

    SpaceX Chief Executive Elon Musk called the agreement “the last critical piece of the spectrum puzzle needed for SpaceX to provide complete phone coverage in America.”

    The announcement has raised questions about the potential future relationship between satellite communications providers, conventional mobile operators and companies that own wireless infrastructure.

    The market implications will depend on how SpaceX develops its network and the extent to which terrestrial facilities become part of its strategy.

    Overall, Friday’s early gains in US futures came against a backdrop of uncertainty over technology sector valuations, corporate profitability, consumer demand and geopolitical risks.

    Upcoming economic releases and earnings announcements may provide further direction for trading as investors assess the outlook for the final quarter of 2026.

  • European Stocks Recover in Early Trading but Remain on Course for Weekly Losses: DAX, CAC, FTSE100

    European Stocks Recover in Early Trading but Remain on Course for Weekly Losses: DAX, CAC, FTSE100

    European stock markets moved higher on Friday, recovering some of the losses recorded earlier in the week as volatility in government bond markets moderated. However, regional equities remained on course for a weekly decline amid concerns about French public finances, rising borrowing costs and geopolitical tensions.

    The pan-European Stoxx Europe 600 index advanced 0.8% in early trading after falling to its lowest level in almost four months during the previous session.

    France’s CAC 40 and Britain’s FTSE 100 each gained 0.8%, while Spain’s IBEX 35 rose 1%.

    Despite the recovery, the Stoxx Europe 600 remained approximately 1% lower for the week, reflecting several sessions of selling across European equity and fixed-income markets.

    Investor concerns have centred partly on France’s fiscal outlook, with public debt projected to approach 120% of gross domestic product.

    The French government also faces political challenges in implementing proposed budget reductions totalling €54 billion, given the fragmented composition of the country’s legislature.

    These concerns contributed to selling in French government bonds earlier in the week, pushing the benchmark 10-year yield towards its highest level in approximately 25 years.

    The spread between French and German government bond yields widened beyond 140 basis points, reflecting an increased premium demanded by investors to hold French sovereign debt.

    Pressure also extended to Italian and Greek government bonds, while higher sovereign yields contributed to concerns about equity valuations and corporate financing conditions.

    French equities were among the weaker performers over the week.

    The CAC 40 remained close to its lowest levels since March and was heading towards a weekly decline exceeding 2%, which would mark its second consecutive weekly loss.

    French banking shares experienced selling pressure, including BNP Paribas (EU:BNP), Crédit Agricole (EU:ACA) and Société Générale (EU:GLE).

    Investors assessed the potential effects of higher sovereign bond yields on banks’ securities portfolios, refinancing expenses and credit risk.

    Rising government borrowing costs can reduce the market value of existing fixed-rate bond holdings, although the financial impact depends on individual banks’ portfolio structures, accounting classifications and risk management arrangements.

    Reports of substantial debt issuance by major US technology companies also formed part of the wider fixed-income market backdrop.

    Increased corporate bond supply can compete with sovereign debt for investor capital, potentially influencing borrowing costs and credit spreads.

    Energy market developments added to uncertainty during the week.

    Missile and drone attacks affecting commercial shipping and energy infrastructure in the Persian Gulf and Red Sea contributed to concerns about supply disruptions.

    Crude oil prices moved above $100 per barrel, while European wholesale natural gas prices exceeded €80 per megawatt-hour during the period.

    Higher energy prices can increase costs for European businesses and households, while also complicating the inflation outlook for central banks.

    Monetary policy expectations were another consideration for investors.

    Minutes from the Federal Reserve’s September meeting indicated that a majority of US policymakers considered further interest rate increases necessary before the end of the year.

    The prospect of additional monetary tightening contributed to uncertainty about the outlook for global borrowing costs and economic activity.

    In France, Bank of France Governor Emmanuel Moulin described the country’s economic situation as “serious”, while indicating that intervention from the European Central Bank was not required.

    His comments came amid continued debate over France’s fiscal position and the potential implications of elevated government borrowing costs.

    Friday’s gains represented a partial recovery following the week’s declines, rather than a reversal of the broader market trend.

    European equities remained sensitive to developments in sovereign bond markets, energy prices, central bank policy and the political outlook for French public finances.