Category: Top Story

  • Aston Martin Reports 36% Rise in Q3 Revenue to £388.7 Million as Valhalla Deliveries Support Margins

    Aston Martin Reports 36% Rise in Q3 Revenue to £388.7 Million as Valhalla Deliveries Support Margins

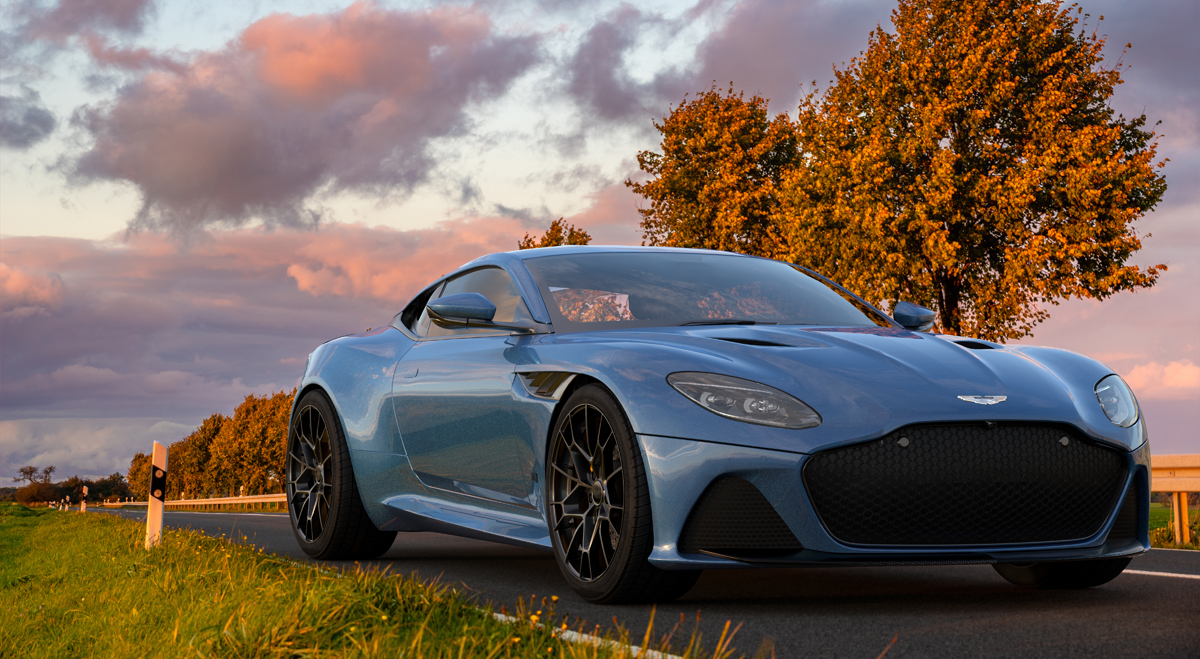
    Aston Martin Lagonda Global Holdings plc (LSE:AML) reported a 36% increase in third-quarter revenue to £388.7 million, supported by deliveries of its Valhalla Coupe and a higher average selling price, while maintaining its financial guidance for 2026.

    The British luxury car manufacturer recorded third-quarter gross profit of £145.5 million, up 76% from £82.8 million a year earlier. Gross margin increased to 37.4% from 29.0%, reflecting changes in the product mix and benefits from the company’s operational transformation programme.

    Adjusted EBITDA rose to £69.9 million from £10.7 million, while the operating loss narrowed to £26.4 million from £56.1 million.

    Wholesale volumes were broadly unchanged at 1,431 vehicles, compared with 1,430 in the corresponding period last year. The total included 127 deliveries of the Valhalla Coupe.

    For the first nine months of 2026, revenue increased 38% to £1.02 billion, while free cash outflow declined to £225.2 million from £415.0 million.

    Aston Martin also reported liquidity of approximately £322 million following the completion of a debt financing arrangement in July, although net debt increased to £1.57 billion.

    Third-Quarter Revenue Increases 36%

    Aston Martin generated revenue of £388.7 million during the three months ended 30 September 2026, compared with £285.2 million in the corresponding period of 2025.

    Vehicle sales contributed £356.3 million, an increase of 39% from £255.5 million.

    Revenue from parts rose 2% to £23.0 million, while vehicle servicing revenue increased 41% to £4.8 million.

    Brand and motorsport activities generated £4.6 million, up 24% from £3.7 million.

    The company attributed the increase in overall revenue primarily to its product mix, including deliveries of higher-priced Special models.

    Total wholesale volumes remained largely unchanged, indicating that the revenue increase was driven mainly by the composition and pricing of vehicles delivered rather than an increase in total units.

    Nine-Month Revenue Reaches £1.02 Billion

    For the nine months ended 30 September 2026, Aston Martin reported revenue of £1,017.3 million, compared with £739.6 million in the prior-year period.

    The 38% increase was supported by higher deliveries of Special models, particularly the Valhalla Coupe.

    Vehicle sales revenue increased 40% to £919.5 million from £654.7 million.

    Parts revenue rose 7% to £72.1 million, while servicing revenue increased 37% to £12.5 million.

    Brand and motorsport revenue reached £13.2 million, compared with £8.5 million a year earlier, representing growth of 55%.

    The company’s nine-month results also reflected changes to its manufacturing operations and cost structure.

    Average Selling Price Rises 25% Year-to-Date

    Aston Martin reported a 25% increase in its total average selling price for the first nine months of 2026.

    The average price rose to £243,000 per vehicle from £194,000 in the corresponding period last year.

    During the third quarter, the total average selling price increased 39% to £247,000 from £178,000.

    The company said the increase was primarily attributable to deliveries of the Valhalla Coupe, which contributed to a higher proportion of Special models in the sales mix.

    The average selling price for core vehicles, excluding Specials, was £185,000 for the nine-month period, compared with £186,000 a year earlier.

    In the third quarter, core average selling price increased 7% to £190,000 from £177,000.

    This also represented a 3% increase from the second-quarter average of £184,000.

    Aston Martin said targeted dealer support to reduce older inventory continued to affect year-to-date core pricing, although it expects inventory levels to move towards normalised levels during the second half.

    Vehicle personalisation contributed approximately 17% of core revenue during the first nine months, broadly unchanged from the previous year.

    Wholesale Volumes Remain Stable at 1,431 Vehicles

    Aston Martin reported total wholesale deliveries of 1,431 vehicles in the third quarter, compared with 1,430 in the corresponding period last year.

    Core wholesale volumes, excluding Specials, declined 9% to 1,304 vehicles from 1,428.

    Special model deliveries increased to 127 vehicles from two a year earlier.

    The company said the decline in core wholesale volumes reflected its planned production schedule, which became more balanced from the second quarter onwards.

    Core wholesale volumes were broadly stable compared with the 1,270 vehicles delivered in the second quarter.

    Aston Martin also reported that core retail volumes continued to exceed wholesale volumes by more than 20% during the first nine months.

    Management said this reflected its approach to aligning production and dealer supply with customer demand.

    The core vehicle order book remained stable.

    Nine-Month Wholesale Deliveries Increase 12%

    Total wholesale volumes for the first nine months of 2026 reached 3,762 vehicles, an increase of 12% from 3,352 in the corresponding period last year.

    Core wholesale deliveries increased 2% to 3,410 vehicles from 3,332.

    Special model deliveries reached 352 vehicles, compared with 20 a year earlier.

    The increase in Specials was primarily attributable to approximately 350 Valhalla Coupe deliveries during the period.

    Sport and GT models accounted for 2,493 wholesale deliveries, up 4% from 2,394.

    SUV deliveries declined 2% to 917 vehicles from 938.

    Aston Martin maintained its expectation that total wholesale volumes for 2026 will be similar to the 5,448 vehicles delivered in 2025.

    The full-year forecast includes approximately 500 Valhalla Coupe deliveries.

    UK and Americas Record Higher Wholesale Volumes

    Aston Martin reported different regional wholesale trends during the third quarter.

    UK deliveries increased 26% to 314 vehicles from 250 a year earlier.

    Americas volumes rose 11% to 480 vehicles from 433.

    However, deliveries in Europe, the Middle East and Africa, excluding the UK, declined 20% to 373 vehicles.

    Asia Pacific wholesale volumes decreased 5% to 264 vehicles.

    For the first nine months, all four geographic regions recorded increases.

    Americas deliveries rose 22% to 1,317 vehicles, while UK volumes increased 17% to 736.

    Europe, the Middle East and Africa, excluding the UK, recorded growth of 6% to 1,064 vehicles.

    Asia Pacific deliveries increased 1% to 645 vehicles.

    The Americas remained Aston Martin’s largest wholesale market by volume during the nine-month period.

    Valhalla Coupe Deliveries Contribute to Revenue Growth

    Aston Martin delivered a further 127 Valhalla Coupes during the third quarter, bringing the year-to-date total to approximately 350 vehicles.

    The model contributed to the increase in total average selling prices and the improvement in gross margin.

    The company expects approximately 500 Valhalla Coupe deliveries during 2026.

    Aston Martin said nearly all remaining Valhalla Coupes have been ordered, with deliveries expected to be completed by the end of the first half of 2027.

    The Valhalla is the company’s first mid-engined plug-in hybrid electric vehicle.

    Its contribution to the sales mix has been a principal factor in the company’s financial performance during 2026.

    Aston Martin Introduces Valhalla Spider and Valen

    Aston Martin announced the Valhalla Spider, an open-top version of the Valhalla Coupe.

    Deliveries are expected to begin in the third quarter of 2027.

    The company said its existing order book for the model extends into the fourth quarter of 2027.

    Aston Martin also launched the Valen during the third quarter of 2026.

    The company describes Valen as the world’s most powerful front-engined production car.

    Deliveries of Valen are scheduled to commence in the second quarter of 2027.

    The new models expand Aston Martin’s Specials programme, which includes limited-production vehicles alongside its core model range.

    The company also recently introduced the DBX GT, expanding its SUV portfolio.

    Aston Martin expects additional derivatives to follow as part of its product development programme.

    Gross Profit Increases 76% in Third Quarter

    Aston Martin reported third-quarter gross profit of £145.5 million, compared with £82.8 million a year earlier.

    The 76% increase reflected higher revenue and changes in the vehicle sales mix.

    Gross margin increased to 37.4% from 29.0%, an improvement of 840 basis points.

    For the first nine months, gross profit increased 71% to £358.0 million from £209.4 million.

    The nine-month gross margin improved to 35.2% from 28.3%, an increase of 690 basis points.

    Aston Martin attributed the improvement to increased Special model deliveries and benefits from its operational transformation programme.

    These benefits included lower manufacturing costs and reduced expenditure associated with product quality and customer satisfaction initiatives compared with the previous year.

    The company said the improvements were partly offset by targeted dealer support and foreign exchange movements.

    Adjusted EBITDA Reaches £69.9 Million

    Aston Martin reported third-quarter adjusted EBITDA of £69.9 million, compared with £10.7 million in the corresponding period last year.

    The adjusted EBITDA margin increased to 18.0% from 3.8%.

    For the first nine months, adjusted EBITDA reached £132.6 million, compared with £7.7 million a year earlier.

    The nine-month adjusted EBITDA margin increased to 13.0% from 1.0%.

    The company attributed the increase to higher gross profit, partly offset by higher adjusted operating expenses.

    Adjusted operating expenses excluding depreciation and amortisation increased 12% to £225 million during the first nine months, compared with £202 million a year earlier.

    Aston Martin said this expenditure remained consistent with its full-year expectations.

    Operating Loss Narrows to £26.4 Million

    Aston Martin reported a third-quarter operating loss of £26.4 million, compared with a loss of £56.1 million in the corresponding period of 2025.

    The reduction of approximately 53% reflected the increase in gross profit.

    Adjusted EBIT remained negative at £24.9 million, compared with a £50.6 million loss a year earlier.

    For the first nine months, the reported operating loss narrowed to £82.9 million from £190.8 million.

    Adjusted EBIT improved to a loss of £133.8 million from £172.1 million.

    The nine-month reported operating result included £47.7 million of adjusting other income associated with the sale of Aston Martin Formula One naming rights to AMR GP.

    The company also recorded higher depreciation and amortisation expenses, reflecting increased deliveries of Special models.

    Adjusted depreciation and amortisation rose 48% to £266.4 million during the nine-month period, compared with £179.8 million a year earlier.

    Pretax Loss Falls to £77.1 Million in Third Quarter

    Aston Martin reported a third-quarter loss before tax of £77.1 million, compared with £111.9 million in the corresponding period last year.

    The loss after tax narrowed to £78.8 million from £131.8 million.

    For the first nine months, the pretax loss decreased to £231.3 million from £252.7 million.

    The reported loss after tax was £231.9 million, compared with £280.5 million a year earlier.

    However, the nine-month adjusted loss before tax increased to £283.0 million from £237.0 million.

    The difference reflected higher adjusted financing costs and the treatment of adjusting items.

    Aston Martin reported nine-month net financing expenses of £148.4 million, compared with £61.9 million in the prior-year period.

    The increase included the impact of non-cash US dollar debt revaluations and additional interest associated with the company’s new financing arrangements.

    Financing Costs Increase Following Debt Refinancing

    Aston Martin reported adjusted net financing costs of approximately £149 million for the first nine months of 2026, compared with £65 million a year earlier.

    The increase partly reflected an £11 million foreign exchange loss arising from non-cash revaluation of US dollar-denominated debt.

    In the corresponding period of 2025, the company recorded a £58 million gain from these movements.

    Additional interest expenses also arose from the £450 million senior secured term loan arranged in July 2026.

    The higher financing costs contributed to the increase in the adjusted pretax loss despite improvements in operating performance.

    Aston Martin expects net cash interest of approximately £160 million for the full year, assuming current exchange rates prevail.

    This compares with £143 million in 2025.

    Free Cash Outflow Declines to £27.6 Million in Third Quarter

    Aston Martin reported third-quarter free cash outflow of £27.6 million, compared with £94.0 million in the corresponding period last year.

    The reduction of approximately 71% reflected improved operating cash generation and lower investment expenditure.

    Cash generated from operating activities reached £47.5 million during the quarter, compared with an outflow of £8.4 million a year earlier.

    Cash used in investing activities, excluding interest, was £73.8 million, compared with £83.4 million.

    Net cash interest paid during the quarter totalled £1.3 million.

    For the first nine months, free cash outflow declined to £225.2 million from £415.0 million.

    The company expects a material year-on-year improvement in free cash flow for 2026 as a whole.

    Operating Cash Flow Turns Positive for Nine-Month Period

    Aston Martin generated £45.2 million of cash from operating activities during the first nine months of 2026.

    This compares with an operating cash outflow of £89.4 million in the corresponding period last year.

    The improvement of approximately £135 million was primarily attributable to higher adjusted EBITDA.

    Working capital movements resulted in a £63 million cash outflow, compared with £45 million a year earlier.

    The principal movements included a £25 million increase in inventories and a £23 million increase in receivables.

    Deposits held declined by £21 million, reflecting the delivery of Special models.

    These movements were partly offset by a £7 million increase in payables.

    Aston Martin said the timing of production and deliveries contributed to the changes in working capital.

    Capital Expenditure Declines to £194 Million

    Aston Martin reported capital expenditure of £194 million during the first nine months of 2026, compared with £254 million in the prior-year period.

    Investment remained focused on future vehicle development and related technologies.

    The company expects capital investment of approximately £300 million for the full year, compared with £341 million in 2025.

    Aston Martin has also reduced its planned capital expenditure programme for 2026 to 2030 to approximately £1.7 billion.

    The previous programme had been approximately £2.0 billion.

    The revised investment plan forms part of the company’s efforts to manage expenditure while continuing product development.

    The company expects lower capital investment and improved operating cash generation to contribute to reduced free cash outflow.

    Liquidity Reaches £321.6 Million Following July Financing

    Aston Martin reported cash and available liquidity of £321.6 million at 30 September 2026.

    This compares with £247.8 million at the same point in 2025.

    The company completed a £550 million debt financing arrangement in July 2026.

    The financing comprises a £450 million senior secured term loan and a £100 million delayed draw term loan.

    The facilities carry interest at 6.75 percentage points above the prevailing SONIA base rate and mature in July 2031.

    Investment funds and accounts managed by HPS Investment Partners were identified as lead lenders.

    The financing also permits an additional £100 million of junior debt capacity.

    Aston Martin said the arrangement provides financial flexibility for its operational and investment plans.

    Net Debt Increases to £1.57 Billion

    Aston Martin reported net debt of £1,572.3 million at 30 September 2026.

    This compares with £1,380.3 million at 31 December 2025 and £1,381.0 million at 30 September 2025.

    Gross debt increased to £1,895.4 million from £1,631.6 million at the end of 2025.

    The increase primarily reflected the new senior secured term loan and non-cash foreign exchange movements, partly offset by repayment and cancellation of the group’s revolving credit facility.

    Despite the higher debt balance, Aston Martin reported an improvement in its adjusted net leverage ratio.

    The ratio declined to 6.7 times from 12.8 times at the end of 2025.

    The company attributed the reduction to higher adjusted EBITDA over the preceding 12 months, partially offset by the increase in net debt.

    Full-Year Wholesale Volume Guidance Maintained

    Aston Martin maintained its expectation that wholesale deliveries for 2026 will be similar to the 5,448 vehicles reported in 2025.

    The forecast includes approximately 500 Valhalla Coupe deliveries.

    The company expects retail volumes to continue exceeding wholesale volumes.

    Management also anticipates a more balanced production schedule across core and Special models during the remainder of the year.

    The group expects its product mix and operational transformation programme to contribute to improved financial performance.

    However, Aston Martin said it continues to monitor economic and geopolitical conditions affecting the global automotive industry.

    Gross Margin Expected to Reach High-30% Range

    Aston Martin maintained its expectation that full-year gross margin will increase into the high-30% range.

    This compares with a gross margin of approximately 29% in 2025.

    The company expects the improvement to reflect increased Valhalla Coupe deliveries, changes in its core model portfolio and manufacturing efficiencies.

    Adjusted operating expenses excluding depreciation and amortisation are expected to remain below £300 million for the full year.

    Adjusted depreciation and amortisation are forecast at between £375 million and £400 million.

    Aston Martin also expects its adjusted EBIT margin to improve towards breakeven from a negative 15.0% in 2025.

    These expectations remain dependent on the company’s planned vehicle deliveries, production performance and operating conditions.

    Global Trade and Economic Conditions Remain Under Review

    Aston Martin identified several external factors that could affect its operations and customer demand.

    These include potential changes to US tariffs, adjustments to China’s taxes on ultra-luxury vehicles and the stability of international supply chains.

    The company also referred to geopolitical uncertainty associated with the conflict in the Middle East.

    Management said it had limited the direct operational impact of these developments during 2026 but continues to monitor potential effects on demand and customer confidence.

    Aston Martin also noted that the US tariff quota mechanism introduced for UK automotive manufacturers in 2025 has increased the complexity of quarterly forecasting.

    The company said there had been no changes to that mechanism during the reporting period.

    CEO Adrian Hallmark Comments on Financial Performance

    Adrian Hallmark, Chief Executive Officer of Aston Martin, commented on the company’s nine-month results and product development programme.

    “Our year-to-date 2026 performance demonstrates tangible and consistent progress towards the financial transformation of Aston Martin. Valhalla deliveries, and the benefits of our transformation programme, have lifted gross margin to 35%, while free cash outflow almost halved as we move towards our goal of cash generation. We expect this momentum to continue into Q4 and beyond, in line with our unchanged full year 2026 guidance and outlook.

    “Our product line-up has also strengthened. The new DBX GT brings a more elegant, quiet-luxury character to our SUV range and two new models have elevated our Specials programme: Valen, launched in Q3 as the world’s most powerful front-engined production car, and the Valhalla Spider, unveiled today, which builds on the success of the groundbreaking mid-engined PHEV Valhalla Coupe. Together, they give us a strong platform for the future.”

    Outlook for the Remainder of 2026

    Aston Martin expects further improvement in financial performance during the final quarter of 2026, supported by its product mix and operational transformation programme.

    The company maintained its wholesale volume guidance and expects approximately 500 Valhalla Coupe deliveries during the year.

    Full-year gross margin is forecast to reach the high-30% range, while the adjusted EBIT margin is expected to move towards breakeven.

    Capital expenditure is expected to decline to approximately £300 million, and free cash outflow is forecast to improve materially compared with the £410 million outflow recorded in 2025.

    The company continues to target margin improvement and cash generation over the short to medium term.

    However, Aston Martin remains exposed to changes in global demand, financing costs, international trade conditions and supply chain developments.

    More About Aston Martin Lagonda

    Aston Martin Lagonda Global Holdings plc is a London-listed manufacturer of luxury sports cars and sport utility vehicles.

    Founded in 1913, Aston Martin designs and manufactures vehicles including the Vantage, DB12, Vanquish and DBX.

    Its product portfolio also includes limited-production Special models, including the Valhalla plug-in hybrid supercar.

    The company is headquartered in Gaydon, England, where its sports cars are manufactured, while DBX production takes place in St Athan, Wales.

    Aston Martin sells vehicles in more than 50 countries and continues to develop its product range through new models, derivatives and electrified powertrain technologies.
  • Unilever Reports 5.2% Q3 Underlying Sales Growth and Raises Full-Year Volume Outlook

    Unilever Reports 5.2% Q3 Underlying Sales Growth and Raises Full-Year Volume Outlook

    Unilever PLC (LSE:ULVR) reported underlying sales growth of 5.2% in the third quarter of 2026, supported by higher volumes across its Beauty & Wellbeing, Personal Care and Home Care businesses, while raising its full-year underlying volume growth forecast to at least 3%.

    The consumer goods group recorded quarterly turnover of €13.3 billion, an increase of 6.7% compared with the corresponding period of 2025. Underlying volume growth contributed 2.9 percentage points, while price growth contributed 2.3 percentage points.

    Unilever’s Home Care division recorded the highest underlying sales growth at 9.1%, followed by Personal Care at 6.3% and Beauty & Wellbeing at 5.7%. Foods reported broadly unchanged underlying sales, with a 0.1% increase.

    The company maintained its full-year underlying sales growth guidance of 4% to 6% and expects a modest improvement in its underlying operating margin compared with the 20.0% recorded in 2025.

    Unilever also confirmed that its proposed combination of its Foods business with McCormick remains on schedule, subject to regulatory and shareholder approvals.

    Third-Quarter Turnover Increases 6.7% to €13.3 Billion

    Unilever reported turnover of €13.3 billion for the three months ended 30 September 2026, compared with €12.4 billion in the corresponding period last year.

    The 6.7% reported increase reflected underlying sales growth of 5.2%, a net contribution of 0.8% from acquisitions and disposals, and a positive currency-related impact of 0.6%.

    Underlying sales growth comprised 2.9% volume growth and 2.3% price growth.

    The company said pricing increased during the quarter in response to higher commodity costs, particularly within Home Care and Personal Care.

    Unilever’s Power Brands recorded underlying sales growth of 5.8%, including volume growth of 3.3%.

    Performance varied across geographic markets, with emerging markets contributing most of the group’s underlying sales growth.

    Nine-Month Turnover Reaches €38.9 Billion

    For the first nine months of 2026, Unilever reported turnover of €38.9 billion, representing an increase of 2.7% from €37.9 billion in the corresponding period of 2025.

    Underlying sales growth for the nine-month period was 4.9%, comprising volume growth of 3.8% and price growth of 1.1%.

    Acquisitions contributed 1.3% to reported turnover growth, while disposals reduced it by 0.6%.

    Currency-related movements had a negative impact of 2.9%.

    The group reported a two-year compound annual growth rate of 4.1% for underlying sales and 2.5% for underlying volume.

    The nine-month performance was supported by growth in Home Care, Personal Care and Beauty & Wellbeing, while Foods recorded lower reported turnover.

    Full-Year Volume Growth Forecast Raised to at Least 3%

    Following its third-quarter performance, Unilever increased its underlying volume growth expectation for 2026.

    The company now forecasts volume growth of at least 3% for the full year.

    It also expects underlying sales growth of approximately 5% during the second half.

    Unilever maintained its multi-year underlying sales growth guidance range of 4% to 6% for 2026.

    The group continues to anticipate a modest improvement in its underlying operating margin compared with the 20.0% achieved in 2025.

    The revised volume outlook reflects performance during the first nine months and management’s expectations for the remainder of the year.

    Beauty & Wellbeing Sales Rise 9.5% to €3.5 Billion

    Unilever’s Beauty & Wellbeing division reported third-quarter turnover of €3.5 billion, an increase of 9.5% compared with the previous year.

    Underlying sales grew 5.7%, comprising volume growth of 3.6% and price growth of 2.1%.

    For the first nine months, turnover reached €10.0 billion, up 3.4%, while underlying sales increased 5.8%.

    Hair Care recorded double-digit growth during the quarter, supported by higher volumes and demand across several brands.

    Dove, Sunsilk, Clear and K18 each reported double-digit growth.

    Dove benefited from product developments in serums, masks and scalp care, alongside sales growth in India and the United States.

    Sunsilk and Clear recorded growth across Latin America and South East Asia.

    The prestige hair care brand K18 also delivered double-digit growth.

    Skin Care Growth Offsets Decline in Wellbeing

    Within Beauty & Wellbeing, Skin Care recorded mid-single-digit underlying sales growth.

    Vaseline reported double-digit growth, supported by performance across several markets, particularly in Asia Pacific Africa.

    The company’s prestige skin care portfolio also contributed, including Hourglass, Paula’s Choice and Dermalogica.

    However, Wellbeing sales declined by a high-single-digit percentage during the quarter.

    Unilever attributed part of the reduction to shipment timing associated with Amazon Prime Day, which had benefited second-quarter sales.

    For the first nine months, Wellbeing underlying sales declined 1.0%.

    The company also reported changes in channel distribution and pricing arrangements, including reduced distribution and private-label competition affecting Liquid I.V. in the club retail channel.

    Management said measures to improve customer acquisition for Nutrafol remained at an early stage.

    Grüns recorded growth during its first full quarter under Unilever ownership but will not be included in underlying sales growth calculations until June 2027.

    Unilever expects Wellbeing performance to improve sequentially from the third quarter.

    Personal Care Underlying Sales Increase 6.3%

    Unilever’s Personal Care division reported third-quarter turnover of €3.6 billion, up 9.7% from the previous year.

    Underlying sales growth was 6.3%, consisting of 3.8% volume growth and 2.4% price growth.

    For the first nine months, turnover increased 6.2% to €10.5 billion, while underlying sales grew 5.3%.

    Skin cleansing products recorded high-single-digit growth, while deodorants increased by a mid-single-digit percentage.

    Dove, the group’s largest brand, reported double-digit growth, including mid-single-digit volume growth.

    Unilever said growth was recorded across emerging markets and the United States.

    The company also increased prices during the quarter to reflect higher commodity costs.

    Deodorants and Skin Cleansing Contribute to Personal Care Growth

    Deodorants recorded mid-single-digit growth during the quarter, supported by higher sales volumes.

    Emerging markets reported double-digit growth, including double-digit increases in Latin America and high-single-digit growth in Asia Pacific Africa.

    US deodorant sales increased by a mid-single-digit percentage.

    Unilever said its FIFA World Cup 2026 sponsorship contributed to brand activity during the period.

    Dove deodorants recorded double-digit growth.

    Skin cleansing also increased by a high-single-digit percentage, supported by both volume and pricing.

    The company reported double-digit growth in emerging markets and mid-single-digit increases in North America and Europe.

    Dove’s body serum product ranges contributed to the category’s performance.

    Wild and Dr. Squatch also recorded double-digit growth, with Dr. Squatch included in underlying sales calculations from September.

    Oral Care declined by a low-single-digit percentage, as growth in India and South East Asia was offset by lower sales in Europe.

    Home Care Reports 9.1% Underlying Sales Growth

    Home Care generated third-quarter turnover of €3.1 billion, an increase of 7.5% compared with the previous year.

    Underlying sales growth reached 9.1%, comprising volume growth of 5.4% and price growth of 3.6%.

    For the first nine months, Home Care turnover totalled €9.0 billion, up 3.6%, while underlying sales increased 8.1%.

    Growth was led by emerging markets, particularly India and Brazil.

    Unilever reported double-digit growth in Asia Pacific Africa and Latin America.

    Higher commodity costs contributed to increased pricing during the quarter, and the company expects further pricing effects during the remainder of the year.

    Fabric Cleaning and Household Products Support Home Care Performance

    Fabric Cleaning recorded double-digit underlying sales growth, supported by high-single-digit volume growth.

    Price increases also contributed, with category pricing growth reaching a mid-single-digit percentage.

    Unilever reported double-digit Fabric Cleaning growth in India and Brazil.

    The company said its market share in India reached record levels during the quarter.

    Home & Hygiene products recorded mid-single-digit growth, with contributions from volume and pricing.

    Cif delivered double-digit growth, supported by its Infinite Clean product range and expansion into additional markets.

    Fabric Enhancers also grew by a mid-single-digit percentage, led by Comfort and demand across Asia Pacific Africa.

    Foods Sales Remain Broadly Unchanged at €3.1 Billion

    Unilever’s Foods division reported third-quarter turnover of €3.1 billion, unchanged on a reported basis from the previous year.

    Underlying sales increased 0.1%, with price growth of 1.3% offsetting a volume decline of 1.1%.

    For the first nine months, Foods turnover declined 2.6% to €9.4 billion.

    Underlying sales growth for the nine-month period was 0.8%.

    The company reported growth in emerging markets and its Unilever Food Solutions business, offset by lower retail sales in developed markets.

    Unilever cited subdued market conditions and increased competition in US condiments.

    Management is implementing product innovation and pricing measures intended to improve the performance of its US Foods business.

    Condiments and Cooking Aids Record Flat Sales

    Underlying sales in Cooking Aids remained broadly unchanged, as price increases offset lower volumes.

    Growth in South East Asia, Brazil and Africa was balanced by declines in developed markets.

    Condiments also recorded broadly flat underlying sales.

    Unilever said its US portfolio had lower exposure to some faster-growing segments, including premium and avocado mayonnaise.

    The company is introducing products and adjusting pricing to address these competitive conditions.

    Unilever Food Solutions recorded low-single-digit growth, supported by a mid-single-digit increase in North America.

    China also contributed low-single-digit growth.

    In India, Foods recorded high-single-digit growth, supported by double-digit growth in Horlicks.

    Emerging Markets Deliver 9.5% Underlying Sales Growth

    Unilever reported third-quarter emerging market turnover of €8.0 billion, with underlying sales growth of 9.5%.

    Volume increased 6.0%, while pricing contributed 3.3%.

    For the first nine months, emerging market turnover reached €23.5 billion, with underlying sales growth of 7.9%.

    Growth was recorded across several major markets, including India, Turkey, Vietnam, Pakistan, Latin America, Indonesia and South East Asia.

    India, Turkey, Vietnam and Pakistan each recorded double-digit underlying sales growth.

    Latin America, Indonesia and South East Asia reported high-single-digit increases.

    The company said emerging market performance contributed to group volume growth during the quarter.

    India Records 15% Underlying Sales Growth

    Unilever reported underlying sales growth of 15% in India during the third quarter, including volume growth of 7%.

    The company said the performance reflected growth across its principal business groups and a lower comparative base from the previous year.

    Home Care and Beauty & Wellbeing recorded double-digit increases.

    Personal Care and Foods grew by high-single-digit percentages.

    Hair Care was a contributor, supported by demand for Dove and TRESemmé products.

    India remained one of the principal contributors to the group’s emerging market performance.

    Asia Pacific Africa Sales Increase 10.1%

    The Asia Pacific Africa region generated turnover of €6.0 billion during the third quarter.

    Underlying sales growth was 10.1%, comprising volume growth of 5.8% and price growth of 4.1%.

    For the first nine months, regional turnover reached €17.3 billion, with underlying sales growth of 8.3%.

    Indonesia recorded 7% growth, supported by volume increases across Home Care, Personal Care and Beauty & Wellbeing.

    China reported low-single-digit growth, with mid-single-digit volume increases and contributions from all business groups.

    Unilever said social commerce activity supported performance in China, alongside new products within its Beauty & Wellbeing and Personal Care portfolios.

    Africa recorded mid-single-digit growth, supported by Vaseline, Home Care and Foods.

    Americas Revenue Reaches €5.0 Billion

    Unilever’s Americas business reported third-quarter turnover of €5.0 billion.

    Underlying sales growth was 2.8%, comprising volume growth of 0.9% and price growth of 1.8%.

    For the first nine months, turnover reached €14.7 billion, with underlying sales growth of 4.0%.

    Performance differed between North America and Latin America.

    North American underlying sales declined 0.7% during the quarter, although the company reported continued volume market share gains.

    Growth in Personal Care and Beauty was offset by lower sales in Wellbeing and Foods.

    Latin America recorded underlying sales growth of 8.5%, including volume growth of 6.5%.

    Brazil reported high-single-digit growth, supported by double-digit volume increases.

    Mexico recorded low-single-digit growth, while Argentina reported double-digit growth.

    European Underlying Sales Decline 1.7%

    Unilever reported third-quarter turnover of €2.3 billion in Europe.

    Underlying sales declined 1.7%, comprising a 0.4% reduction in volume and a 1.3% decline in pricing.

    For the first nine months, European turnover reached €6.9 billion, with underlying sales down 1.2%.

    Beauty & Wellbeing recorded mid-single-digit growth, while Personal Care increased by a low-single-digit percentage.

    The company reported growth in Dove products and deodorants.

    However, these increases were offset by lower sales in Home Care and Foods.

    Unilever attributed the declines to subdued market conditions in the region.

    Unilever Foods Combination With McCormick Remains on Schedule

    Unilever confirmed that preparations for the proposed combination of its Foods business with McCormick are progressing.

    The transaction was announced in March 2026 and is intended to separate Unilever’s Foods operations from its remaining consumer goods businesses.

    The company said more than 200 employees are working across 20 cross-functional teams on separation and integration activities.

    Regulatory filings have been submitted according to the planned timetable.

    The transaction remains subject to approval from McCormick shareholders, receipt of required regulatory approvals and satisfaction of other customary closing conditions.

    Consultation with relevant works councils is also underway.

    Unilever said it expects the consultation process to be completed before the transaction closes.

    The company did not announce a revised completion date.

    Portfolio Restructuring Continues Following Ice Cream Demerger

    The proposed Foods combination follows the December 2025 demerger of The Magnum Ice Cream Company.

    Together, these transactions form part of Unilever’s programme to reshape its business portfolio.

    Following the proposed Foods separation, the remaining business would be more concentrated on Beauty & Wellbeing, Personal Care and Home Care.

    Unilever said it continues to prioritise investment in growth and productivity, alongside selective acquisitions and disposals.

    No bolt-on acquisitions were completed during the third quarter.

    In August 2026, the company completed the disposal of its Home Care businesses in Colombia.

    The group also intends to continue returning capital to shareholders through dividends and potential share repurchases.

    Quarterly Dividend Increases 3% Year-on-Year

    Unilever declared a third-quarter interim dividend of €0.4664 per ordinary share.

    The payment is unchanged from the second-quarter 2026 dividend and represents an increase of 3.0% compared with the third quarter of 2025.

    For ordinary shares traded on the London Stock Exchange, the dividend is equivalent to £0.3907 per share.

    For shares traded on Euronext Amsterdam, the payment is €0.4664 per share.

    American Depositary Receipt holders will receive US$0.5219 per ADR.

    The currency conversions were determined using applicable exchange rates dated 26 October 2026.

    The shares are scheduled to trade ex-dividend on 12 November 2026, while the ex-dividend date for ADRs is 13 November.

    The record date is 13 November, with the deadline for dividend reinvestment elections set for 27 November.

    Payment is scheduled for 18 December 2026.

    CEO Fernando Fernandez Comments on Quarterly Performance

    Fernando Fernandez, Chief Executive Officer of Unilever, commented on the company’s sales performance and revised volume expectations.

    “We have delivered another quarter of competitive growth, led by continued strong volume delivery and a step up in price to offset the impact of higher commodity costs. Our Power Brands continued to lead performance, with strong growth across Home Care, Personal Care and Beauty & Wellbeing. Emerging markets were again a key driver, with broad-based growth across markets, led by India and continued strength in Latin America and South East Asia. Developed market performance reflected tougher prior year comparators and softer performance in Foods.

    We are performing while transforming Unilever. We are becoming simpler and sharper, with greater focus and stronger execution as we drive Desire at Scale across our brands. This progress gives us confidence that we will now deliver at least 3% volume growth for the full year.

    At our Investor Event next week we will set out how this transformation is creating a stronger, more focused Unilever capable of delivering sustained, competitive performance.”

    Investor Event Scheduled for November

    Unilever is scheduled to hold an investor event in New York on 4 November 2026.

    The company intends to provide further information about its business transformation, portfolio strategy and operational priorities.

    The event follows the third-quarter trading statement and the revision to the group’s full-year volume growth outlook.

    Unilever’s fourth-quarter and full-year 2026 results are scheduled for publication on 11 February 2027.

    Outlook for the Remainder of 2026

    Unilever expects underlying sales growth of between 4% and 6% for the full year, with underlying volume growth of at least 3%.

    The company anticipates second-half underlying sales growth of approximately 5% and a modest improvement in underlying operating margin compared with 2025.

    Performance during the third quarter was supported by growth in Home Care, Personal Care and Beauty & Wellbeing, particularly across emerging markets.

    Foods remained broadly unchanged on an underlying sales basis, while developed markets recorded lower sales.

    Unilever continues to implement pricing changes in response to commodity costs and is progressing its proposed Foods combination with McCormick.

    Further information about its business strategy is expected at the November investor event.

    More About Unilever

    Unilever PLC is a London-listed multinational consumer goods company operating across Beauty & Wellbeing, Personal Care, Home Care and Foods.

    Its portfolio includes brands such as Dove, Vaseline, Sunsilk, Clear, TRESemmé, Cif, Comfort, Hellmann’s and Horlicks.

    The company sells products across developed and emerging markets, with operations spanning Asia Pacific Africa, the Americas and Europe.

    Unilever completed the demerger of The Magnum Ice Cream Company in December 2025 and announced an agreement in March 2026 to combine its Foods business with McCormick.

    The group continues to develop its consumer goods portfolio while investing in product innovation, distribution and operational efficiency.

  • GSK Reports 4% Rise in Q3 Sales to £8.9 Billion, Beats Earnings Forecasts and Maintains Full-Year Guidance

    GSK Reports 4% Rise in Q3 Sales to £8.9 Billion, Beats Earnings Forecasts and Maintains Full-Year Guidance

    GSK plc (LSE:GSK) reported a 4% increase in third-quarter sales to £8.9 billion, supported by growth in its Specialty Medicines business, while core earnings per share exceeded analysts’ expectations.

    The British pharmaceutical company recorded core earnings per share of 54.6 pence for the three months ended 30 September 2026, compared with a company-compiled analyst consensus of 50.4 pence.

    Revenue increased 5% at constant exchange rates, with demand for HIV, respiratory, immunology and oncology medicines contributing to the quarterly performance.

    GSK maintained its full-year and longer-term financial targets despite reporting declines in total operating profit and statutory earnings per share, partly reflecting restructuring charges associated with its Accelerate Growth programme.

    The company also generated £3.1 billion in operating cash flow and £2.1 billion in free cash flow during the quarter.

    Third-Quarter Revenue Increases to £8.9 Billion

    GSK reported total sales of £8.9 billion for the third quarter of 2026, representing growth of 4% at actual exchange rates and 5% at constant exchange rates.

    The increase was primarily supported by the Specialty Medicines division, where sales rose across HIV, respiratory, immunology and inflammation, and oncology treatments.

    General Medicines revenue remained broadly unchanged, while Vaccines recorded a decline.

    The company attributed its core earnings performance to higher revenue, changes in its product and geographic sales mix, and increased royalty income.

    These factors were partly offset by higher research and development expenditure, investment in new product launches and increased financing costs.

    Core Earnings Per Share Exceed Analyst Expectations

    GSK reported core earnings per share of 54.6 pence, exceeding the company-compiled analyst consensus of 50.4 pence.

    The result was approximately 8.3% above the consensus estimate.

    Core earnings per share increased 1% compared with the corresponding period last year.

    Core operating profit rose 5%, reflecting revenue growth and the contribution from higher-margin products and royalty income.

    The increase was partly offset by additional spending on research and development, commercial investment associated with new medicines and higher finance costs.

    Core financial measures exclude certain items included in statutory results, including specified restructuring and other adjustments.

    Specialty Medicines Sales Rise 15% to £3.9 Billion

    GSK’s Specialty Medicines division reported third-quarter sales of £3.9 billion, representing growth of 15%.

    The division accounted for approximately 44% of total group revenue during the period.

    Growth was recorded across its principal therapeutic categories, including HIV, respiratory, immunology and inflammation, and oncology.

    The performance reflected continued demand for the company’s specialty treatments.

    Specialty Medicines was the main contributor to group revenue growth during the quarter, offsetting the decline in Vaccines sales and relatively unchanged revenue in General Medicines.

    HIV Medicines Revenue Increases 10%

    GSK reported HIV medicines sales of £2.1 billion during the third quarter, an increase of 10%.

    The HIV portfolio represented the largest component of Specialty Medicines revenue.

    The company continues to develop and commercialise treatments in this therapeutic area as part of its broader specialty pharmaceuticals business.

    The quarterly figures indicate that HIV medicines remained a contributor to group sales growth.

    GSK did not provide individual HIV product sales figures in the supplied quarterly summary.

    Respiratory, Immunology and Inflammation Sales Grow 21%

    Sales from respiratory, immunology and inflammation medicines increased 21% to £1.1 billion.

    The category contributed to the overall growth of Specialty Medicines during the quarter.

    GSK’s investment in these therapeutic areas forms part of its strategy to expand its portfolio of specialty treatments.

    The company has also continued to allocate research and development resources towards new medicines and potential product launches.

    The supplied results did not specify the contribution of individual products within this category.

    Oncology Revenue Advances 23%

    GSK’s oncology business reported third-quarter revenue of £0.6 billion, an increase of 23%.

    The category recorded the highest percentage sales growth among the Specialty Medicines areas disclosed in the update.

    Oncology remains part of GSK’s strategy to expand its portfolio of specialist medicines.

    The company’s investment in research, development and new product launches contributed to higher operating expenditure during the period.

    The quarterly summary did not provide a breakdown of sales by individual oncology treatment.

    Vaccines Revenue Declines 2% to £2.6 Billion

    GSK reported Vaccines sales of £2.6 billion for the third quarter, representing a decline of 2%.

    Performance varied across the company’s vaccine portfolio.

    Sales of Shingrix, the company’s shingles vaccine, decreased 5% to £0.8 billion.

    Meningitis vaccine revenue increased 12% to £0.6 billion, partially offsetting declines elsewhere in the division.

    Arexvy, GSK’s respiratory syncytial virus vaccine, recorded sales of £0.2 billion, down 24%.

    The differences in performance across these products contributed to the overall reduction in Vaccines revenue.

    The company did not provide detailed explanations for the individual vaccine sales movements in the supplied summary.

    General Medicines Revenue Remains Stable at £2.4 Billion

    GSK’s General Medicines division recorded third-quarter sales of £2.4 billion, broadly unchanged from the corresponding period last year.

    Within the division, Trelegy generated revenue of £0.8 billion, an increase of 8%.

    The product’s growth contributed to the performance of the General Medicines portfolio.

    However, the division’s overall revenue remained stable, indicating that growth in Trelegy was offset by movements elsewhere in the business.

    General Medicines accounted for approximately 27% of group sales during the quarter.

    Statutory Operating Profit Falls 16% Following Restructuring Charges

    Although core operating profit increased, GSK reported a 16% decline in total operating profit.

    Total earnings per share fell 21%.

    The statutory results were affected by £328 million in restructuring charges associated with the company’s Accelerate Growth programme.

    Lower other net operating income also contributed to the decline.

    These effects were partly offset by growth in core operating profit.

    The difference between statutory and core earnings reflects the impact of items excluded from the company’s adjusted performance measures.

    The Accelerate Growth programme forms part of management’s efforts to adjust the group’s operating structure and cost base.

    The supplied results did not specify the total expected savings or implementation timetable for the programme.

    Operating Cash Flow Reaches £3.1 Billion

    GSK reported cash generated from operations of £3.1 billion during the third quarter.

    Free cash flow totalled £2.1 billion.

    The cash flow figures provide a separate measure of the company’s financial performance alongside reported and core earnings.

    Cash generation remains relevant to GSK’s ability to fund research and development, commercial investment, restructuring activities and other corporate requirements.

    The supplied quarterly summary did not include comparative cash flow figures for the corresponding period of 2025.

    Full-Year and Long-Term Financial Targets Maintained

    GSK reaffirmed its annual and longer-term financial targets following the third-quarter results.

    The decision came despite restructuring charges affecting statutory profitability and mixed performance across the company’s operating divisions.

    Specialty Medicines continued to support group revenue growth, while General Medicines sales remained stable and Vaccines revenue declined.

    The company is also continuing its Accelerate Growth programme and investing in research, development and new product launches.

    GSK did not revise its financial guidance in the supplied announcement.

    The specific numerical ranges for its full-year and longer-term targets were not included in the source material.

    CEO Luke Miels Continues Focus on Growth and Portfolio Development

    The results come as Chief Executive Officer Luke Miels oversees initiatives intended to accelerate growth and prepare GSK for future patent expiries.

    The company’s strategy includes investment in specialty medicines, research and development, product launches and changes to its operating cost structure.

    During the third quarter, sales growth in HIV, respiratory, immunology and oncology medicines contributed to the group’s overall financial performance.

    At the same time, the company continued to incur restructuring costs associated with its Accelerate Growth programme.

    GSK’s ability to maintain revenue growth over the longer term will depend partly on the commercial performance of existing products, new medicine launches and the impact of patent expiries.

    Outlook for the Remainder of 2026

    GSK enters the final quarter of 2026 having reported nine-month progress that allowed it to maintain its annual financial targets.

    Third-quarter sales growth was led by Specialty Medicines, with HIV, respiratory, immunology and oncology products recording increases.

    The Vaccines division reported lower revenue, reflecting declines in Shingrix and Arexvy sales, while General Medicines remained broadly stable.

    Core operating profit and core earnings per share increased, although statutory profitability was affected by restructuring charges and lower other net operating income.

    The company continues to invest in its product portfolio and implement its Accelerate Growth programme.

    GSK has not announced changes to its full-year or longer-term financial objectives.

    More About GSK

    GSK plc is a London-listed global biopharmaceutical company focused on the research, development, manufacture and commercialisation of medicines and vaccines.

    The company operates across three principal commercial divisions: Specialty Medicines, Vaccines and General Medicines.

    Its therapeutic areas include HIV, respiratory diseases, immunology, inflammation, oncology and infectious diseases.

    GSK’s product portfolio includes Shingrix, Arexvy and Trelegy, alongside a range of specialist medicines and vaccines.

    The company continues to invest in research and development while implementing operational initiatives intended to support its longer-term business objectives.

  • Georgina Energy Outlines 8–10 Week Rig Mobilisation Plan for Hussar Helium and Hydrogen Project

    Georgina Energy Outlines 8–10 Week Rig Mobilisation Plan for Hussar Helium and Hydrogen Project

    Georgina Energy Plc (LSE:GEX) has outlined a revised mobilisation plan for its Hussar EP513 helium, hydrogen and natural gas exploration project in Western Australia, with drilling preparations expected to take approximately eight to ten weeks once formal authorisation to begin mobilisation activities is issued.

    The company is working with Ensign Energy Services to arrange the transportation and deployment of the Ensign Rig 970, following delays caused by adverse weather conditions and road closures affecting heavy vehicles.

    Georgina confirmed that all civil engineering and site preparation work required for drilling has been completed, with contractors and their equipment having left the site.

    However, the timing of rig mobilisation remains dependent on road access, and the company has not yet confirmed a revised drilling commencement date.

    Hussar Rig Mobilisation Expected to Take Eight to Ten Weeks

    Georgina Energy is reviewing a mobilisation programme with Ensign Energy Services and Westmarket Oil & Gas (WMOG), subject to the reopening of roads suitable for transporting the drilling equipment.

    Under the proposed schedule, reactivation of Ensign Rig 970 at its current Waylering location would take approximately four to five weeks.

    This phase includes recommissioning activities and ordering equipment required before transportation.

    Mobilisation of the accommodation camp from Port Augusta in South Australia would take place concurrently with the rig reactivation work.

    Once the equipment is ready and an accessible route has been confirmed, transportation of the drilling rig to the Hussar site is expected to take approximately three weeks.

    A further one to two weeks would be required to assemble the rig and prepare it for drilling.

    The company estimates that the overall process will take eight to ten weeks from the date Westmarket Oil & Gas formally instructs Ensign to commence mobilisation.

    The timetable remains conditional on road access and completion of the necessary preparations.

    Weather Conditions and Road Closures Delay Drilling Preparations

    Georgina said continuing road closures to heavy vehicles and variable weather conditions have prevented the planned mobilisation of Ensign Rig 970.

    The company is working with its contractors to identify a suitable transportation route that can accommodate the equipment.

    Although construction and preparation work at the Hussar location has been completed, the rig cannot be transported until the relevant roads are accessible.

    Management said personnel and equipment safety will remain a priority when determining the mobilisation arrangements.

    The company has not provided a firm date for the reopening of the affected roads.

    As a result, the eight-to-ten-week mobilisation estimate does not establish a confirmed drilling start date.

    Alternative Transport Routes Under Review

    Georgina and its contractors are assessing alternative routes to the Hussar exploration site.

    Consulting engineers and advisers Aztech Well Construction and Ingenua are assisting with the assessment of road access for Ensign Rig 970.

    Westmarket Oil & Gas is also reviewing a potential alternative route through Leonora, travelling along the Great Central Road before turning north onto the David Carnegie Highway.

    The proposed route would then continue towards the Mangkili turnoff and north along the Eagle Highway.

    The suitability of this route remains under review.

    The company has not confirmed whether the alternative will be adopted or whether additional transport approvals or road works will be required.

    Rig Reactivation and Transport Costs Expected to Increase

    Georgina reported that the revised mobilisation arrangements will result in additional costs compared with earlier estimates.

    The increases relate primarily to rig reactivation and transportation.

    Ensign Rig 970 has remained stacked for longer than initially anticipated, requiring additional reactivation work before deployment.

    Transport contractor ECS has also advised that its costs have increased from the original estimate.

    The company attributed the additional transport expenditure to changes identified in the August and September route survey, including the requirement for additional equipment and a longer transportation route.

    Higher fuel prices have also contributed to the revised cost estimate.

    Georgina said the additional mobilisation costs will be allocated between Ensign and Westmarket Oil & Gas.

    The company did not disclose the total expected increase or specify the amount payable by each party.

    Hussar Site Preparation Work Completed

    Georgina confirmed that all civil engineering and site preparation activities required to facilitate drilling at Hussar have been completed.

    Contractors responsible for these activities have demobilised from the location with their equipment.

    The project is therefore awaiting the mobilisation of the drilling rig and associated facilities before drilling operations can begin.

    The company is continuing to coordinate with Ensign Energy Services and Westmarket Oil & Gas to establish a revised schedule.

    Further announcements are expected as the mobilisation arrangements progress and a new drilling commencement date becomes available.

    Hussar Well Targets Helium, Hydrogen and Natural Gas

    The Hussar prospect is located within Exploration Permit 513 in the Officer Basin of Western Australia.

    Georgina plans to drill the exploration well to a total depth of approximately 3,200 metres.

    The planned depth may be extended depending on the geological formations encountered, indications of gas and the quality of potential reservoir intervals.

    The primary exploration targets are subsalt reservoir formations, including the Townsend Formation and fractured Neoproterozoic basement rocks.

    These formations are being evaluated for their potential to contain helium, hydrogen and natural gas.

    The company is also targeting hydrocarbon gas within the shallower Kanpa and Hussar formations.

    Georgina said these secondary targets have not been adequately tested by previous drilling, although earlier exploration encountered hydrocarbon indications and reservoir intervals with favourable porosity characteristics.

    The planned well is intended to provide further geological and reservoir information to assess the prospect’s resource potential.

    Fractured Basement Reservoirs Form Part of Exploration Strategy

    Georgina’s exploration programme includes fractured basement formations beneath the principal sedimentary sequences.

    The company identified these formations as potential reservoirs based on geological characteristics and comparisons with producing fields elsewhere.

    As an example of fractured basement production, Georgina referred to the Bach Ho field offshore Vietnam.

    The company noted that Bach Ho has produced hydrocarbons from fractured basement reservoirs for more than four decades and reached peak production equivalent to approximately 1.6 billion cubic feet of gas per day.

    However, the performance of an established producing field does not establish that similar production rates or commercially recoverable resources will be present at Hussar.

    The planned exploration well will be required to assess the geological conditions and potential gas accumulations at the Western Australian prospect.

    Independent Report Estimates Prospective Helium, Hydrogen and Gas Resources

    Georgina referred to an Independent Geological Report dated 1 February 2026, prepared by competent person Maki Petkovski.

    The report estimates unrisked net attributable 2U prospective resources at Hussar of 283 billion cubic feet of helium, 315 billion cubic feet of hydrogen and 2.93 trillion cubic feet of hydrocarbon gas.

    The estimates were prepared under the Society of Petroleum Engineers Petroleum Resources Management System framework.

    These figures represent prospective resources rather than discovered reserves.

    Prospective resources relate to quantities that may potentially be recoverable from undiscovered accumulations, subject to exploration success, development feasibility and commercial conditions.

    The estimates are unrisked and therefore do not incorporate the probability of geological discovery or commercial development.

    Drilling and further evaluation will be required to determine whether commercially recoverable accumulations exist.

    Company Estimates Potential In-Situ Resource Value at $152 Billion

    Georgina provided an indicative combined in-situ value of approximately US$152 billion for the prospect’s unrisked net attributable prospective resources.

    The estimate is based on assumed commodity prices of US$450 per thousand cubic feet of helium, US$2.65 per kilogram of hydrogen and US$8 per thousand cubic feet of hydrocarbon gas.

    The company said the valuation uses pricing information associated with the Australian Energy Regulator and the Helium Price Index.

    The figure represents an indicative gross in-situ resource value calculated from prospective volumes and assumed commodity prices.

    It is not a project valuation, net present value, revenue forecast or estimate of recoverable economic value.

    The calculation excludes production, processing, gas separation and transportation costs, together with other expenses required to develop and commercialise any discoveries.

    There is no certainty that the prospective resources will be discovered or that any portion will be commercially recoverable.

    Revised Drilling Date Remains Subject to Mobilisation

    Georgina has not announced a new drilling commencement date for Hussar EP513.

    The company said the timing will depend on the reopening of roads, the suitability of alternative transport routes and the completion of rig reactivation and mobilisation activities.

    The proposed eight-to-ten-week schedule will begin only after Westmarket Oil & Gas issues formal notification to Ensign Energy Services to commence the work.

    Further technical and logistical updates are expected as preparations continue.

    Georgina also intends to provide additional site photographs through its corporate website.

    CEO Comments on Hussar Mobilisation

    Anthony Hamilton, Chief Executive Officer of Georgina Energy, commented on the revised mobilisation arrangements and the company’s exploration objectives.

    “The Company is working with Ensign to facilitate mobilisation as quickly as possible and we anticipate that road closures due to unseasonal weather conditions will be overcome with careful planning and drilling Hussar for its Helium and Hydrogen potential into a full field development remains our priority target. We look forward to making further announcements in due course”.

    The company continues to work with its contractors to establish road access and prepare the drilling equipment for transportation.

    Outlook for the Hussar EP513 Project

    Georgina’s immediate priority is to finalise arrangements for mobilising Ensign Rig 970 to the Hussar exploration site.

    The company has completed the required civil engineering and site preparation work but remains dependent on suitable transport access.

    The revised mobilisation plan allows approximately eight to ten weeks between formal authorisation and readiness to commence drilling, subject to road conditions and completion of the planned activities.

    The exploration programme will target helium, hydrogen and natural gas within subsalt formations and secondary hydrocarbon-bearing intervals.

    The results of drilling will be needed to establish whether the prospect contains recoverable gas accumulations and to inform any subsequent appraisal or development decisions.

    Georgina has indicated that further announcements will follow as the mobilisation schedule and revised drilling date are determined.

    More About Georgina Energy

    Georgina Energy Plc is a London-listed exploration and development company focused on helium, hydrogen and natural gas opportunities in Australia.

    The company’s portfolio includes the Hussar prospect within Exploration Permit 513 in the Officer Basin of Western Australia.

    Hussar is planned as an exploration well targeting subsalt reservoir formations and shallower hydrocarbon-bearing intervals.

    An independent geological report dated February 2026 estimated unrisked net attributable prospective resources of 283 billion cubic feet of helium, 315 billion cubic feet of hydrogen and 2.93 trillion cubic feet of hydrocarbon gas.

    These estimates remain subject to geological uncertainty and do not constitute commercially recoverable reserves.

  • Pantheon Resources: Experienced Leadership and Major Resource Potential Put Alaska in Focus

    Pantheon Resources: Experienced Leadership and Major Resource Potential Put Alaska in Focus

    Pantheon Resources (LSE:PANR) (USOTC:PTHRF) is positioning itself at the centre of renewed interest in Alaska’s North Slope, with CEO Dave Wilkins bringing more than 40 years of oil and gas industry experience to the company’s Kodiak and Ahpun projects.

    When an experienced oil and gas executive comes out of retirement to lead a company, investors naturally want to understand what has captured his attention. For Dave Wilkins, the answer lies in Pantheon Resources’ substantial resource base, advances in seismic technology and the growing strategic importance of Alaska’s energy infrastructure.

    In an interview with ADVFN, Wilkins explained that his decision to join Pantheon followed a detailed examination of its technical data, seismic information, historical work and development plans. Having spent more than four decades evaluating opportunities and delivering projects across the industry, he said the quality of the assets and the strength of the team convinced him that Pantheon had the potential to progress to its next stage of development.

    Wilkins initially joined the board in March before subsequently taking on the role of CEO. His enthusiasm for the opportunity is clear, with his experience bringing an important perspective as the company advances its strategy.

    A Substantial Resource Base

    At the heart of Pantheon Resources’ investment proposition is its significant acreage position on Alaska’s North Slope.

    According to Wilkins, the company holds approximately 258,000 acres associated with more than three billion barrels of oil equivalent in contingent resources (2C). This provides a substantial resource base across its Alaskan portfolio, with the Kodiak and Ahpun projects central to its development plans.

    A key factor in understanding the opportunity is the improvement in seismic technology. Wilkins explained that earlier seismic data, including a dataset from 2016, had been difficult to interpret clearly. Advances in technology and the reprocessing of this information have improved the company’s understanding of the subsurface, helping to identify potential resource locations and inform future well planning.

    This improved technical understanding is an important part of Pantheon’s strategy. Better interpretation of the available data can help the company refine its development plans and make more informed decisions as it evaluates how to progress its assets.

    For investors, the combination of a large acreage position and improved subsurface imaging provides important context for understanding the scale of the opportunity Pantheon is pursuing.

    Alaska Attracts Renewed Industry Interest

    Wilkins believes the timing is particularly attractive for companies operating in Alaska, pointing to several developments that are bringing the region back into focus.

    One factor is the oil and gas industry’s continuing search for substantial resource opportunities. After a decade of significant activity in shale plays, Wilkins believes companies are increasingly looking towards the longer-term potential of other regions capable of supporting future energy production.

    Alaska’s North Slope offers that potential, with Pantheon holding a significant acreage position in an established energy-producing region.

    Technological improvements are also helping unlock a better understanding of Alaska’s resources. As seismic interpretation becomes more sophisticated, companies can reassess previously identified opportunities and improve their understanding of the geology.

    For Pantheon, these developments reinforce the importance of its technical work and the potential value of its extensive acreage.

    Infrastructure Could Be a Strategic Advantage

    Another important element of the story is the proposed Alaska LNG project, which Wilkins highlighted as a significant development for the region.

    The project, associated with Glenfarne, is intended to help bring Alaska’s substantial natural gas resources to market, supporting energy supply for both domestic and international customers.

    Wilkins noted that the proposed pipeline route passes through Pantheon’s acreage, potentially providing an important infrastructure connection for the company’s assets.

    Access to suitable infrastructure is a key consideration for oil and gas developments, particularly in remote regions where transporting resources to market can be challenging. The prospect of additional infrastructure in Alaska therefore represents an important part of the wider regional opportunity.

    While the commercial implications for Pantheon will depend on the development of the project and the company’s own plans, the proposed pipeline route highlights the strategic relevance of its acreage within the evolving North Slope energy landscape.

    The combination of improved seismic data, substantial resources and potential access to new infrastructure gives investors several important factors to consider when evaluating Pantheon’s position in Alaska.

    Experienced Leadership Focused on the Next Stage

    Wilkins’ appointment also brings a renewed focus on execution and the development of Pantheon’s strategy.

    His decision to return from retirement followed a direct assessment of the company’s technical position and the people responsible for advancing its projects. He was particularly encouraged by the quality of the team, describing it as comparable to, or better than, others he had worked with throughout his career.

    That endorsement is significant because the next stage of Pantheon’s progress will require the company to translate its technical understanding into a clear and disciplined development strategy.

    Wilkins brings extensive industry experience to that challenge, alongside an enthusiasm for the company’s assets and the broader outlook for Alaska.

    His comments suggest that Pantheon’s opportunity is not simply about the scale of its resource base, but also about how technological advances, infrastructure developments and experienced leadership can combine to support the next phase of its development.

    Pantheon Resources Looks to Alaska’s Next Chapter

    Pantheon Resources is operating at a time when Alaska is attracting renewed attention from the energy industry. Improvements in seismic technology are providing a clearer understanding of its subsurface potential, while proposed LNG infrastructure could help reshape the region’s energy landscape.

    Against this backdrop, Pantheon’s approximately 258,000-acre position and the more than three billion barrels of oil equivalent in resources cited by Wilkins provide a substantial foundation for its strategy.

    For Wilkins, the decision to return to the industry reflects his conviction in the quality of the assets and the team working to develop them.

    The company’s challenge now is to build on its technical work, advance its development plans and establish how its resource base can be progressed commercially.

    With an experienced CEO at the helm and its assets situated within a region attracting fresh industry interest, Pantheon Resources offers investors a story centred on resource potential, technological progress and Alaska’s evolving energy infrastructure.

    For more information visit – https://www.pantheonresources.com/

  • ADVFN Expands Mobile App With Advanced Charts, Options Data, Ownership Information and New Investor Tools

    ADVFN Expands Mobile App With Advanced Charts, Options Data, Ownership Information and New Investor Tools

    ADVFN has introduced a series of updates to its mobile application, expanding the range of financial data, research tools and personalisation features available to investors. The additions include advanced charting capabilities, options data for U.S. equities, company ownership information, insider transaction records, expanded financial data, customisable notifications and Dark Mode.

    The updates are designed to give users access to more detailed market information and company research tools directly from their mobile devices, while improving navigation and control over the app’s functionality.

    Advanced Charting Tools and Full-Screen Analysis

    One of the additions is an enhanced charting experience, providing investors with more ways to examine share price movements and market trends.

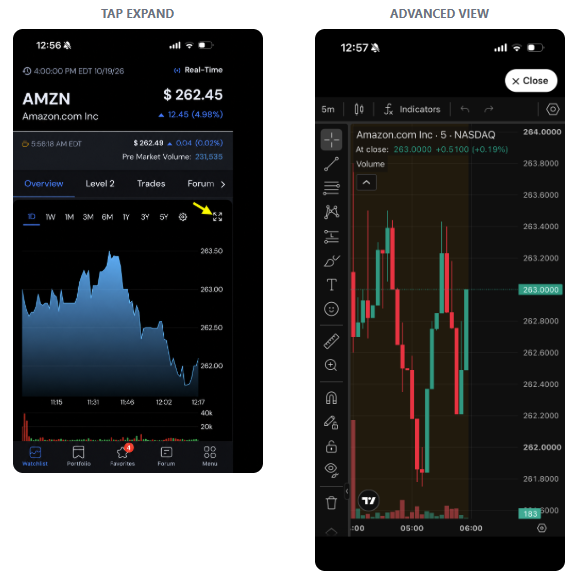
    The updated charts include additional controls and a full-screen advanced chart view, allowing users to explore price activity in greater detail.

    Investors can access the feature by opening a company or financial instrument’s page, selecting the Chart section and tapping the expand icon in the upper-right corner. This opens the advanced chart interface, providing a larger workspace for market analysis.

    ADVFN app charting advanced view

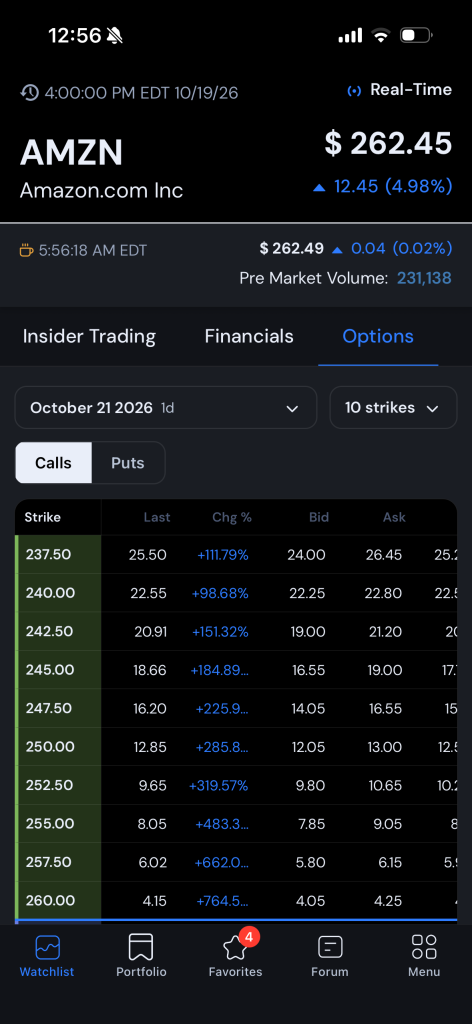
    Options Chain Data for U.S. Equities

    ADVFN has also introduced options chain information for supported U.S.-listed equities, allowing investors to examine options contracts within the mobile application.

    The new Options section enables users to select expiration dates, switch between call and put options, and review available strike prices and contracts.

    The feature provides access to options information alongside the underlying equity’s market data, reducing the need to navigate between different research platforms.

    To access the information, users can open a supported U.S. stock, select the Options tab and choose the relevant expiration date and contract type.

    ADVFN app options chain

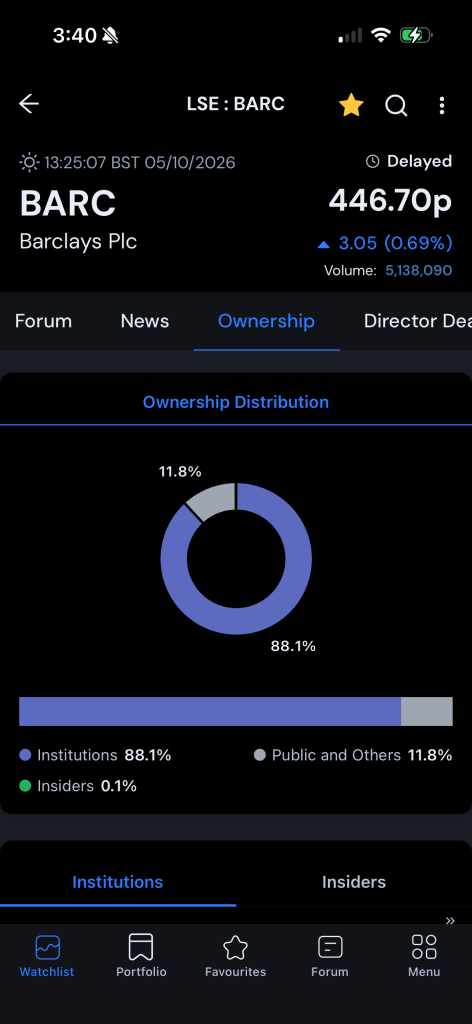
    Company Ownership and Institutional Holdings

    A new Ownership tab provides additional information about the shareholder structure of companies and other supported securities.

    Investors can review institutional, insider and public ownership information, providing a breakdown of the different categories of shareholders.

    The feature is accessible directly from a symbol’s page by selecting Ownership.

    The addition complements the app’s expanded company statistics, which include institutional holdings data and other measures relevant to company research.

    ADVFN app ownership

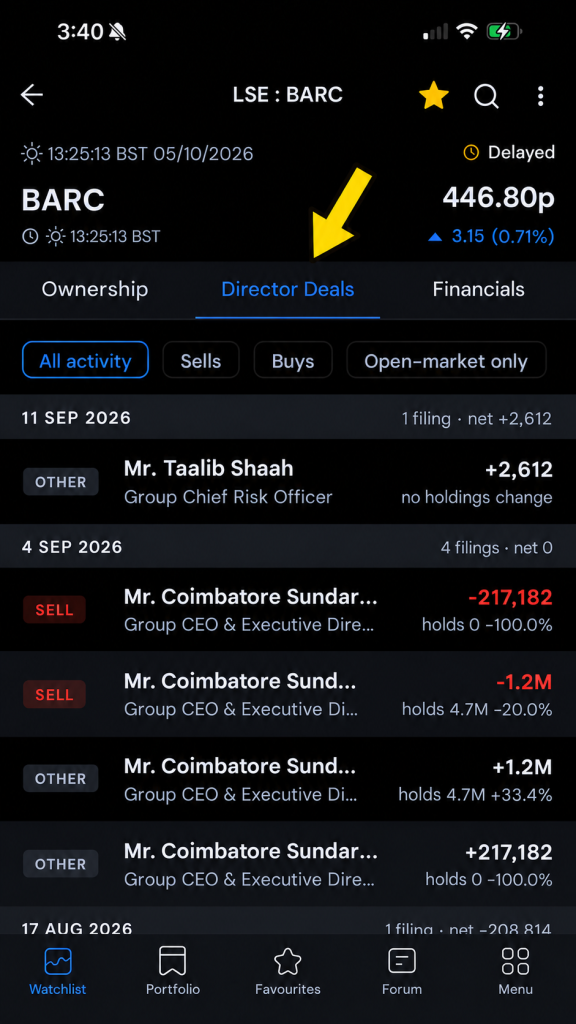
    Insider Transactions and Director Dealings

    The updated application also provides access to historical insider transactions, allowing users to review buying and selling activity involving company insiders.

    Available through the Director Deals section of a symbol’s page, the feature includes filtering options for all transactions, purchases, sales and open-market activity.

    This allows investors to examine reported insider dealings separately from other company information and assess transaction histories as part of their research.

    ADVFN app director deals

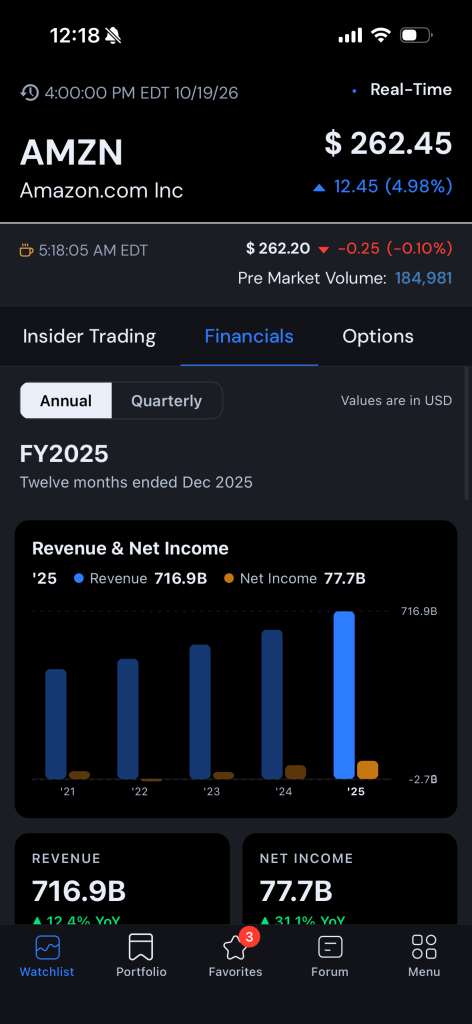
    Expanded Financial Statements and Company Fundamentals

    ADVFN has increased the amount of company financial information available through the mobile app, adding further fundamental data and key statistics.

    The Financials section provides access to available company financial information directly from individual symbol pages, while the General section includes additional company metrics.

    ADVFN app financials

    Among the expanded data points are Beta, Float, Institutional Holdings and valuation information, alongside other company statistics.

    Beta provides a measure of a security’s historical sensitivity to broader market movements, while Float represents the shares generally available for public trading. Institutional Holdings data offers information about ownership by investment institutions.

    By bringing these metrics together with financial information and market prices, the app allows investors to access multiple aspects of company research within the same interface.

    ADVFN app financial data

    Customisable Notifications and Market Alerts

    The updates also introduce additional control over notifications, allowing users to manage the types of alerts they receive.

    Notification settings cover forum activity, price alerts, private messages and news relating to selected securities.

    Users can enable or disable individual notification categories through Menu, App Settings and Notifications.

    The Manage Symbols function provides additional control over which securities are included in news notifications, allowing investors to tailor updates to the companies and instruments they follow.

    ADVFN app notifications

    Dark Mode and Display Personalisation

    ADVFN has introduced Dark Mode as an alternative display option within the mobile application.

    The feature allows users to switch between light and dark interfaces according to their viewing preferences.

    Dark Mode can be enabled or disabled directly from the app’s Menu, giving users control over the appearance of the platform without changing their market data or research settings.

    ADVFN app light and dark modes

    Continued Development of ADVFN Mobile

    The combined updates expand several areas of the ADVFN mobile experience, including technical analysis, derivatives information, shareholder research, financial fundamentals and notification management.

    The introduction of advanced charts and U.S. equity options chains extends the app’s market analysis capabilities, while ownership data, insider transactions and additional financial metrics provide more information for company-level research.

    Meanwhile, customisable notifications and Dark Mode give users greater control over how they interact with the platform.

    ADVFN has indicated that further improvements are planned as it continues developing the mobile application, with an emphasis on expanding available market data, research functionality and overall performance. The latest features form part of the company’s ongoing development of its mobile services, bringing additional tools and financial information into a single application for investors monitoring markets and researching securities on the move.

    Get the ADVFN app from the Apple store and Google Play

  • Wall Street Futures Edge Higher as Technology Shares Recover Ahead of Fed Decision: Dow Jones, S&P, Nasdaq

    Wall Street Futures Edge Higher as Technology Shares Recover Ahead of Fed Decision: Dow Jones, S&P, Nasdaq

    U.S. equity futures indicated further gains ahead of Tuesday’s opening bell, following a recovery in the previous session that lifted the Nasdaq Composite, S&P 500 and Dow Jones Industrial Average.

    Developments involving artificial intelligence companies and quarterly earnings announcements provided additional information for investors, while the Federal Reserve’s upcoming interest rate decision remained a focus.

    Anthropic’s public filing for an initial public offering and a new investment agreement involving Nvidia and Meta Platforms contributed to renewed attention on AI-related equities.

    Meanwhile, JetBlue Airways and Corning advanced in premarket trading, while Whirlpool declined following its latest financial announcement.

    Why Are U.S. Stock Futures Moving Higher?

    Futures linked to the principal U.S. equity indices pointed to gains after Monday’s market recovery.

    The advance followed two consecutive sessions of losses late in the previous week, when concerns about debt-financed AI infrastructure spending affected technology shares.

    Investors subsequently returned to selected stocks that had declined during the selloff.

    The recovery coincided with developments involving Anthropic, Nvidia and Meta, alongside a decline in crude oil prices.

    However, the pending Federal Reserve announcement remained a potential constraint on trading activity ahead of Wednesday’s policy decision.

    Anthropic IPO Filing Draws Attention to AI Companies

    Anthropic publicly filed for an initial public offering, adding to investor attention on the artificial intelligence industry.

    The filing followed a period of market concern about the amount of borrowing being used to finance AI infrastructure expansion.

    Investors have been assessing the financial commitments associated with data processing capacity, computing infrastructure and the development of advanced AI systems.

    The IPO announcement provided another development for market participants evaluating the industry’s investment requirements and commercial prospects.

    The news also coincided with renewed buying interest in technology-related shares during Monday’s session.

    Nvidia Announces $3 Billion Investment in Meta

    Nvidia (NASDAQ:NVDA) and Meta Platforms (NASDAQ:META) announced plans to expand their existing collaboration on Muse and related artificial intelligence models.

    Under the arrangement, Nvidia said it would invest $3 billion in Meta.

    The investment forms part of Meta’s plans to raise as much as $95 billion through equity financing.

    The agreement represents an expansion of the companies’ work on artificial intelligence technology.

    It also comes as investors continue to examine the financing structures and spending commitments of businesses developing AI models and supporting infrastructure.

    JetBlue Shares Jump While Corning Also Advances

    JetBlue Airways (NASDAQ:JBLU) shares rose 13.9% in premarket trading after the airline published its third-quarter financial results.

    Although the company reported a larger quarterly loss than analysts had forecast, it also indicated that operating margins were expected to expand further during the fourth quarter.

    Corning (NYSE:GLW) also recorded a notable premarket increase.

    The glass manufacturer reported third-quarter revenue and earnings above analyst consensus estimates.

    The two companies were among those recording gains following their earnings announcements ahead of Tuesday’s regular trading session.

    Whirlpool Falls After Third-Quarter Results

    Whirlpool (NYSE:WHR) shares declined 7.2% before the opening bell.

    The appliance manufacturer reported third-quarter results below Wall Street expectations and lowered its full-year revenue forecast.

    The reduction in guidance accompanied the company’s quarterly earnings announcement and contributed to the information investors were assessing before the session.

    Whirlpool’s decline contrasted with the gains recorded by JetBlue and Corning, demonstrating differing share price reactions during the earnings reporting period.

    Federal Reserve Expected to Keep Interest Rates Unchanged

    The Federal Reserve is scheduled to announce its monetary policy decision on Wednesday.

    Market participants widely expect the central bank to leave interest rates unchanged.

    Attention will therefore extend beyond the decision itself to the accompanying statement, particularly any indications about the future direction of borrowing costs.

    Investors will be assessing the Federal Reserve’s assessment of economic conditions and the factors likely to influence subsequent policy decisions.

    The approaching announcement could contribute to relatively limited trading activity ahead of Wednesday.

    Nasdaq and S&P 500 Recover From Recent Lows

    Wall Street recorded gains on Monday after the principal indices declined during the previous Thursday and Friday.

    The Nasdaq Composite rose 214.04 points, or 0.8%, to 26,169.38.

    The S&P 500 increased 53.09 points, or 0.7%, to 7,676.77.

    The Dow Jones Industrial Average added 146.32 points, or 0.3%, closing at 52,361.58.

    All three indices ended the session higher, although they finished below their intraday highs.

    The rebound followed a decline that had taken the Nasdaq to its lowest closing level since early August and the S&P 500 to its lowest closing level in one month.

    Buying interest included shares that had experienced price declines during the preceding sessions.

    Crude Oil Declines as Saudi Arabia and Iran Hold Talks

    U.S. crude oil futures fell 1.5% amid reports of diplomatic discussions concerning the Middle East conflict.

    Saudi Defense Minister Prince Khalid bin Salman travelled to Tehran to meet senior Iranian officials and discuss efforts to reduce regional tensions.

    The development coincided with a decline in crude oil prices and a recovery in U.S. equities.

    Investors continued to monitor developments affecting the conflict and their implications for energy supplies and prices.

    Technology Sectors Record Broad Gains

    Technology-related stocks contributed to Monday’s market advance.

    The NYSE Arca Networking Index gained 2.9%, while the Philadelphia Semiconductor Index increased 2.8%.

    Computer hardware and software stocks also advanced during the session.

    Oil services companies recorded gains, while brokerage shares declined.

    The sector performance showed renewed buying activity in semiconductor and networking stocks following the technology sector’s losses late in the previous week.

    What Could Influence Wall Street’s Next Trading Session?

    U.S. equity futures suggested that Monday’s recovery could continue into Tuesday’s regular trading session.

    The market backdrop included developments involving Anthropic, Nvidia and Meta, as well as premarket movements following the latest corporate earnings announcements.

    Lower crude oil prices and diplomatic activity in the Middle East were also among the factors being monitored.

    The Federal Reserve’s Wednesday policy announcement remains a principal upcoming event, with investors awaiting both the interest rate decision and any guidance contained in the accompanying statement.

  • European Stocks Mixed as HSBC Earnings and French Protests Weigh on Sentiment: DAX, CAC, FTSE100

    European Stocks Mixed as HSBC Earnings and French Protests Weigh on Sentiment: DAX, CAC, FTSE100

    European stock markets traded in mixed territory on Tuesday as investors assessed quarterly corporate earnings, political unrest in France and new economic data from the United Kingdom.

    London’s FTSE 100 declined 0.8%, with banking group HSBC among the notable fallers following its third-quarter earnings announcement. Germany’s DAX advanced 0.4%, while France’s CAC 40 gained 0.5%.

    Investor attention also turned to continuing demonstrations in France, where student leaders pledged further protests despite government concessions on education. Meanwhile, UK shop price inflation accelerated to its highest level in two and a half years.

    French Consumer Confidence Falls to Lowest Level Since 2013

    France’s national statistics agency, INSEE, reported that consumer confidence declined in October to its lowest level since June 2013.

    The deterioration came amid widespread protests over education, living costs and government policy.

    French student leaders indicated that demonstrations would continue despite concessions announced by the government in an effort to address the unrest.

    The developments added to the economic and political issues facing France, although the CAC 40 advanced 0.5% during Tuesday’s session.

    UK Shop Price Inflation Accelerates to 2.1%

    In the United Kingdom, the British Retail Consortium reported an increase in annual shop price inflation during October.

    Its shop price index rose 2.1% year over year, compared with a 1.4% increase in September.

    The October reading represented the highest rate of shop price inflation in two and a half years.

    The figures provided further evidence of rising retail prices as investors monitored inflation developments and their potential implications for consumer spending.

    HSBC and Reckitt Benckiser Decline Following Earnings Updates

    HSBC (LSE:HSBA) shares moved lower after the banking group reported third-quarter profit slightly below market expectations.

    The results contributed to the decline in London’s FTSE 100, which fell 0.8%.

    Consumer goods group Reckitt Benckiser (LSE:RKT) also recorded a share price decline after reducing its annual sales guidance.

    The company reported third-quarter sales below expectations, citing an unexpected slowdown in its US business.

    The revised outlook reflected weaker trading conditions in that market during the reporting period.

    Beiersdorf and Orange Shares Fall Despite Different Earnings Developments

    German consumer goods manufacturer Beiersdorf (TG:BEI) declined after reporting third-quarter sales below analyst expectations.

    French telecommunications group Orange (EU:ORA) also traded lower, despite announcing higher quarterly revenue and increasing its 2026 core earnings growth target.

    The contrasting financial developments highlighted differing investor responses to corporate results across European markets.

    While Beiersdorf reported a sales shortfall, Orange’s share price declined despite improvements in its reported revenue and annual earnings outlook.

    RWS Holdings Advances Following Return to Organic Revenue Growth

    RWS Holdings (LSE:RWS), the London-listed provider of AI-related solutions, recorded a share price increase after reporting an improvement in organic revenue.

    The company said organic revenue rose approximately 3% for the period ending September 30, following a decline in the preceding year.

    The update indicated a return to organic revenue growth during the reported period.

    RWS was among the London-listed companies trading higher despite the broader decline in the FTSE 100.

    Porsche and Alfa Laval Gain Following Operating Updates

    Porsche (TG:PAH3) shares advanced after the luxury sports car manufacturer reaffirmed its full-year 2026 outlook.

    The company also reported a substantial recovery in operating profit for the first nine months of the year.

    Swedish industrial group Alfa Laval (TG:AA9) moved higher after announcing record order intake during the third quarter.

    The companies’ operating updates coincided with share price increases during Tuesday’s European trading session.

    Novartis Rises After Upgrading Annual Profit Outlook

    Swiss pharmaceutical group Novartis (TG:NOT) recorded a notable share price increase after raising its full-year core operating income guidance.

    The company revised its expectations following third-quarter sales growth and improved core operating profitability.

    Novartis now expects annual core operating income to remain broadly unchanged or increase by a low single-digit percentage at constant currencies, compared with its previous forecast of a low single-digit decline.

    The revised outlook contributed to the company’s share price advance.

    European Markets Reflect Divergent Corporate Results and Economic Conditions

    Tuesday’s European trading session showed differences between national indices and individual company performances.

    The FTSE 100 declined 0.8%, while Germany’s DAX gained 0.4% and France’s CAC 40 advanced 0.5%.

    Corporate earnings announcements influenced individual shares, with HSBC, Reckitt Benckiser, Beiersdorf and Orange declining, while RWS Holdings, Porsche, Alfa Laval and Novartis advanced.

    Investors also assessed France’s decline in consumer confidence, continuing protests and the acceleration of UK shop price inflation.

    These developments formed the economic and corporate backdrop to the mixed performance of European equities.

  • US Markets Assess Anthropic IPO Plans, Boeing Results and Fed Policy as Stock Futures Slip: Dow Jones, S&P, Nasdaq, Wall Street

    US Markets Assess Anthropic IPO Plans, Boeing Results and Fed Policy as Stock Futures Slip: Dow Jones, S&P, Nasdaq, Wall Street

    US equity futures moved modestly lower on Tuesday, 27 October 2026, following gains in the previous trading session that were accompanied by advances in artificial intelligence-related shares. Anthropic’s initial public offering filing drew attention to revenue growth in the AI industry, while investors prepared for Boeing’s quarterly results and the Federal Reserve’s latest monetary policy meeting.

    At 03:56 ET (07:56 GMT), S&P 500 futures were down 11 points, or 0.1%, and Nasdaq futures had declined 125 points, equivalent to 0.4%. Dow Jones futures showed little movement.

    The previous session had ended with gains across Wall Street’s major benchmarks. The Nasdaq Composite rose 0.83%, the S&P 500 increased 0.7% and the Dow Jones Industrial Average advanced 0.3%.

    Technology and semiconductor shares contributed to those increases after Anthropic (NASDAQ:ANT) disclosed first-half revenue of $1.16 billion in documents submitted for its proposed stock market listing.

    The market was also awaiting earnings from Boeing (NYSE:BA), Coca-Cola, Corning, Visa and Seagate Technology, alongside developments involving US monetary policy, international elections and energy markets.

    US Equity Futures Indicate a Lower Opening

    Futures linked to the main US stock indices declined slightly in early Tuesday trading.

    S&P 500 futures fell 0.1%, while contracts tracking the Nasdaq dropped 0.4%. Dow Jones futures remained broadly unchanged.

    The movements followed a session in which technology shares contributed to gains in the main US indices.

    The Nasdaq Composite advanced 0.83% on Monday, compared with increases of 0.7% for the S&P 500 and 0.3% for the Dow Jones Industrial Average.

    The latest trading activity came ahead of several corporate earnings announcements and the Federal Reserve’s two-day policy meeting.

    Market participants expected the central bank to maintain its current interest rate settings.

    Attention was also directed toward the Fed’s comments on inflation, economic conditions and the possible direction of monetary policy at subsequent meetings.

    Anthropic Discloses $1.16 Billion in First-Half Revenue

    Anthropic (NASDAQ:ANT) released financial and operational information as part of its preparations for an initial public offering.

    The San Francisco-based company, which develops the Claude artificial intelligence chatbot, reported revenue of $1.16 billion for the six months ended June 2026.

    The amount represented an increase of 1,304% compared with the same period in 2025.

    The approximately 400-page filing provided details about the company’s business model, financial performance and operational risks.

    Anthropic remained unprofitable, reflecting expenditure associated with developing and operating advanced AI systems.

    Analysts suggested that the company could complete its public offering as soon as November.

    Reports indicated a potential valuation of between $1.5 trillion and $2 trillion, although neither the final valuation nor the listing date had been established.

    The proposed transaction attracted attention because of the company’s reported revenue growth and the scale of its potential entry into public equity markets.

    Semiconductor Companies Record Gains

    Shares of semiconductor manufacturers and related businesses advanced following Anthropic’s filing.

    The iShares Semiconductor ETF gained almost 3% on Monday, while the Philadelphia Semiconductor Index increased 2.82%.

    Nvidia, Broadcom, Advanced Micro Devices and Micron were among the companies whose shares finished higher.

    The gains coincided with renewed investor attention to businesses supplying the computing infrastructure used in artificial intelligence applications.

    Semiconductors are essential components in data centres and other systems used to train and operate AI models.

    The sector had experienced volatility during the previous week as investors assessed the financing requirements associated with expanding AI infrastructure.

    Anthropic’s filing provided additional financial information about a company operating in this market, although it also identified risks associated with the technology.

    These included the possibility of AI systems operating beyond human control and limitations in obtaining insurance coverage for certain potential events.

    Anthropic Listing Could Influence Future AI Offerings

    Evercore ISI analysts commented on the potential implications of Anthropic’s proposed public listing.

    “A successful listing could also encourage more AI companies to test the public markets, accelerate broader IPO momentum, and reinforce the view that the AI trade still has room to run,” the analysts wrote.

    Their assessment focused on the possibility that Anthropic’s transaction could provide a reference point for other artificial intelligence businesses considering public market financing.

    The proposed listing comes as investors evaluate the relationship between rapid revenue growth, operating losses and capital requirements across the AI industry.

    A completed offering could provide additional information about the valuation that public market investors assign to a company focused on developing large artificial intelligence models.

    However, the transaction’s final terms and timing remained unconfirmed.

    AI Infrastructure Financing Remains in Focus

    Separate announcements from Meta Platforms and SpaceX highlighted additional financing activity associated with artificial intelligence.

    Meta Platforms said it planned to raise $95 billion to support its AI objectives.

    SpaceX Chief Executive Elon Musk disclosed that the company had reached a $40 billion debt agreement related to purchasing AI chips.

    The announcements concern investments in the computing infrastructure required to support artificial intelligence operations.

    Companies developing and operating AI systems require substantial processing capacity, including specialised semiconductors and data centre facilities.

    The associated spending has become an important consideration for investors assessing capital expenditure, borrowing requirements and future financial returns.

    The source did not provide detailed financing terms or implementation schedules for the two announcements.

    Boeing Earnings Expected Before Market Open

    Boeing (NYSE:BA) was scheduled to release its third-quarter results before the opening of US stock markets.

    According to LSEG estimates cited by Reuters, analysts expected the aircraft manufacturer to report a loss of $0.21 per share.

    Investors were preparing to examine the company’s free cash flow, production performance and plans for additional defence manufacturing facilities.

    During the third quarter, Boeing secured the US Navy’s sixth-generation F/A-XX fighter aircraft contract.

    The company also received certification for the final two versions of its 737 MAX aircraft.

    Boeing delivered 363 737 MAX aircraft during the first nine months of 2026, its highest delivery pace for that period.

    These operational developments formed part of the information available ahead of the earnings release.

    Free cash flow was expected to receive particular attention because it provides an indication of the company’s cash generation after capital expenditure.

    The results were also expected to offer further details about Boeing’s manufacturing and investment priorities.

    Additional Earnings Reports Scheduled Throughout Tuesday

    Several other major US companies were scheduled to publish quarterly financial results.

    Coca-Cola and Corning were expected to report before the opening bell.

    Visa and Seagate Technology were scheduled to release their figures after regular trading ended.

    The companies operate across different industries, providing investors with information about consumer spending, industrial technology, payments and data storage.

    Their financial statements will offer updated measures of revenue, profitability and business activity.

    The earnings calendar coincides with the Federal Reserve meeting, making corporate performance and monetary policy two important areas of attention during the week.

    Brazilian Equities React to Presidential Election Result

    International political developments also featured in market trading.

    Brazilian stocks declined following the re-election of President Luiz Inácio Lula da Silva.

    The result prompted investors to assess the country’s fiscal outlook and the potential implications of government economic policy.

    Brazil’s public finances remained an area of attention as market participants considered the direction of future fiscal measures.

    The source did not provide a specific percentage decline for Brazilian equity benchmarks.

    The election result occurred during a period in which investors were also monitoring political events in Israel and the approaching US midterm elections.

    Israeli Election Takes Place During Middle East Conflict

    Israel held parliamentary elections on Tuesday, with debate focused partly on Prime Minister Benjamin Netanyahu’s leadership and national security policy.

    The vote was the first since the Hamas attack of 7 October 2023.

    It also took place during the eighth month of the conflict involving Israel, the United States and Iran.

    The election attracted international attention because of its possible implications for regional security and diplomatic relations.

    Opposition figure Gadi Eisenkot criticised Netanyahu’s approach, saying the prime minister was offering “eternal war.”

    Netanyahu’s supporters defended the government’s military operations involving Iran, Hamas and Hezbollah in Lebanon.

    The outcome remained undetermined at the time of the report.

    Political developments in Israel were among several international events being monitored alongside the US midterm elections scheduled for the following week.

    Brent and WTI Crude Prices Move Higher

    Oil prices increased during early Tuesday trading as investors assessed diplomatic developments in the Middle East.

    At 03:52 ET, Brent crude futures were up 0.4% at $116.28 per barrel.

    West Texas Intermediate futures gained 0.5% to $102.24 per barrel.

    The increases followed declines in oil prices during Monday’s session.

    Brent had reached a six-month high the previous week amid concerns about attacks on energy infrastructure and commercial shipping.

    The latest movements reflected continued uncertainty surrounding the conflict involving Iran and the possible effects on regional energy supplies.

    Diplomatic initiatives aimed at reducing tensions were also being assessed by market participants.

    Regional Diplomatic Talks Continue

    Senior officials from Saudi Arabia, Turkey and Pakistan met Iranian leaders in Tehran on Monday.

    The discussions were intended to reduce tensions and establish channels for further negotiations.

    Qatari officials were also engaging with Tehran as part of efforts to prevent a broader regional escalation.

    The diplomatic activity took place during continuing military operations and concerns about the security of energy infrastructure and shipping routes.

    The source did not identify a formal agreement resulting from the latest meetings.

    For energy markets, the progress of negotiations remains relevant because developments in the region can influence expectations for oil production, transportation and international supply.

    Outlook for Wall Street and Global Markets

    US equity futures traded modestly lower following a session of gains in technology and semiconductor shares.

    Anthropic’s proposed IPO remained a focus after the company disclosed revenue growth of 1,304% to $1.16 billion for the first half of 2026.

    Investors were also preparing for Boeing’s earnings release, other major corporate reports and the Federal Reserve’s policy meeting.

    Political developments in Brazil and Israel, the upcoming US midterm elections and diplomatic efforts involving Iran added to the range of events being monitored.

    Brent crude futures traded at $116.28 per barrel and WTI at $102.24 per barrel during early Tuesday trading.

    Further corporate earnings, monetary policy announcements and international developments will provide additional information for investors during the remainder of the week.

  • Market Open: HSBC Profit Rises, Shoe Zone Revenue Falls

    Market Open: HSBC Profit Rises, Shoe Zone Revenue Falls

    FTSE 100 retreats after a flat open as HSBC revenue misses forecasts and Shoe Zone sales decline. Brent crude falls amid Iran diplomatic efforts.

    Market Overview

    The FTSE 100 opened marginally higher at 10,767.81, up 0.0045 per cent from its previous close, before falling to 10,655.50 as HSBC shares came under pressure following the bank’s third-quarter results. Investors also remained cautious ahead of the UK Budget and Federal Reserve policy decisions. European markets declined, with the Euronext 100 opening 0.03 per cent lower at 1,856.73 before slipping to 1,852.59, while Germany’s DAX fell 0.10 per cent to 25,384.78. Wall Street closed higher overnight, with the Nasdaq Composite advancing to 26,169.38 and the S&P 500 rising to 7,676.77, supported by technology shares.

    Commodity markets were mixed, with copper and gold advancing while Brent crude and natural gas declined. Oil prices remained under pressure as diplomatic efforts involving Iran eased concerns about potential supply disruptions. Bitcoin weakened against sterling. In currency markets, the pound strengthened against the US dollar, Swiss franc and Australian dollar, while gaining against the Japanese yen and remaining unchanged against the euro. Investors continued to assess monetary policy expectations, geopolitical developments and corporate earnings.


    Market Numbers

    FTSE 100: Up (+0.0045%), 10,767.81
    Euronext 100: Down (-0.03%), 1,856.73
    DAX: Down (-0.10%), 25,384.78
    NASDAQ: Up, 26,169.38
    S&P 500: Up, 7,676.77


    In the Headlines

    Profit Rises, Revenue Misses – HSBC Holdings (LSE:HSBA)
    HSBC reported a 32 per cent increase in third-quarter pretax profit to $9.6 billion, broadly in line with expectations, while revenue rose 5 per cent to $18.6 billion but fell short of forecasts. The banking group also announced a share buyback of up to $1 billion, although slower growth in its wealth business and the revenue shortfall weighed on investor sentiment.

    Revenue Declines, Loss Reported – Shoe Zone (LSE:SHOE)
    Footwear retailer Shoe Zone reported a 4.5 per cent decline in full-year revenue to £142.4 million and an adjusted loss of £1 million for FY2026. The results highlight continued trading pressures facing the retailer, bringing profitability and cost management into focus.


    Currencies (vs GBP)

    USD: Down (-0.16%), $1.3324
    CHF: Down (-0.09%), Fr.1.1036
    EUR: Unchanged (0.00%), €1.1943
    JPY: Down (-0.02%), ¥210.205
    AUD: Down (-0.17%), $1.8979
    Bitcoin (BTC/GBP): Down (-0.30%), £59,789.00


    Commodities

    Copper: Up
    Gold: Up
    Brent Crude: Down
    Natural Gas: Down