Blog

  • Wall Street Futures Gain as Treasury Yields Stay High; Costco Beats Quarterly Estimates: Dow Jones, S&P, Nasdaq

    Wall Street Futures Gain as Treasury Yields Stay High; Costco Beats Quarterly Estimates: Dow Jones, S&P, Nasdaq

    US equity futures traded higher on Friday as markets continued to assess a rise in Treasury yields alongside developments in crude oil and a new set of corporate updates.

    At 03:12 ET, Dow futures were 63 points higher, representing a 0.1% gain. S&P 500 futures also increased 0.1%, or 11 points, while Nasdaq 100 futures advanced 126 points, or 0.4%.

    Thursday’s regular session ended with mixed results. The Dow Jones Industrial Average and S&P 500 declined, while the Nasdaq Composite finished 0.01% higher.

    Government bond yields remained a focus after rising during the week as markets considered oil prices, US economic conditions and the outlook for Federal Reserve interest rates.

    “One important theme at the moment is that Treasuries continue to sell-off with oil but that breakevens aren’t moving, with pretty much all the move being driven by real yields,” Deutsche Bank analysts said.

    Treasury Yields Reach Multi-Year Highs

    The US 10-year Treasury yield ended Thursday at 5.2%, its highest level since 2007. The 30-year yield, meanwhile, reached its highest level since 2004.

    The 10-year yield recorded its largest two-day increase since US President Donald Trump’s announcement of the “Liberation Day” tariffs the previous year.

    Markets have been adjusting their expectations for Federal Reserve policy following the central bank’s 25-basis-point rate increase the previous week.

    According to the supplied information, energy-related inflation pressures were among the factors cited in connection with the rate decision.

    Higher oil prices have recently coincided with rising government bond yields and periods of weakness in equity markets. However, longer-term yields reflect a range of factors, including inflation expectations, economic conditions and expectations for monetary policy.

    Crude Oil Retreats Following Reports of US-Iran Discussions

    Oil prices moved lower on Friday as markets considered reports of negotiations between the United States and Iran over a possible phased arrangement involving the Strait of Hormuz.

    Crude benchmarks had climbed as much as 5% on Thursday before giving back part of those gains following reports of the discussions.

    Earlier in the session, Saudi Arabia said it had intercepted six ballistic missiles launched by Yemen’s Iran-backed Houthis towards locations including Taif and the Yanbu region.

    The incident followed earlier damage to Saudi Arabia’s East-West pipeline that had disrupted crude shipments to Yanbu, an export hub on the Red Sea connected to the country’s eastern oil-producing areas.

    Saudi Arabia had increased crude flows towards Yanbu, although tanker loadings had yet to return fully to previous levels, according to the supplied information.

    Subsequent reports said US and Iranian negotiators in New York were considering a phased framework that would involve Iran reopening the Strait of Hormuz in exchange for the lifting of the US economic blockade.

    The reports did not indicate that a final agreement had been reached.

    Musk Plans Further Expansion of Colossus 2

    Elon Musk outlined plans to expand the computing capacity of the Colossus 2 data centre in Tennessee through the addition of more Nvidia (NASDAQ:NVDA) processors.

    Musk said in a post on X that the facility has used 110,000 Nvidia GB200 chips alongside 440,000 GB300 chips.

    He said another 220,000 GB300 processors were expected to be operational by the following week, with a further 220,000 planned for November.

    “If we get lucky, yet another 220k GB300 by late December,” Musk said in response to a post about xAI’s computing infrastructure.

    Musk has previously called Colossus the “world’s largest AI supercomputer.” The original Colossus facility was built in 2024 to support the training of xAI’s Grok model.

    Costco Reports 11.2% Increase in Fourth-Quarter Net Sales

    Costco (NASDAQ:COST) reported fiscal fourth-quarter earnings and revenue above Wall Street estimates. Its shares were slightly lower in extended trading following the announcement.

    The warehouse retailer reported earnings per share of $6.75, exceeding the consensus forecast of $6.55.

    Revenue was $95.7 billion compared with analysts’ estimate of $94.85 billion.

    Net sales increased 11.2% to $93.9 billion during the 16-week quarter, up from $84.4 billion in the comparable period a year earlier.

    Adjusted earnings of $6.75 per share included a $0.15 non-recurring benefit from tariff refunds received during the quarter, partly offset by the reinvestment of some of those refunds in increased member value.

    Fourth-quarter comparable sales increased 9.4% as reported. Excluding changes in gasoline prices and foreign exchange rates, comparable sales rose 6.7%, compared with an analyst estimate of 6.44%.

    US comparable sales increased 10.7%, or 7.2% on an adjusted basis. Canadian comparable sales rose 5.0%, or 4.6% adjusted, while comparable sales in other international markets increased 7.0%, or 6.2% after adjustments.
  • European Gas Prices Fall More Than 8% This Week as LNG Shipping Routes Adjust

    European Gas Prices Fall More Than 8% This Week as LNG Shipping Routes Adjust

    European and British wholesale natural gas futures fell on Friday, putting both markets on course for their largest weekly declines since mid-June.

    The benchmark Dutch front-month TTF contract and the equivalent UK NBP wholesale gas contract each declined 3.2% during Friday’s session.

    Both benchmarks were on track for weekly losses of more than 8%, following increases earlier in September amid uncertainty surrounding energy supplies and shipping routes in the Middle East.

    The latest moves came as LNG carriers and commercial shipping operators adjusted transit routes around the Arabian Peninsula in response to disruption affecting regional maritime traffic.

    LNG Shipping Routes Adjust to Middle East Disruption

    Changes to shipping routes have provided indications that LNG cargoes can continue to reach destination markets despite disruption affecting some established transit routes.

    Gas markets have experienced significant volatility in recent weeks alongside developments involving the United States and Iran and concerns about the potential impact on energy infrastructure and shipping in the Persian Gulf.

    Friday’s decline also followed gains earlier in the month, with some market participants taking profits ahead of the weekend.

    No formal agreement between the United States and Iran has been reached, leaving the outlook for regional energy supplies dependent on further diplomatic and security developments.

    EU Gas Storage at Around 70% of Capacity

    European gas inventories remain below their levels from the corresponding period last year as the region approaches the winter heating season.

    Data from Gas Infrastructure Europe showed underground gas storage across the European Union at approximately 70% of total working capacity at the latest reading cited.

    Inventories were around 12 percentage points below levels recorded during the same period last year.

    The difference means European gas markets remain exposed to changes in winter demand and potential supply disruptions despite the recent decline in wholesale prices.

    Energy prices also remain relevant to the inflation outlook because changes in wholesale costs can feed through to consumer energy prices.

    The European Central Bank has identified energy-price volatility as a factor that can affect inflation, leaving developments in European gas markets among the variables being monitored by policymakers.

  • European Stocks Rise as Oil Prices Ease and Investors Monitor Bond Yields: DAX, CAC, FTSE100

    European Stocks Rise as Oil Prices Ease and Investors Monitor Bond Yields: DAX, CAC, FTSE100

    European equities moved higher on Friday, recovering from a near one-week low reached in the previous session as investors assessed lower crude oil prices alongside elevated government bond yields.

    The pan-European STOXX 600 rose 0.7%, leaving the index on course for a weekly gain of approximately 0.15%. If maintained through the close, the advance would end three consecutive weeks of declines.

    Germany’s DAX gained 0.8%, while France’s CAC 40 and the UK’s FTSE 100 each rose 0.5%. Italy’s FTSE MIB advanced 1%.

    Crude oil prices declined by around 1% during the session.

    Bond Yields Remain Elevated

    Despite Friday’s gains, European equities continued to face a backdrop of higher government bond yields as markets assessed expectations for monetary policy in the US and Europe.

    Sovereign bond yields have risen in recent sessions amid expectations that central banks could maintain tighter monetary policy in response to inflation.

    European markets are also monitoring regional natural gas inventories, which were reported to be around 12 percentage points below comparative levels, alongside developments affecting trade and energy supplies in the Middle East.

    Lower oil prices during Friday’s session coincided with gains across parts of the travel, leisure and industrial sectors, which are sensitive to changes in energy and input costs.

    “I would give sustained energy relief time to feed through to prices, then assess. Before supporting another hike, you really would want a clear case that existing policy is insufficient to bring underlying inflation down,” said Luke Davis, founder and chief market strategist at Bull Market Blueprint.

    Corporate Updates Support Individual Stocks

    Corporate earnings and company-specific developments also contributed to moves in individual European equities during the week.

    These developments came against a broader backdrop of rising sovereign bond yields in both the US and Europe.

    Rate-sensitive equities can be affected by changes in government bond yields because higher rates influence financing costs and the discount rates used in company valuations.

    Markets Monitor US-China Talks

    Investors were also assessing developments surrounding a meeting in Washington between US President Donald Trump and Chinese President Xi Jinping.

    Areas being monitored included trade relations, rare-earth supply chains and technology export rules.

    “Breakthroughs on long-standing disputes are unlikely, but the meeting could still be a symbolic step forward for future trade talks,” said Lukman Otunuga, head of market research at FXTM.

    Middle East Developments Remain in Focus

    Energy and currency markets also continued to monitor diplomatic and security developments in the Middle East.

    Although crude oil prices declined during Friday’s session, uncertainty remained around the potential for further disruption to energy supplies in the Persian Gulf.

    European natural gas storage levels were also being monitored as markets assessed the region’s energy supply outlook.

  • HSBC Upgrades BP and TotalEnergies as Oil and Gas Price Forecasts Rise

    HSBC Upgrades BP and TotalEnergies as Oil and Gas Price Forecasts Rise

    HSBC upgraded BP (LSE:BP.) and TotalEnergies (LSE:TTE) (EU:TTE) to Buy from Hold on Friday as the bank raised its oil, gas and refining assumptions and increased earnings and cash flow estimates across its global oil coverage.

    Analysts led by Kim Fustier increased their Brent crude assumption for 2026 to approximately $90 per barrel from $80 and raised their 2027 forecast to $85 from $65.

    The revisions reflect HSBC’s expectation of a partial and gradual recovery in flows through the Strait of Hormuz.

    The bank also increased its TTF gas price forecast for the second half of 2026 to $22.50 per million British thermal units from $16.70 and raised its 2027 estimate to $17 from $12.

    Earnings Estimates Raised Across Oil Sector

    Following the commodity price revisions, HSBC increased its earnings-per-share estimates across the sector by an average of 19% for 2026, 65% for 2027 and 33% for 2028.

    Cash flow per share estimates were raised by averages of 12%, 30% and 14%, respectively.

    According to HSBC, the largest revisions were made to international oil majors because of their combined exposure to upstream production, refining and trading activities.

    BP Price Target Raised to 640p

    HSBC increased its price target for BP to 640 pence from 570 pence, representing a difference of nearly 18% from the share price used in the bank’s analysis.

    The analysts said they expect BP “to be under much less strategic pressure to sell assets to reduce liabilities,” arguing that higher assumed oil prices mean deleveraging would be less dependent on asset disposals.

    HSBC said BP shares trade at an approximately 26% discount to Shell (LSE:SHEL) and TotalEnergies on a 2027 EV/DACF basis. Its new price target assumes that valuation gap narrows by half.

    The bank said it does not currently expect BP to resume share buybacks before 2028. However, the analysts said this assessment could change if management adopts “a more benign definition of ‘gearing’” that excludes hybrid securities or liabilities related to Macondo.

    TotalEnergies Target Increased to €93

    HSBC raised its price target for TotalEnergies to €93 from €80, representing a difference of 18.4% from the share price referenced in its analysis.

    The bank said its upgrade reflected a change in relative valuation, noting that TotalEnergies’ previous valuation premium to Shell “has disappeared.”

    HSBC also said TotalEnergies could increase its share buybacks in the future, although this remains an analyst expectation rather than company guidance.

    HSBC Retains Buy Rating on Shell, Repsol and Chevron

    HSBC maintained its Buy ratings on Shell, Repsol (TG:REP) and Chevron (NYSE:CVX).

    The bank increased its Chevron price target to $250 from $218 following revisions to its cash flow forecasts. HSBC also said Chevron has “the lowest” exposure to the Middle East among the five supermajors included in its comparison.

    HSBC expects Chevron to increase its annual share buyback run rate to $15 billion from between $10 billion and $12 billion.

    Eni (BIT:ENI), Equinor (NYSE:EQNR), Galp (EU:GALP) and ExxonMobil (NYSE:XOM) remain rated Hold, while OMV (TG:OMV) retains a Reduce rating.

    HSBC said Eni’s valuation “relative to peers is currently justified” following its year-to-date share-price performance and described the shares as “fairly valued.”

    HSBC Raises Distribution Assumptions

    Across its oil-sector coverage, HSBC increased its assumptions for shareholder distributions at most companies, with ExxonMobil and BP the exceptions.

    The bank said its revised target prices represent an average difference of 12% from prevailing share prices across the sector and 21% for companies carrying its Buy rating.

    Price targets, ratings and commodity forecasts represent HSBC analysts’ estimates and can change as market conditions and company performance develop.

  • Airbus Identifies A321neo Fuselage Quality Issue Affecting About 500 Aircraft – Report

    Airbus Identifies A321neo Fuselage Quality Issue Affecting About 500 Aircraft – Report

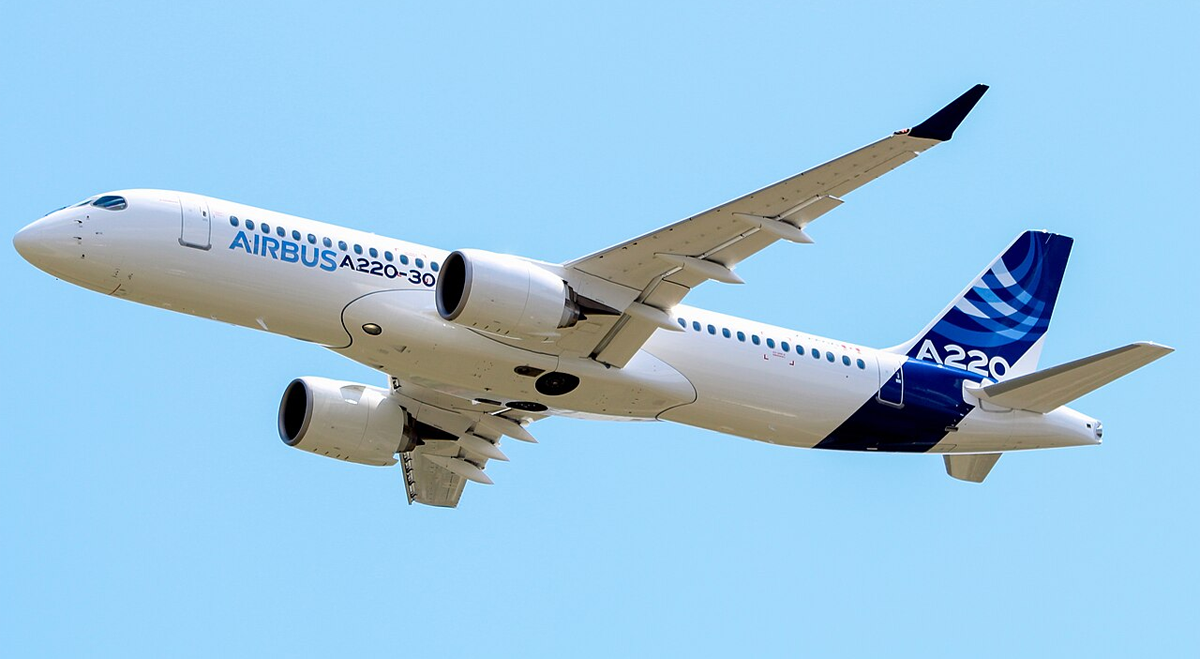
    Airbus (EU:AIR) has identified a fuselage quality issue affecting approximately 500 A321neo aircraft, Reuters reported, citing a source familiar with the matter.

    Around 250 of the affected aircraft are already in service, while a further 250 are in production, according to the report.

    The issue does not represent a safety risk and aircraft already in service can continue operating, Reuters reported.

    Issue Relates to Fuselage Stringer Coating

    Airbus identified a “deviation” in the surface protection, or coating, applied to stringers, structural components that run lengthways along the aircraft’s fuselage.

    The issue was identified during the summer and was first reported by aviation industry publication the Air Current.

    According to the report, the A321XLR, the longer-range variant of the A321neo, is not affected.

    Customers are continuing to accept deliveries of affected aircraft without additional work being required before handover. Airbus has also told airlines that there is no immediate requirement to repair aircraft already in service, the report said.

    European aviation regulators could subsequently issue a directive requiring repairs to be completed within a specified timeframe, according to Reuters.

    Previous A321neo Fuselage Issue Affected Deliveries

    The latest issue follows a separate fuselage-related quality problem involving the A321neo that Airbus reported in December.

    That issue involved defects in fuselage panels and was also described by Airbus as having no safety implications. Remedial work contributed to several months of delivery delays.

    The latest quality issue comes as Airbus works to increase narrow-body aircraft production from approximately 60 aircraft per month to a target of 75 per month.

  • FTSE 100 Rises 0.5% as Markets Assess US-Iran Talks and Hormuz Disruption

    FTSE 100 Rises 0.5% as Markets Assess US-Iran Talks and Hormuz Disruption

    The FTSE 100 rose 0.50% on Friday as investors assessed developments in US-Iran talks alongside reduced shipping traffic through the Strait of Hormuz and further regional security developments.

    As of 07:13 GMT, Germany’s DAX was up 0.66% and France’s CAC 40 had gained 0.40%.

    Sterling was little changed against the US dollar at $1.3223, down 0.01% during the session.

    US and Iran Discuss Phased Framework

    Iranian President Masoud Pezeshkian, speaking to the media on the sidelines of the UN General Assembly in New York, said Tehran wanted Washington to return to the Memorandum of Understanding “before the midterms.”

    In a separate interview with Fox News, Pezeshkian said “the framework was agreed upon” and that Iran “never sought anything more” than its entitlements under international law.

    According to sources cited by Reuters, US and Iranian negotiators have been discussing a phased framework that would involve Tehran reopening the Strait of Hormuz in exchange for Washington lifting its economic blockade.

    No final agreement was reported in the supplied information.

    Strait of Hormuz Traffic Declines

    Shipping activity through the Strait of Hormuz remained below recent levels.

    Reuters reported that nine vessels transited the waterway on Thursday, compared with a rolling 10-day average of approximately 18. Some vessels were believed to be operating with their transponders switched off.

    The UAE also suspended flights by Iranian carriers on Thursday, joining Oman, Iraq, Azerbaijan, Georgia and Turkmenistan in implementing new US secondary sanctions relating to Iranian aviation.

    US Senate Rejects War Powers Resolution

    In Washington, the US Senate voted 50-49 against a Democratic resolution that would have restricted President Donald Trump’s authority to continue the conflict with Iran.

    Four Republican senators voted in support of the resolution.

    Separately, Saudi Arabia, Türkiye and Pakistan announced plans for an urgent chiefs-of-staff meeting under the Mecca Joint Defence Agreement following Houthi strikes on Taif, Yanbu and military sites near the Saudi-Yemeni border.

    Qatar described the attacks as “a blatant violation of Saudi sovereignty.”

    Saudi Foreign Minister Prince Faisal bin Farhan also chaired a trilateral ministerial meeting during the UN General Assembly at which ministers affirmed Saudi Arabia’s right to self-defence under Article 51 of the UN Charter.

    UK Foreign Secretary Meets Iranian Counterpart

    UK Foreign Secretary Ed Miliband met Iranian Foreign Minister Abbas Araghchi in New York.

    According to a Foreign Office statement reported by Sky News, Miliband raised the importance of reopening the Strait of Hormuz and referred to the UK’s “unwavering resolve to combat threats from Iranian-linked groups on UK soil.”

    Oil Prices Fall While Gold Advances

    Brent crude declined 0.63% to $105.95 a barrel, while West Texas Intermediate fell 1.4% to $93.32.

    Gold prices moved higher, with futures up 0.32% at $4,311.50 and spot gold gaining 0.06% to $4,276.23.

  • Harworth Shares Rise 4.6% After Peel Pepper Raises Cash Offer to 187p

    Harworth Shares Rise 4.6% After Peel Pepper Raises Cash Offer to 187p

    Harworth (LSE:HWG) shares rose 4.6% to 186.2 pence after Peel Pepper (UK) Limited, a vehicle connected to Peel Holdings, increased its cash takeover proposal to 187 pence per share.

    The revised proposal, which the bidder has described as its best and final offer, values Harworth at approximately £631.7 million.

    Harworth’s board has unanimously recommended the revised proposal, having previously declined to recommend earlier approaches from Peel Pepper.

    Revised Offer Increases to 187p Per Share

    The new proposal represents an 8.4% increase from Peel Pepper’s previous offer of 172.5 pence per share.

    It also represents a 30.2% premium to Harworth’s closing share price of 143.6 pence immediately before the start of the offer period.

    Harworth’s directors said they had considered the certainty provided by the cash consideration alongside the execution risks associated with continuing the company’s standalone strategy before deciding to recommend the revised proposal.

    Peel Pepper Secures Acquisition Financing

    Peel Pepper plans to finance the proposed acquisition using its own resources together with debt facilities provided by HSBC UK Bank and NatWest.

    An interim facilities agreement relating to the financing was dated on the day the revised offer was announced.

    Harworth shares traded as high as 193.2 pence during the session before trading at 186.2 pence, compared with the 187 pence offer price. The company’s 52-week high stands at 195 pence.

    UK Mid-Cap Market Falls

    The share-price increase came after a lower session for the broader UK market.

    The FTSE 100 closed the previous session 0.2% lower at 10,679.99, while the FTSE 250 declined 0.9%.

    Harworth specialises in the regeneration and development of land, with activities concentrated in the North of England and the Midlands.

  • Avacta Presents AVA6103 Preclinical Data and FOCUS-01 Trial Design at AACR Conference

    Avacta Presents AVA6103 Preclinical Data and FOCUS-01 Trial Design at AACR Conference

    Avacta (LSE:AVCT) has presented the design of its FOCUS-01 Phase 1 clinical trial alongside new preclinical data for AVA6103 at the AACR Conference on Pancreatic Cancer.

    AVA6103 is a FAP-enabled pre|CISION peptide-drug conjugate designed to deliver exatecan, a topoisomerase I inhibitor, within the tumour microenvironment.

    The company is evaluating the drug in FAP-positive solid tumours, including pancreatic ductal adenocarcinoma, or PDAC.

    Preclinical Studies Evaluate Two-Week Dosing

    Preclinical studies using PDAC patient-derived xenograft models evaluated AVA6103 under a dose-dense regimen administered every two weeks.

    Avacta reported tumour-targeted delivery of exatecan and complete and partial responses in the models, with responses persisting for several weeks after treatment ended.

    Researchers also observed high FAP expression in the PDAC models and reported that FAP-positive fibroblasts were located close to blood vessels and tumour cells.

    Avacta said these findings are consistent with the intended mechanism of its pre|CISION technology, which is designed to release its drug payload in FAP-rich tumour environments.

    FOCUS-01 Trial Continues Dose Escalation

    Avacta also presented early safety and pharmacokinetic findings from the first three dose levels of the Phase 1 FOCUS-01 trial.

    According to the company, the results demonstrated proof of mechanism and AVA6103 was well tolerated at payload doses approximately 50% above the maximum tolerated dose of conventional exatecan.

    Avacta said the pharmacokinetic profile observed to date was consistent with its preclinical modelling.

    These findings are from an early-stage Phase 1 study, and further clinical data will be required to assess the safety and efficacy of AVA6103 in patients.

    Enrolment Continues in Both Trial Arms

    Patient enrolment is continuing across both arms of FOCUS-01, including a dose-intense every-two-week regimen for patients with PDAC.

    Avacta said current dosing in this arm has reached a payload level exceeding twice the conventional maximum tolerated dose of exatecan and is approaching the payload exposure of Enhertu in breast cancer.

    The trial is continuing to evaluate AVA6103 across increasing dose levels and dosing schedules.

    About Avacta

    Avacta Group plc, trading as Avacta Therapeutics, is a clinical-stage life sciences company developing targeted oncology treatments.

    Its pre|CISION platform uses fibroblast activation protein to enable the release of drug payloads within the tumour microenvironment.

    AVA6103 is an exatecan-based pre|CISION peptide-drug conjugate being developed for FAP-positive solid tumours, including pancreatic, cervical, breast, small cell lung, gastric and colorectal cancers.

  • Bango H1 Revenue Rises 3% as Annual Recurring Revenue Reaches $20.4 Million

    Bango H1 Revenue Rises 3% as Annual Recurring Revenue Reaches $20.4 Million

    Bango (LSE:BGO) reported revenue of $25.9 million for the six months ended 30 June 2026, an increase of 3% from the corresponding period a year earlier.

    Subscriptions revenue increased 13% to $12.3 million, while Payments revenue declined 5% to $13.6 million. Bango said the reduction in Payments revenue reflected its planned restructuring and exit from lower-margin payment routes.

    Group gross margin increased to 87%, reflecting a greater contribution from subscription revenue.

    Annual Recurring Revenue Increases 31%

    Annual Recurring Revenue reached $20.4 million at the end of the period, up 31% year-on-year. Bango said recurring revenue represented 39% of group revenue on a trailing 12-month basis.

    Net Revenue Retention was 119%, while the number of active subscriptions increased 33% to 25.6 million.

    The company added six new Digital Vending Machine® customers during the first half.

    Adjusted EBITDA Rises to $9.0 Million

    Group Adjusted EBITDA increased 34% to $9.0 million.

    Cash EBITDA was $3.7 million, compared with a $0.7 million loss in the first half of 2025. The company said first-half Cash EBITDA was also higher than the amount generated during the whole of the 2025 financial year.

    Within the Payments business, Adjusted EBITDA margin increased to 43% following the removal of non-core, lower-margin payment routes.

    Payments Restructuring Expected to Finish in 2026

    Bango said the restructuring of its non-core Payments activities is progressing ahead of its original plan and is expected to be completed during 2026.

    The company expects the remaining changes to have a low-single-digit impact on reported revenue and a negligible effect on Adjusted EBITDA.

    Bango said subscription activity has continued into the second half, supported by expansion among existing customers and its pipeline of potential new business.

    The board said trading remains in line with full-year market expectations.

    About Bango

    Bango PLC is a Cambridge-based technology company providing subscription bundling and digital payment services.

    Its Digital Vending Machine® platform enables telecom operators, financial services companies and other distribution channels to offer subscription services to customers.

    The group operates through Subscriptions and Payments activities, with the latter including carrier billing and digital wallet services.

  • Capita Secures £30 Million Financing From Shawbrook Bank

    Capita Secures £30 Million Financing From Shawbrook Bank

    Capita plc (LSE:CPI) has secured £30 million of new financing facilities from Shawbrook Bank Limited for general corporate purposes and the refinancing of existing debt.

    The financing comprises a £15 million revolving credit facility and a £15 million term loan. Both facilities have a three-year maturity, running to September 2029.

    New Facilities Include £15 Million RCF and Term Loan

    Capita said the new £15 million revolving credit facility largely mirrors the terms and interest rate of its existing £325 million revolving credit facility.

    The separate £15 million term loan carries an interest rate that is modestly higher than the rate applying to the existing revolving facility.

    The company said the additional financing will be used for general corporate purposes and to refinance existing debt.

    About Capita

    Capita plc is a business services company providing services to public and private-sector organisations, including central and local government and regulated industries.

    The company combines technology, data, artificial intelligence and operational services in the delivery of services for its clients.