Blog

  • Carrefour Shares Fall Over 11% as Retailer Lowers 2026 Financial Guidance

    Carrefour Shares Fall Over 11% as Retailer Lowers 2026 Financial Guidance

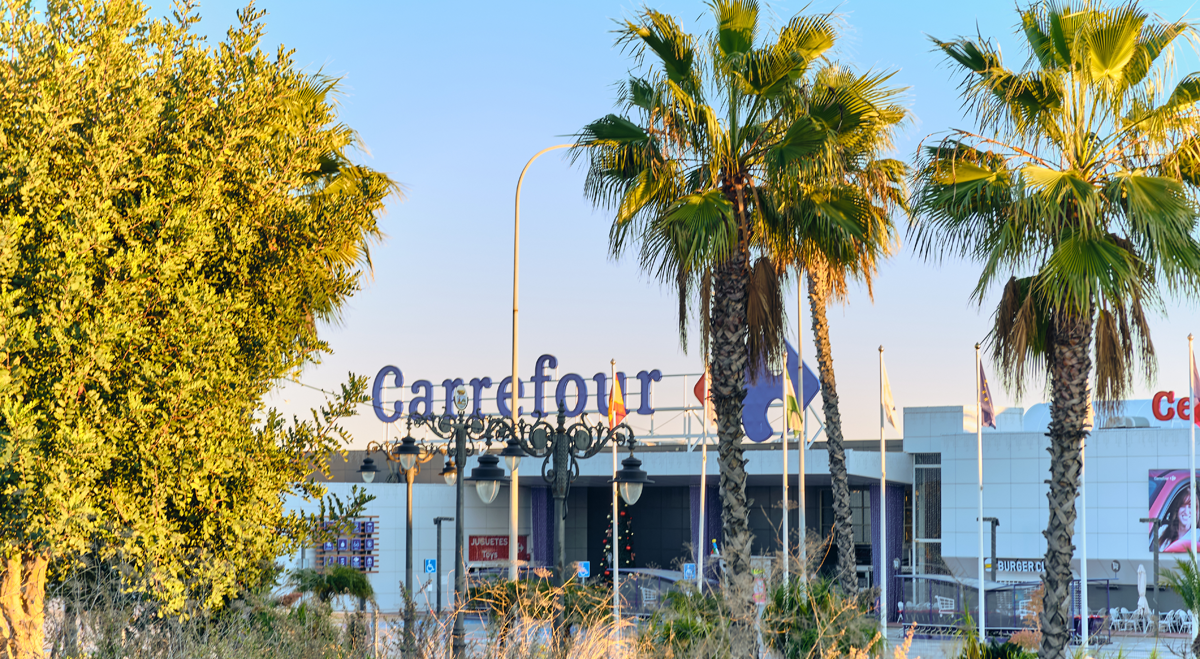
    Carrefour (EU:CA) shares declined more than 11% on Wednesday after the French retail group reduced its full-year financial forecasts, citing deteriorating social and security conditions in France that have affected store operations and consumer spending.

    The company reported third-quarter like-for-like sales growth of 2.3%, compared with an increase of 2.1% during the first half of 2026.

    Despite the quarterly sales increase, Carrefour revised its expectations for operating profitability, earnings per share and cash generation for the full year.

    The retailer now forecasts growth in its recurring operating income margin of between zero and 15 basis points, compared with its previous target of 25 basis points.

    Carrefour also reduced its adjusted earnings per share guidance, now expecting broadly stable earnings or slight growth rather than the high single-digit increase previously anticipated.

    The company revised its net free cash flow outlook from slight growth to a slight decline for 2026.

    Management attributed the changes to recent developments in France, which have disrupted operations at a number of urban stores and created uncertainty surrounding consumer spending.

    In its domestic market, Carrefour recorded third-quarter like-for-like sales growth of 1.2%, with increases across its different store formats.

    The company said pricing investments made earlier in the year contributed to the French sales performance.

    In Spain, like-for-like sales rose 2.1%, supported by higher sales volumes.

    Brazil reported like-for-like growth of 1.4%, with the Atacadão retail format contributing to the increase.

    Alexandre Bompard, Chairman and Chief Executive Officer of Carrefour, commented on the group’s quarterly trading performance and the situation affecting its French operations.

    “Carrefour recorded +2.3% like-for-like sales growth in the third quarter, in line with the first half of the year, driven by food sales and the positive contribution from our core markets,” Bompard said.

    “The events that have taken place in France over the last few days have affected a significant number of our stores in urban areas and have placed our teams and partners in particularly difficult situations.”

    The company indicated that recent events had affected a significant number of stores in French urban areas, complicating the operating environment ahead of the year-end retail period.

    Carrefour also reported an 18% increase in e-commerce sales during the third quarter, reflecting growth in its online retail activities.

    The group continued expanding its convenience store network, opening 89 new locations across France and Spain during the period.

    The quarterly results therefore showed increased like-for-like sales across Carrefour’s principal markets, alongside growth in online sales and further store openings.

    However, the retailer’s revised financial guidance reflects its assessment of the potential effects of current operating conditions in France on profitability and cash flow during the remainder of 2026.

    The reduction in its full-year targets coincided with a decline of more than 11% in Carrefour’s share price during Wednesday’s trading session.
  • EssilorLuxottica Shares Rise Over 11% as Q3 Revenue Reaches €7.49 Billion

    EssilorLuxottica Shares Rise Over 11% as Q3 Revenue Reaches €7.49 Billion

    EssilorLuxottica (EU:EL) shares rose more than 11% in early trading in Paris on Wednesday after the eyewear group reported third-quarter revenue above analysts’ expectations, supported by growth in its Direct-to-Consumer business and wearable technology products.

    The company reported quarterly revenue of €7.49 billion, an increase of 9% compared with the previous year and above the market consensus estimate of €7.35 billion.

    At constant exchange rates, revenue increased 7.2%, following double-digit growth in the corresponding quarter of the previous year.

    The Direct-to-Consumer division generated revenue of €4.09 billion, representing growth of 10.6% at constant exchange rates. Comparable-store sales increased 6.8% during the quarter.

    Professional Solutions recorded revenue of €3.39 billion, an increase of 3.4%, compared with double-digit growth in the same period last year.

    All geographic regions contributed to the group’s revenue growth.

    Asia-Pacific recorded the largest increase, with revenue rising 15.7% at constant exchange rates. Revenue in Europe, the Middle East and Africa (EMEA) grew 7.5%, while Latin America reported growth of 7.1%.

    North American revenue increased 4.7% at constant exchange rates.

    Across its product categories, EssilorLuxottica reported growth of 6.5% in its traditional Eyecare and Medtech business.

    Wearables revenue, which includes artificial intelligence-enabled glasses and Nuance Audio products, increased 20% to €486 million.

    The company’s myopia management portfolio also recorded growth, with revenue increasing 24% during the period.

    Chairman and Chief Executive Officer Francesco Milleri and Deputy Chief Executive Officer Paul du Saillant commented on the group’s performance and the development of its product portfolio.

    “Quarter after quarter, our Company continues to demonstrate the strength of its unique model,” the executives said.

    They also highlighted upcoming product launches and the expansion of the group’s wearable technology range ahead of the holiday shopping period.

    “As we head into the holiday season, new AI glasses launches and the rollout of Nuance Audio Plus are further strengthening our wearable portfolio, offering people new ways to engage with and navigate the world around them,” they said.

    For the first nine months of 2026, EssilorLuxottica reported revenue of €22.3 billion, an increase of 6.8% on a reported basis and 8.9% at constant exchange rates.

    Analysts currently expect the company to generate full-year revenue of €30.08 billion.

    Looking beyond the current financial year, EssilorLuxottica outlined its objectives for the next five years, targeting continued revenue growth at constant exchange rates.

    The company also intends to deliver growth in adjusted operating profit broadly aligned with its revenue performance over that period.

    The third-quarter results reflected increased sales across the group’s geographic markets and business divisions, with wearable technology and direct-to-consumer activities contributing to overall revenue growth.

  • Market Open: Domino’s Sales Rise, Halfords Growth Continues

    Market Open: Domino’s Sales Rise, Halfords Growth Continues

    FTSE 100 slips as UK inflation rises. Domino’s and Halfords report sales growth, while Brent crude advances amid Middle East supply concerns.

    Market Overview

    The FTSE 100 opened 0.19 per cent lower at 10,712.80, as UK inflation accelerated to 3.5 per cent, weighing on expectations for interest rate reductions. European markets were mixed, with the Euronext 100 rising 0.39 per cent to 1,860.22, while Germany’s DAX declined 0.16 per cent to 25,263.04. On Wall Street, the Nasdaq closed marginally lower at 26,424.82, while the S&P 500 advanced to 7,712.57, as investors assessed corporate earnings ahead of major technology company results.

    Commodity markets showed mixed movements, with copper and gold declining while Brent crude advanced amid concerns over Middle Eastern energy supplies. Natural gas also moved lower. Bitcoin rose against sterling. The pound strengthened against the US dollar and euro but weakened against the Swiss franc, Japanese yen and Australian dollar. Inflation developments and energy prices remained important considerations for monetary policy expectations.


    Market Numbers

    FTSE 100: Down (-0.19%), 10,712.80
    Euronext 100: Up (+0.39%), 1,860.22
    DAX: Down (-0.16%), 25,263.04
    NASDAQ: Down, 26,424.82
    S&P 500: Up, 7,712.57


    In the Headlines

    Quarterly System Sales Rise – Domino’s Pizza Group (LSE:DOM)
    Domino’s Pizza Group reported a 3.5 per cent increase in third-quarter system sales and maintained its FY2026 outlook. The update provides investors with an indication of trading performance across its franchise network and management’s expectations for the remainder of the financial year.

    First-Half Like-for-Like Sales Increase – Halfords Group (LSE:HFD)
    Halfords reported a 7.1 per cent increase in first-half like-for-like sales and reaffirmed its FY2027 profit guidance. The results highlight trading across the motoring and cycling retailer’s operations while leaving its full-year earnings expectations unchanged.


    Currencies (vs GBP)

    USD: Up (+0.02%), $1.3376
    CHF: Down (-0.07%), Fr.1.1034
    EUR: Up (+0.05%), €1.1918
    JPY: Down (-0.10%), ¥211.47
    AUD: Down (-0.17%), $1.9056
    Bitcoin (BTC/GBP): Up, £62,035.80


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Up
    Natural Gas: Down

  • FTSE 100 Declines as UK Inflation Rises to 3.5% in September

    FTSE 100 Declines as UK Inflation Rises to 3.5% in September

    The FTSE 100 traded lower on Wednesday after UK inflation accelerated more than expected in September, adding to uncertainty over the Bank of England’s interest rate outlook. Oil prices also advanced amid continuing tensions in the Middle East and concerns about energy supplies.

    The FTSE 100 declined 0.24% as of 07:18 GMT, while European equity markets showed mixed movements. Germany’s DAX fell 0.16%, while France’s CAC 40 gained 0.10%.

    Sterling weakened 0.02% against the US dollar to $1.3379.

    Figures released by the Office for National Statistics showed that UK consumer price inflation increased to 3.5% in September, compared with 3.1% in August.

    The annual reading exceeded economists’ expectations of 3.4% and represented the highest inflation rate since October 2025.

    On a monthly basis, consumer prices rose 0.4%, compared with forecasts for a 0.3% increase.

    Core inflation, which excludes certain volatile components, was in line with expectations at 2.8%.

    Fuel prices contributed to the inflation backdrop, with petrol averaging 169.5 pence per litre, its highest level since August 2022.

    The figures were released ahead of the UK Government’s Budget, scheduled for 28 October, and added to market discussions about the potential direction of monetary policy.

    Higher inflation has raised questions about whether the Bank of England may need to increase interest rates to contain price pressures.

    Geopolitical developments also remained a focus for financial markets, particularly diplomatic efforts involving the United States and Iran and the implications for international shipping routes.

    US Secretary of State Marco Rubio said several countries were participating in diplomatic discussions concerning Iran, with mediation efforts continuing.

    Rubio indicated that any agreement would ultimately require a decision by President Donald Trump. He also described reaching an agreement as extremely difficult and said economic pressure would continue until Iran stopped targeting shipping in the Strait of Hormuz.

    Iranian Foreign Minister Abbas Araghchi said the strait would remain closed until Washington accepted Tehran’s conditions. Indirect negotiations were continuing through Pakistan and Qatar.

    Trump separately indicated that he expected the conflict to conclude quickly and suggested that oil prices would decline substantially following its resolution.

    In the UK, Prime Minister Andy Burnham told parliament that a suspected plot involving RAF Fairford was almost certainly directed by Iran’s Revolutionary Guard. Police had re-arrested two men in connection with the matter.

    Energy markets reflected continuing uncertainty surrounding regional shipping routes and potential disruptions to oil infrastructure.

    Brent crude futures increased 1.12% to $110.01 per barrel, with traders monitoring risks to Red Sea shipping and reported threats involving Saudi Arabian oil facilities.

    US crude futures also advanced, rising 1.04% to $98.84 per barrel.

    Precious metals moved in the opposite direction, with gold futures declining 0.24% to $4,132.55 an ounce.

    Spot gold fell 0.25% to $4,115.23 an ounce.

    The combination of higher UK inflation, uncertainty over interest rates and developments in the Middle East provided the backdrop for Wednesday’s trading session, as investors assessed economic data alongside geopolitical risks.

  • Ashtead Technology Shares Rise 14.8% Following £505 Million Takeover Agreement

    Ashtead Technology Shares Rise 14.8% Following £505 Million Takeover Agreement

    Ashtead Technology Holdings PLC (LSE:AT.) shares rose 14.8% after the company announced an agreement to be acquired by Pine Acquisition UK Bidco Limited in an all-cash transaction valuing the business at approximately £505 million on a fully diluted basis.

    Under the terms of the proposed acquisition, Ashtead Technology shareholders will receive 615 pence in cash for each share held.

    The offer represents a premium of 80.9% to the company’s closing share price of 340 pence on 22 September 2026, the last business day before the commencement of the offer period.

    Pine Acquisition UK Bidco Limited is controlled by funds managed by Ember Infrastructure Management.

    The transaction is expected to be implemented through a court-sanctioned scheme of arrangement under Part 26 of the Companies Act 2006, subject to shareholder approval and the satisfaction of other required conditions.

    Ashtead Technology’s board of directors has unanimously recommended that shareholders vote in favour of the proposed acquisition.

    Bill Shannon, Chairman of Ashtead Technology, said the board considers the offer an opportunity for shareholders to realise value relative to the risk-adjusted returns that could be achieved through the company’s existing standalone business strategy.

    The recommendation reflects the board’s assessment of the acquisition terms and the alternative of continuing to operate as an independent listed company.

    Bidco has received irrevocable undertakings from Ashtead Technology directors holding a combined 1,822,898 shares, representing approximately 2.3% of the company’s issued share capital as of Sunday.

    These undertakings relate to the directors’ commitment to support the proposed transaction through the required shareholder approval process.

    Completion of the acquisition remains conditional on several approvals.

    At the court meeting, the scheme must receive approval from a majority in number of shareholders voting, representing at least 75% in value of the shares voted.

    Shareholders must also approve the relevant resolutions at a separate general meeting, while the scheme requires sanction by the court before it can become effective.

    The proposed transaction would result in Ashtead Technology being acquired for cash at the agreed price of 615 pence per share, provided all applicable conditions are satisfied.

    The company’s shares increased 14.8% following the announcement, reflecting the market movement reported after publication of the agreed takeover terms.

  • Quilter Reports 30% Rise in Q3 Core Net Inflows to £2.9 Billion as Assets Reach £160.5 Billion

    Quilter Reports 30% Rise in Q3 Core Net Inflows to £2.9 Billion as Assets Reach £160.5 Billion

    Quilter (LSE:QLT) reported a 30% increase in core net inflows to £2.891 billion for the third quarter of 2026, compared with £2.227 billion in the corresponding period last year, supported by increased investment flows across its wealth management platform.

    The UK wealth manager’s assets under management and administration (AuMA) reached £160.5 billion at the end of September, representing a 19% increase from £134.8 billion a year earlier.

    Reported net inflows, which include non-core activities, rose to £2.737 billion during the quarter, compared with £2.118 billion in the third quarter of 2025.

    Gross inflows increased 22% year on year, reaching £6.01 billion from £4.944 billion in the prior-year period.

    For the first nine months of 2026, Quilter recorded core net inflows of £8.850 billion, an increase of 31% compared with £6.733 billion during the same period in 2025.

    Reported net inflows for the nine-month period totalled £8.535 billion, up from £6.441 billion a year earlier.

    The company’s investment platform accounted for a substantial proportion of the inflows, generating £8.0 billion in net new assets during the first nine months of the year.

    Third-quarter platform net inflows increased 25% year on year to £2.6 billion, reflecting higher contributions from both Quilter-affiliated financial advisers and independent advisers.

    Inflows generated through Quilter advisers rose 10% compared with the previous year, while those from independent financial advisers increased 33%.

    The High Net Worth business also reported increased client investment activity, with quarterly net inflows rising 35% year on year to £322 million.

    Gross inflows within the High Net Worth division reached £873 million during the quarter.

    Quilter also reported an increase in adviser productivity, with annualised gross sales per adviser rising 9% compared with the third quarter of 2025.

    Gross sales per adviser reached £3.7 million on an annualised basis, compared with £3.4 million in the prior-year period.

    Chief Executive Steven Levin said gross outflow rates remained stable during the quarter and were consistent with levels recorded in the first half of the year.

    The company provides investment management, financial advice and wealth management platform services to retail investors, financial advisers and high-net-worth clients.

    Its operations include adviser-led investment services and a platform used by independent financial advisers to manage client portfolios and investment products.

    The third-quarter figures show increased net inflows across Quilter’s principal distribution channels, alongside growth in total assets under management and administration.

    At the end of September, Quilter’s AuMA stood at £160.5 billion, while cumulative core net inflows for the first nine months of 2026 reached £8.850 billion.

  • 3i Group Shares Fall Over 4% as Carrefour Cuts 2026 Financial Guidance

    3i Group Shares Fall Over 4% as Carrefour Cuts 2026 Financial Guidance

    3i Group (LSE:III) shares declined more than 4% on Wednesday, coinciding with a fall of over 13% in Carrefour (EU:CA) shares after the French retailer reduced its full-year financial forecasts.

    Carrefour revised its 2026 outlook, citing deteriorating social and security conditions in France that have disrupted store operations and affected consumer spending.

    The retailer now expects growth in its recurring operating income margin of between zero and 15 basis points, compared with its previous forecast of 25 basis points.

    Carrefour also lowered its adjusted earnings per share guidance, now anticipating broadly stable earnings or slight growth rather than the high single-digit increase previously forecast.

    The company revised its net free cash flow outlook, projecting a slight decline for the full year compared with its earlier expectation of modest growth.

    The changes to Carrefour’s financial guidance were accompanied by third-quarter trading figures showing a 2.3% increase in like-for-like sales, compared with growth of 2.1% during the first half of 2026.

    In France, like-for-like sales increased 1.2% during the third quarter, with growth recorded across the retailer’s store formats.

    Carrefour attributed part of the French sales performance to pricing investments undertaken earlier in the year.

    Despite the increase in quarterly sales, the company indicated that recent developments in France had affected its operating environment and prompted the revisions to its financial expectations.

    Alexandre Bompard, Chairman and CEO of Carrefour, commented:

    “The events that have taken place in France over the last few days have affected a significant number of our stores in urban areas and have placed our teams and partners in particularly difficult situations,”

    The decline in Carrefour shares coincided with selling pressure on 3i Group, whose shares fell more than 4% during Wednesday’s session.

    The source attributed the movement in 3i’s share price to a market read-across from Carrefour’s revised outlook, although it did not provide details establishing a direct financial impact on 3i.

    Carrefour’s updated guidance reflects its assessment of the operating conditions affecting its French business, while its third-quarter results showed continued like-for-like sales growth.

    The retailer’s revised expectations for operating margins, earnings per share and free cash flow represent reductions across its principal full-year financial targets.

  • Hardide Expects FY2026 Revenue of £13.5 Million and EBITDA of £5.8 Million as Coating Capacity Expansion Progresses

    Hardide Expects FY2026 Revenue of £13.5 Million and EBITDA of £5.8 Million as Coating Capacity Expansion Progresses

    Hardide plc (LSE:HDD) has reported that revenue more than doubled to £13.5 million for the financial year ended 30 September 2026, with EBITDA expected to reach £5.8 million, exceeding both the previous year’s performance and market forecasts.

    The UK-based industrial coatings specialist attributed the increase in revenue and profitability to higher customer demand, cost management measures and operational improvements implemented across the business.

    Trading during the fourth quarter contributed to the full-year performance, supported by orders from customers in North America and new production contracts across the aerospace, energy and industrial sectors.

    Hardide confirmed that it had completed initial shipments to a major North American customer, resulting in a further order valued at US$1.9 million.

    The company also reported additional production contracts in its existing markets, alongside ongoing product testing with prospective customers in the Middle Eastern energy sector and the semiconductor industry.

    These testing programmes form part of Hardide’s efforts to expand the commercial applications of its tungsten-based surface coating technology.

    At the financial year-end, Hardide reported gross cash of £3.2 million, following investment in working capital and manufacturing equipment.

    The company invested £1.5 million in working capital to support increased production activity and secure supplies of process gases at agreed costs for most of FY2027.

    Hardide also paid a £0.7 million deposit towards the purchase of additional coating reactors as part of a programme to increase manufacturing capacity.

    The new equipment is expected to become operational during the second half of FY2027 and is intended to approximately double the company’s production capacity.

    Management estimates that the expanded facilities will have the capacity to support annual sales of approximately £40 million once the additional reactors are operational.

    The planned increase in capacity is intended to accommodate anticipated demand from existing customers and potential new contracts across Hardide’s principal industrial markets.

    Hardide specialises in tungsten carbide and tungsten metal matrix coatings designed to improve the durability of engineering components exposed to abrasion, erosion and corrosion.

    Its coating technology is used in applications including energy equipment, industrial pumps and valves, gas turbines, aerospace components and precision engineering.

    The company also supplies coatings for components with complex geometries and internal surfaces, where conventional surface treatments may be difficult to apply.

    Looking ahead, management expects revenue growth to continue during FY2027, supported by its existing order pipeline, customer development programmes and planned manufacturing expansion.

    Hardide has also outlined a longer-term objective of more than doubling revenue again over the next two to three years.

    Achievement of this target will depend on customer demand, the conversion of commercial opportunities into orders and the successful commissioning of the additional coating capacity.

    The company enters FY2027 with expected annual EBITDA of £5.8 million, gross cash of £3.2 million and an investment programme aimed at expanding its manufacturing operations.

  • Duke Capital Reports £7.0 Million Quarterly Cash Revenue and Maintains 1.4p Interim Dividend

    Duke Capital Reports £7.0 Million Quarterly Cash Revenue and Maintains 1.4p Interim Dividend

    Duke Capital (LSE:DUKE) has reported total cash revenue of £7.0 million for the quarter ended 30 September 2026, unchanged from the previous quarter, as the investment company continues restructuring activities across parts of its portfolio.

    The Guernsey-based provider of hybrid capital financing issued the trading update in response to recent volatility in its share price, providing information on cash generation, portfolio developments and its outlook for the remainder of the financial year.

    Duke confirmed that its interim dividend of 1.4p per share remains covered by free cash flow, with the company continuing to generate income from investments across multiple sectors and geographic markets.

    The group reported progress in reorganising certain portfolio businesses, including the exit of loss-making divisions within two of its investments.

    Management said these changes form part of efforts to improve the operating performance of its capital partners and address areas of the portfolio experiencing financial or operational challenges.

    Duke also highlighted conditions in the UK market, which it expects to affect recurring cash revenue during the second half of the financial year.

    The company anticipates a reduction in recurring revenue in H2 as its investment team concentrates on improving the performance of UK portfolio businesses, with the objective of achieving progress during the following financial year.

    Separately, Duke reported that two of its capital partners are currently involved in late-stage exit processes.

    Management indicated that successful completion of these transactions could result in FY2027 total cash revenue materially exceeding existing market expectations.

    The potential financial contribution remains conditional on the exits being completed, and the company has not provided revised revenue guidance or disclosed the expected proceeds from either transaction.

    Duke’s directors also commented on the company’s market valuation, stating their belief that the current share price represents a significant discount to its net asset value.

    This assessment reflects the board’s view and was provided in the context of recent share price movements.

    Duke operates a hybrid capital investment model, providing long-term financing to small and medium-sized businesses in Europe and North America.

    Its financing arrangements combine characteristics of debt and equity, with returns generated through recurring cash payments and potential additional proceeds when investments are realised.

    The company maintains a portfolio diversified across industries and geographic regions, with investment management activities focused on cash generation, capital preservation and portfolio company performance.

    Looking ahead, Duke expects to provide further updates on its portfolio reorganisations and the potential exits currently under discussion.

    The group is scheduled to publish its interim financial statements on 3 December 2026, when additional information on its financial position and portfolio performance is expected to become available.

  • Fresnillo Reports 11.6% Decline in Q3 Silver Production and Maintains 2026 Guidance

    Fresnillo Reports 11.6% Decline in Q3 Silver Production and Maintains 2026 Guidance

    Fresnillo plc (LSE:FRES) has reported lower silver and gold production for the third quarter of 2026, reflecting reduced ore grades and processing volumes at several operations, while maintaining its full-year production guidance across all metals.

    The Mexico-focused precious metals producer recorded attributable silver production of 10.3 million ounces during the quarter, representing an 11.6% decline compared with the corresponding period in 2025.

    Attributable gold production decreased 10.7% year on year to 135,100 ounces. Both silver and gold output also declined compared with the second quarter of 2026.

    Fresnillo attributed the reduction in production to lower ore grades at certain mining operations, reduced volumes of ore processed and the cessation of contributions from its Silverstream arrangement.

    The company also reported quarter-on-quarter declines in lead and zinc production, which are recovered as by-products of its silver and gold mining activities.

    Despite the lower quarterly output, management said production remained broadly consistent with its expectations for the period.

    Fresnillo reaffirmed its full-year 2026 production guidance, including attributable silver output of between 42.0 million and 46.5 million ounces and gold production of between 500,000 and 550,000 ounces.

    The company also maintained its existing production outlook for 2027 and 2028, with no revisions announced following the third-quarter operating update.

    Fresnillo operates several mining assets in Mexico, including Fresnillo, Herradura, Saucito, Juanicipio, San Julián and Ciénega.

    Its operations include underground silver and gold mines, alongside associated processing facilities producing lead and zinc as secondary metals.

    Management said the company’s operational priorities remain focused on maintaining production efficiency, managing costs and implementing safety measures across its mining portfolio.

    The group continues to address variations in ore grades and processing volumes at its underground operations as part of its ongoing mine planning and production activities.

    Looking ahead to the final quarter of 2026, Fresnillo will continue operating within its existing production plans as it works towards its annual output targets.

    The company has maintained its full-year guidance of 42.0 million to 46.5 million ounces of silver and 500,000 to 550,000 ounces of gold, despite the year-on-year decline in third-quarter production.