Category: Top Story

  • European Stocks Fall as Bond Yields and Oil Prices Rise on Inflation Concerns: DAX, CAC, FTSE100

    European Stocks Fall as Bond Yields and Oil Prices Rise on Inflation Concerns: DAX, CAC, FTSE100

    European stock markets moved lower on Thursday as rising government bond yields and a sharp increase in crude oil prices renewed concerns about inflation and the outlook for interest rates.

    Brent crude futures climbed above $104 a barrel following reports that the White House had requested military strike options against Iran from the Pentagon, potentially for implementation before the US midterm elections.

    The reports intensified concerns about a possible escalation in tensions between Washington and Tehran, raising fears of disruptions to energy supplies.

    Meanwhile, US Treasury yields approached multi-decade highs after minutes from the Federal Reserve’s September monetary policy meeting indicated unanimous support for another interest rate increase before the end of 2026.

    The yield on the benchmark 10-year Treasury note approached 5.32%, while the 30-year yield traded near 5.71%.

    The combination of higher borrowing costs and rising energy prices weighed on investor sentiment across European equity markets.

    German Exports Decline as European Markets Retreat

    European shares also came under pressure following weaker-than-expected German trade figures.

    Data released by Germany’s Federal Statistical Office, Destatis, showed that exports unexpectedly fell by 0.8% in August compared with the previous month, following a 0.5% decline in July.

    Imports increased by 0.9% during August, reversing a 5.5% contraction recorded in July.

    The figures added to concerns about the outlook for Europe’s largest economy amid elevated financing costs and uncertainty surrounding global trade.

    Germany’s DAX Index declined 0.9%, while France’s CAC 40 fell 0.4%. In London, the FTSE 100 slipped 0.1%.

    Banking stocks were among the weaker performers as eurozone government bond yields climbed towards their recent highs.

    Shares in Commerzbank, BNP Paribas and Lloyds Bank declined as investors assessed the implications of higher yields and persistent inflationary pressures.

    Argenx, Bayer and Vodafone Decline

    Among individual companies, Argenx (NASDAQ:ARGX) recorded a sharp fall after announcing the discontinuation of its Phase 3 UNITY clinical trial.

    The Belgian-Dutch immunology specialist said it had stopped the study evaluating efgartigimod SC in adults with moderate-to-severe Sjögren’s disease.

    The announcement weighed heavily on the company’s shares as investors considered the implications for its clinical development programme.

    Bayer (TG:BAYN) also traded lower despite announcing that the US Food and Drug Administration had accepted its supplemental New Drug Application for KERENDIA.

    The German pharmaceutical and biotechnology group’s shares declined amid broader market weakness.

    Vodafone (LSE:VOD) also moved lower after increasing its cost-saving target for its merged UK telecommunications business.

    Energy Shares Advance as Brent Crude Climbs Nearly 4%

    Energy companies were among the stronger performers as crude oil prices rose sharply.

    BP (LSE:BP.), Shell (LSE:SHEL) and TotalEnergies (EU:TTE) advanced as Brent crude gained nearly 4%, supported by concerns about a potential escalation of the conflict involving the United States and Iran.

    The rise in oil prices followed reports that US officials were considering possible military options against Iran.

    Investors assessed the potential consequences for global crude supplies, particularly given the importance of Middle Eastern energy production and transportation routes.

    The increase in oil prices provided support for major European energy producers, even as it contributed to wider concerns about inflation and interest rates.

    Tesco and Imperial Brands Gain on Corporate Updates

    Several UK-listed companies advanced following announcements concerning their financial outlooks and capital allocation plans.

    Tesco (LSE:TSCO) rose after the supermarket group issued a slightly improved profit forecast and increased the size of its share buyback programme.

    The announcement provided support for the retailer’s shares despite the broader decline in European equities.

    Imperial Brands (LSE:IMB) also gained after reaffirming its full-year financial guidance and announcing plans to repurchase £1.5 billion of its shares during fiscal 2027.

    Elsewhere, Edinburgh-based investment company Aberdeen (LSE:ABDN) advanced after announcing plans to reduce its holding in insurer Standard Life (LSE:SDLF).

    Aberdeen intends to lower its stake from 10.3% to 5.2%, while Standard Life shares declined following the announcement.

    Danish biotechnology company Bavarian Nordic (TG:BV3) also recorded strong gains after raising its full-year financial guidance.

    Overall, European markets remained under pressure from rising bond yields, higher oil prices and weaker economic indicators, although company-specific developments supported selected stocks.
  • Wall Street Futures Retreat as AI Borrowing Plans and Global Bond Market Risks Unsettle Investors: Dow Jones, S&P, Nasdaq

    Wall Street Futures Retreat as AI Borrowing Plans and Global Bond Market Risks Unsettle Investors: Dow Jones, S&P, Nasdaq

    US stock index futures moved lower on Thursday as investors weighed growing debt market pressures, higher energy prices and reports that major technology companies are seeking billions of dollars to finance artificial intelligence infrastructure.

    The latest developments came alongside earnings updates from Applied Digital (NASDAQ:APLD) and Samsung Electronics (USOTC:SSNHZ), while minutes from the Federal Reserve’s September meeting provided further indications about the outlook for US interest rates.

    At 02:54 ET (06:54 GMT), Dow Jones futures declined 262 points, or 0.5%. S&P 500 futures fell 23 points, equivalent to 0.3%, while Nasdaq 100 futures lost 154 points, or 0.5%.

    The weaker futures followed declines in the main US equity indices during the previous session, when rising bond yields and concerns about Middle Eastern oil supplies affected market sentiment.

    French Debt Market Turbulence Adds to Global Borrowing Cost Pressures

    Government bond markets remained under pressure as concerns about France’s public finances contributed to increased volatility across European sovereign debt.

    The yield spread between French and German 10-year government bonds was on course for its largest daily widening since the COVID-19 pandemic in 2020 before easing later in the session.

    Deutsche Bank analysts identified France as a major contributor to the latest global bond market sell-off, noting that sovereign yield spreads had widened across several European countries.

    The developments raised concerns about renewed financial market contagion after a period of relative improvement in European debt market conditions.

    In the UK, the benchmark 10-year gilt yield reached its highest level since 2007, while Italian government bond yields also increased.

    Rising oil prices added to the pressure as investors considered the inflationary implications of possible energy supply disruptions in the Middle East.

    US Treasury markets experienced similar volatility. Strong demand at an auction of 10-year government bonds provided some support, although the 30-year Treasury yield climbed to its highest level in more than two decades.

    The US 10-year Treasury yield subsequently stood at 5.327%.

    Higher yields have raised concerns about financing conditions for governments and businesses, while also influencing investor demand for equities and other risk-sensitive assets.

    Broadcom, Oracle and SpaceX Reportedly Pursue Major AI Financing Deals

    Reports of substantial debt financing plans among US technology companies added another source of uncertainty for global bond investors.

    According to The Wall Street Journal, Broadcom (NASDAQ:AVGO) has been working to secure more than $50 billion to support a custom artificial intelligence chip project being developed with OpenAI.

    The newspaper also reported that Oracle (NYSE:ORCL) was discussing financing arrangements with Apollo and Goldman Sachs for a large purchase of computing chips.

    Separately, the Financial Times reported that SpaceX was seeking approximately $40 billion from lenders to fund purchases of Nvidia processors.

    The proposed transactions underline the scale of investment required to expand AI computing capacity, with technology companies committing substantial resources to processors, data centres and supporting infrastructure.

    Analysts at Vital Knowledge suggested that the volume of borrowing associated with AI investment could maintain upward pressure on US Treasury yields.

    An increase in corporate debt supply could also create additional competition for investment capital at a time when government borrowing costs remain elevated.

    Applied Digital Revenue Surges While Equipment Spending Exceeds $2 Billion

    Applied Digital (NASDAQ:APLD) reported first-quarter fiscal revenue of $342 million, representing a 322% increase from the corresponding period a year earlier.

    The result exceeded Wall Street forecasts, reflecting continued demand for data centre infrastructure supporting AI computing.

    Adjusted core earnings reached $64.4 million, also ahead of analysts’ expectations.

    However, the company’s expenditure on property and equipment rose 730% year on year to $2.074 billion.

    That spending substantially exceeded Applied Digital’s reported cash flow of $64 million, highlighting the financial requirements associated with expanding AI data centre operations.

    The difference between revenue growth and infrastructure spending has drawn attention to the financing demands facing companies involved in the artificial intelligence investment cycle.

    Vital Knowledge analysts pointed to Applied Digital’s results as an example of the sector’s combination of rapid commercial expansion and substantial capital expenditure.

    Applied Digital shares advanced in after-hours trading following the announcement.

    Samsung Delivers Record Third-Quarter Earnings Estimate

    Samsung Electronics (USOTC:SSNHZ) forecast record operating profit for the third quarter, supported by strong demand for memory chips used in artificial intelligence applications.

    The company estimated operating profit of approximately 107.40 trillion won, or $80.1 billion, for the three months ended 30 September.

    This compared with 12.2 trillion won during the same period last year, representing an increase of almost tenfold.

    The preliminary figure was slightly below Bloomberg’s consensus estimate of 108.67 trillion won but exceeded LSEG’s forecast of 106.1 trillion won.

    Samsung also projected third-quarter sales of 195 trillion won, more than double the 86.06 trillion won recorded a year earlier.

    The result marked the company’s fourth consecutive quarter of record profits.

    Despite the strong performance, Samsung shares declined during volatile trading, contributing to weakness in South Korea’s KOSPI index.

    Shares in fellow memory chip producer SK Hynix also moved lower.

    Fed Minutes Point to Possible October Hold Before December Rate Increase

    Minutes from the Federal Reserve’s September policy meeting suggested that officials were prepared to wait for further economic evidence before implementing another interest rate increase.

    The central bank raised borrowing costs in September for the first time since 2023, responding to persistent inflationary pressures.

    The meeting record indicated that policymakers intended to assess incoming economic data and consider each policy decision independently.

    Although most officials believed another increase in the federal funds rate would probably be appropriate before the end of the year, the minutes suggested limited urgency to act at the next meeting.

    The Fed could therefore leave interest rates unchanged on 27–28 October while retaining the option of a further increase at its December gathering.

    CME FedWatch data indicated that investors were assigning approximately a 78% probability to unchanged rates in October and a 67% probability to a December increase.

    The outlook for US monetary policy remains closely linked to developments in global debt markets, particularly as rising energy costs and substantial AI-related borrowing plans create additional uncertainty for investors.

  • European Stocks Fall to Four-Month Lows as Bond Market Pressure and Middle East Tensions Weigh on Sentiment: DAX, CAC, FTSE100

    European Stocks Fall to Four-Month Lows as Bond Market Pressure and Middle East Tensions Weigh on Sentiment: DAX, CAC, FTSE100

    European equities declined on Thursday, with the region’s main benchmark reaching its lowest level in almost four months as rising bond yields, concerns about substantial US corporate debt issuance and renewed Middle East energy supply risks weighed on investor sentiment.

    The pan-European Stoxx Europe 600 index fell 1%, reaching its lowest level since 11 June after ending a three-session winning streak on Wednesday.

    Germany’s DAX declined 1%, while France’s CAC 40 lost 0.9%. London’s FTSE 100 fell 0.7%, and Italy’s FTSE MIB recorded a larger decline of 1.3%.

    The losses followed a brief recovery in European equities earlier in the week, with investors continuing to assess developments in global fixed-income markets, monetary policy and government finances.

    US Corporate Bond Issuance Adds to Debt Market Concerns

    Reports that major US technology companies are preparing substantial bond offerings added to uncertainty in international debt markets.

    SpaceX (NASDAQ:SPCX) and Broadcom (NASDAQ:AVGO) were among the companies reportedly considering debt issuance, with the combined potential fundraising estimated at approximately US$80 billion.

    The prospect of additional corporate bond supply raised concerns about competition for institutional investment capital, particularly as government borrowing costs remain elevated.

    Large corporate debt offerings could influence demand for sovereign bonds and affect borrowing conditions across fixed-income markets.

    European technology shares declined amid the broader market weakness, reflecting the sector’s exposure to global technology investment and international supply chains.

    Infineon (TG:IFX) fell 2.7%, while ASML (EU:ASML) declined 2.3%. BE Semiconductor (EU:BESI) and STMicroelectronics (BIT:STMMI) each lost 2.6%.

    Although European equity markets have less direct exposure to some of the largest US technology companies, several European semiconductor and industrial businesses maintain commercial relationships with American technology groups.

    Middle East Conflict Pushes Energy Prices Higher

    Renewed military activity in the Middle East contributed to increases in crude oil prices and European wholesale natural gas futures.

    Reports of drone and missile attacks affecting commercial shipping and energy infrastructure in the Persian Gulf and Red Sea heightened concerns about potential disruptions to energy supplies.

    The increase in energy prices reversed part of their recent declines and added to uncertainty surrounding the cost of fuel and industrial production in Europe.

    Higher energy costs are particularly relevant for energy-intensive manufacturers and other businesses exposed to fluctuations in electricity, natural gas and petroleum prices.

    The developments also raised concerns about inflation at a time when government bond yields have already increased across major economies.

    European businesses face the prospect of higher energy expenditure as seasonal heating demand begins to increase in northwestern Europe.

    Federal Reserve Minutes Reinforce Interest Rate Concerns

    Investor sentiment was also affected by the publication of minutes from the US Federal Reserve’s September monetary policy meeting.

    The minutes indicated that a majority of Federal Open Market Committee policymakers continued to consider another interest rate increase likely before the end of 2026.

    The assessment reduced expectations of an imminent shift towards monetary easing and added to pressure on global bond markets.

    Higher US interest rates can influence borrowing costs internationally and affect valuations across equity and fixed-income markets.

    French Fiscal Concerns Add Pressure to Banks and Equities

    France remained a focus for investors amid concerns about its budget deficit, political uncertainty and the outlook for government borrowing.

    Bank of France Governor Emmanuel Moulin acknowledged on Wednesday that the country’s economic and fiscal position was serious, citing widening budget deficits and political instability.

    However, Moulin rejected suggestions that France required emergency assistance from the European Central Bank, indicating that the country’s fiscal challenges should be addressed through domestic budget measures.

    The CAC 40 remained near its lowest level since March and was heading towards a second consecutive weekly decline as investors assessed the potential consequences of prolonged budget negotiations.

    French banking shares were among the stocks affected by the selling pressure, reflecting concerns about their exposure to domestic government debt.

    Société Générale (EU:GLE) and BNP Paribas (EU:BNP) each declined by more than 2%.

    The broader decline in European equities reflected the combined impact of higher financing costs, uncertainty over monetary policy, renewed energy supply risks and concerns about fiscal conditions in France.

  • Market Open: Tesco Profit Rises, Imperial Brands Buyback

    Market Open: Tesco Profit Rises, Imperial Brands Buyback

    FTSE 100 slips as Tesco reports higher profit and Imperial Brands announces a £1.5bn buyback. Brent crude rises amid Middle East supply concerns.

    Market Overview

    The FTSE 100 opened 0.04 per cent lower at 10,396.56, with mining stocks weighing on UK equities amid renewed concerns over Middle Eastern oil supplies. European markets also weakened, with the Euronext 100 down 1.09 per cent at 1,836.10 and Germany’s DAX falling 0.82 per cent to 24,897.86, as French debt concerns and wider financial market uncertainty affected sentiment. On Wall Street, the Nasdaq closed lower at 27,538.69, while the S&P 500 declined to 7,801.77.

    Commodity markets showed mixed movements, with copper and gold declining while Brent crude and natural gas advanced. Oil supply concerns remained in focus following attacks on shipping in the Middle East, supporting energy prices. Against sterling, the US dollar, Swiss franc and Japanese yen strengthened, while the euro and Australian dollar weakened. Bitcoin also moved lower, reflecting a cautious tone across risk-sensitive assets.


    Market Numbers

    FTSE 100: Down (0.04%), 10,396.56
    Euronext 100: Down (1.09%), 1,836.10
    DAX: Down (0.82%), 24,897.86
    NASDAQ: Down, 27,538.69
    S&P 500: Down, 7,801.77


    In the Headlines

    Profit Growth and Buyback Increase – Tesco (LSE:TSCO)
    Tesco reported a 6.3 per cent increase in first-half adjusted operating profit to £1.78 billion and raised its share buyback target. The performance highlights continued profitability at the UK supermarket group, with increased capital returns providing an additional focus for shareholders.

    Full-Year Outlook Confirmed – Imperial Brands (LSE:IMB)
    Imperial Brands reaffirmed its financial outlook for 2026 and announced a £1.5 billion share buyback programme for 2027. The announcement provides investors with greater visibility over planned shareholder returns as the tobacco group maintains its existing financial expectations.


    Currencies (vs GBP)

    USD: Up (0.06%), $1.3199
    CHF: Up (0.05%), Fr.1.1001
    EUR: Down (0.05%), €1.1793
    JPY: Up (0.03%), ¥208.836
    AUD: Down (0.01%), $1.8986
    Bitcoin (BTC/GBP): Unchanged, £62,986.14


    Commodities

    Copper: Down
    Gold: Down
    Brent Crude: Up
    Natural Gas: Up

  • FTSE 100 Falls as Mining Stocks Decline and Oil Prices Rise on Strait of Hormuz Supply Concerns

    FTSE 100 Falls as Mining Stocks Decline and Oil Prices Rise on Strait of Hormuz Supply Concerns

    UK equities moved lower on Thursday as weakness among mining companies, rising government bond yields and renewed concerns over oil shipments through the Strait of Hormuz weighed on market sentiment.

    The FTSE 100 declined 0.60% by 08:21 BST, while European markets also traded lower. Germany’s DAX fell 0.82%, and France’s CAC 40 lost 0.90%. Sterling weakened 0.15% against the US dollar to $1.3203.

    Mining stocks were among the largest contributors to the decline in London, reflecting weakness across several industrial metals and continued pressure from higher borrowing costs.

    Antofagasta (LSE:ANTO) fell 2.1%, while Anglo American (LSE:AAL), Rio Tinto (LSE:RIO) and Fresnillo (LSE:FRES) recorded losses ranging from 1.4% to 1.8%.

    In commodities trading, silver declined 1.5%, aluminium on the London Metal Exchange fell 0.6%, and nickel slipped 0.63%. Copper prices were broadly unchanged.

    Oil prices, meanwhile, advanced sharply amid concerns about shipping activity and potential supply disruptions in the Strait of Hormuz.

    Brent crude futures rose 3.7% to $103.89 a barrel, while US West Texas Intermediate gained 3.2% to $91.25.

    Gold prices also increased, with futures advancing 0.22% to $4,159 an ounce and spot gold rising 0.37% to $4,126.52.

    Shipping data indicated a reduction in vessel movements through the Strait of Hormuz. According to Kpler, transits declined to a two-month low, with seven vessels recorded on Tuesday and 10 on Wednesday, compared with more than 20 on each of Sunday and Monday.

    Crude oil flows through the waterway were estimated at a minimum of 10.1 million barrels per day, equivalent to approximately 74% of levels recorded before the conflict.

    The UK Maritime Trade Operations organisation reported that a tanker had been struck by projectiles off the coast of Qatar on Wednesday, adding to concerns about maritime security in the region.

    Statements from Iranian and US officials presented differing assessments of the situation.

    Iranian Foreign Minister Abbas Araghchi claimed on social media platform X that US aircraft losses were substantially higher than publicly reported, alleging that 81 aircraft had been downed, compared with 42 cited by the Congressional Research Service in May. He did not provide evidence to substantiate the claim.

    Separately, Ali Mohammadi, deputy political commander of Iran’s Islamic Revolutionary Guard Corps Navy, challenged US statements about conditions in the waterway.

    A White House official told Al Jazeera that the Strait of Hormuz remained open and that substantial volumes of crude oil were being escorted through the passage daily. Those statements differed from the shipping activity figures reported by Kpler.

    US President Donald Trump also commented on the possibility of an agreement with Iran during a campaign rally in San Antonio, Texas, indicating limited interest in pursuing a deal under the circumstances described.

    NBC reported that indirect discussions had taken place in New York, with Washington rejecting an Iranian proposal linking the reopening of the strait to sanctions relief.

    Separately, The Atlantic reported that Trump had requested military strike options ahead of the US midterm elections scheduled for 3 November.

    Government bond markets remained another source of pressure on equities.

    The yield on the benchmark US 10-year Treasury note rose to 5.329%, approaching its 52-week high of 5.366%.

    In the UK, the 30-year gilt yield increased to 6.018%, close to its recent peak of 6.036%.

    Higher bond yields can increase financing costs for businesses and influence equity valuations, particularly when investors reassess the outlook for interest rates and economic growth.

    ING analyst Michiel Tukker linked increased volatility in European interest rate markets to movements in US Treasury yields, particularly after the benchmark yield moved above 5%.

    He indicated that elevated volatility could persist over the coming months.

    UK Corporate News: Tesco, Imperial Brands and Unite Group

    Tesco (LSE:TSCO) raised the lower end of its full-year profit guidance following an increase in first-half operating profit. The supermarket group reported operating profit growth of 6.5% and increased its share buyback target to £950 million.

    Imperial Brands (LSE:IMB) reaffirmed its financial outlook for the year and announced a further £1.5 billion share repurchase programme. The tobacco company said growth in next-generation products helped offset weaker conventional cigarette sales.

    Unite Group (LSE:UTG) reported a 4% quarterly decline in the valuation of its principal student accommodation fund. The company also reiterated plans to dispose of between £300 million and £400 million of assets during the year.

    The combination of falling mining shares, rising oil prices and elevated government bond yields contributed to the weaker performance of UK equities, while investors continued to monitor developments in the Middle East and their implications for energy supplies and financial markets.

  • Greenland Mines Brings Two Major Critical Minerals Opportunities Together

    Greenland Mines Brings Two Major Critical Minerals Opportunities Together

    Greenland Mines Ltd (NASDAQ:GRML), (FSE: HK6) is bringing together two significant critical minerals opportunities in Greenland, combining its established Skaergaard palladium-gold-platinum project with the newly acquired Sarfartoq neodymium-praseodymium rare earths project.

    The combination gives the company exposure to two strategically important areas of the critical minerals market while establishing the foundations of a broader North Atlantic minerals platform.

    The strategy has moved forward significantly during 2026. Greenland Mines has advanced technical work at Skaergaard, completed the acquisition of Sarfartoq and continued to develop plans connecting Greenland’s mineral resources with potential downstream processing and industrial markets in Europe and North America.

    A Major Palladium, Gold and Platinum Opportunity

    At the heart of Greenland Mines’ portfolio is the Skaergaard Project in southeast Greenland, a large-scale mineral system containing palladium, gold and platinum, alongside potential critical-metal by-products.

    The company’s 2026 S-K 1300 Mineral Resource Estimate reported 15.0 million ounces of palladium equivalent in the Indicated category and a further 17.49 million ounces in the Inferred category. The Indicated resource includes approximately 7.57 million ounces of palladium, 3.19 million ounces of gold and 0.60 million ounces of platinum.

    These figures are from the Skaergaard Technical Report Summary prepared by SLR Consulting (Canada) Ltd., with a Mineral Resource Estimate effective July 3, 2026. Palladium-equivalent (PdEq) is a calculated measure based on the report’s metal-price and recovery assumptions; it is not a quantity of contained palladium.

    Importantly, Greenland Mines is continuing to add technical understanding to the resource rather than simply relying on its existing scale.

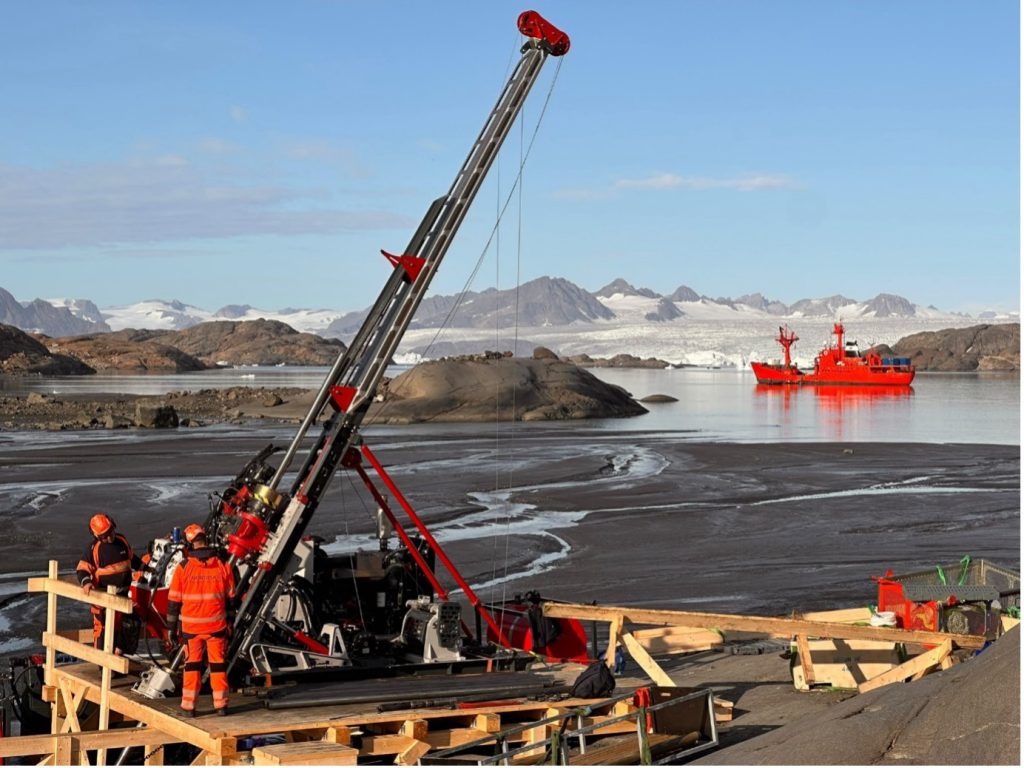
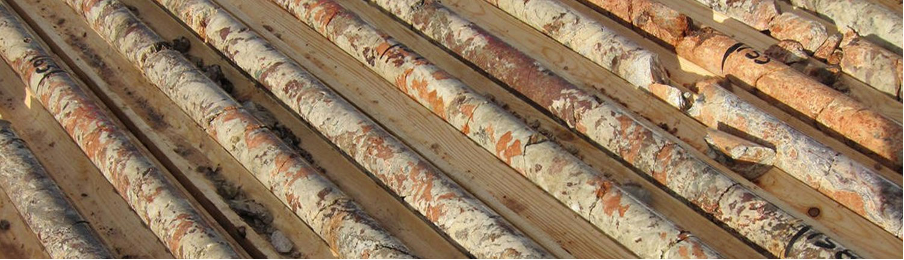
    Its 2026 field programme included drilling, geotechnical work, geophysical surveys, environmental studies and bulk sampling. The company completed 4,480 metres of diamond drilling across 17 holes, together with more than nearly 105 tonnes of bulk material, providing  materials for advanced metallurgical and process flow-sheet bench and pilot plant test-work.

    The bulk-sampling programme itself exceeded the original plan, with 104.8 tonnes of material collected from seven sites. The samples cover different mineralised horizons.

    This work represents an important step as Greenland Mines continues to evaluate and advance the Skaergaard Project towards production.

    Sarfartoq Adds a Second Critical Minerals Opportunity

    The company’s strategy became considerably broader with its acquisition of the Sarfartoq rare earth project in southwest Greenland, which closed in September 2026.

    Sarfartoq is focused particularly on neodymium and praseodymium, two magnet rare earth elements that are important components in permanent magnets used in electric vehicles, wind turbines, robotics, defence systems and other advanced technologies.

    The project has an extensive exploration history, with more than 15 years of drilling, metallurgical testing, engineering studies and environmental work.

    In August, Greenland Mines announced an independently prepared S‑K 1300 Technical Report Summary for Sarfartoq, effective July 31, 2026, reporting an Indicated Mineral Resource under S‑K 1300 for the first time.

    The resource is particularly notable for its concentration of the magnet rare earth elements that are most important to today’s supply chains.

    Greenland Mines also has an important strategic relationship with Neo Performance Materials, which retains offtake rights covering up to 60% of future Sarfartoq ore or mineral concentrate production, subject to the relevant project development conditions.

    That relationship provides the project with a potential connection into Western rare earth processing and magnet supply chains.

    Two Projects, One Broader Strategy

    The combination of Skaergaard and Sarfartoq gives Greenland Mines a differentiated portfolio.

    Skaergaard provides exposure to palladium, gold and platinum, while Sarfartoq adds exposure to neodymium, praseodymium and other rare earth elements.

    This diversification is important because the company is not dependent on a single commodity or project.

    Instead, Greenland Mines is building a portfolio around minerals that are increasingly important to energy, technology, defence and advanced manufacturing.

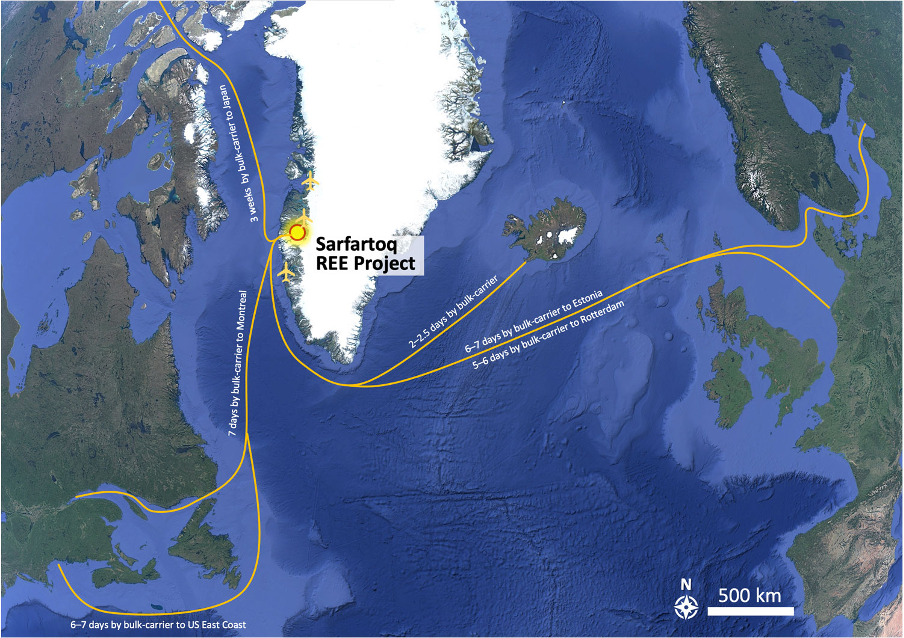
    The company is also pursuing a broader North Atlantic critical minerals strategy, seeking to connect Greenland’s resource base with potential processing, logistics and industrial infrastructure in the wider region. Its strategy includes potential downstream opportunities in Iceland, where it has been developing relationships around industrial infrastructure.

    Moving Towards the Next Stage

    The focus now turns to advancing both projects through their next technical milestones.

    At Skaergaard, the completed 2026 field programme provides additional drilling, sampling, geological, metallurgical and engineering information that can feed into the next phase of development work.

    At Sarfartoq, Greenland Mines is progressing work around resource upgrading, engineering, infrastructure assessment and metallurgical testing, with the company targeting further advancement towards a Pre-Feasibility Study.

    The company is therefore entering the next stage with a substantially broader portfolio than it had at the beginning of 2026.

    For investors looking at the critical minerals sector, Greenland Mines offers an interesting combination: a large-scale palladium-gold-platinum resource at Skaergaard and an advanced rare earth opportunity at Sarfartoq, both located in Greenland and supported by a strategy designed to connect resources with Western supply chains.

    With the two projects now sitting within a single platform, Greenland Mines is positioning itself around some of the mineral resources that could play an increasingly important role in the future of energy, technology, defence and industrial manufacturing.

    Cautionary Note on Project Development
    Greenland Mines’ projects remain at the exploration and development stage. Neither project is in production, and their advancement depends on further technical studies, metallurgical evaluation, permitting, financing and execution. No Initial Assessment or Pre-Feasibility Study has been completed for Skaergaard. Sarfartoq has an Initial Assessment, but further studies and development work remain necessary, and there is no assurance that either project will reach production.

  • ITM Power Narrows FY2026 Adjusted EBITDA Loss Guidance to £20–21 Million

    ITM Power Narrows FY2026 Adjusted EBITDA Loss Guidance to £20–21 Million

    ITM Power (LSE:ITM) has revised its financial guidance for the year ended 30 April 2026, reducing its expected adjusted EBITDA loss to between £20 million and £21 million while maintaining its previous revenue and cash guidance.

    The hydrogen technology company said the revised loss forecast represents a 27% improvement compared with its earlier guidance and a 38% improvement year on year.

    The adjustment indicates that ITM expects to report a smaller adjusted operating loss before interest, tax, depreciation and amortisation than previously anticipated. The company has not announced any changes to its revenue or year-end cash expectations.

    ITM confirmed that it will publish its preliminary financial results for the year ended 30 April 2026 on 19 October 2026.

    The results announcement will provide further details of the company’s financial performance during the reporting period, including its revenue, operating costs and cash position.

    The company also plans to engage with analysts and investors in connection with the results publication, providing an opportunity to discuss its financial performance and operational developments.

    The revised guidance follows ITM’s ongoing activities in the development and manufacture of proton exchange membrane (PEM) electrolysers, which use electricity to separate water into hydrogen and oxygen.

    The company’s technology is designed for industrial-scale hydrogen production, with applications across industrial and energy markets seeking alternatives to conventional hydrogen production methods.

    ITM also operates through its Hydropulse business model, under which it intends to develop, own and operate hydrogen production facilities rather than solely supplying electrolyser equipment to customers.

    The forthcoming preliminary results will provide additional information on the company’s financial position and progress against its operational objectives.

    ITM Power is a UK-based manufacturer of hydrogen production equipment listed on London’s AIM market. Its operations include electrolyser manufacturing, engineering and the development of hydrogen supply solutions using proprietary PEM technology.

  • Jubilee Metals Completes Legal Due Diligence on US$35 Million Zambian Project Disposal

    Jubilee Metals Completes Legal Due Diligence on US$35 Million Zambian Project Disposal

    Jubilee Metals Group (LSE:JLP) has completed legal due diligence for the proposed sale of its Large Waste Project in Zambia, a transaction valued at approximately US$35 million, as the company continues its programme of asset disposals and investment in its Zambian copper operations.

    The company expects to receive a deposit of US$2.25 million in the coming days, coinciding with the commencement of a 45-day technical due diligence period.

    The proposed disposal remains subject to the completion of the technical review, with the transaction forming part of Jubilee’s strategy to redirect capital towards its existing copper mining, processing and refining activities in Zambia.

    Together with approximately US$65 million in remaining cash proceeds from the sale of its South African operations, Jubilee expects potential cash inflows of up to US$100 million from the two transactions.

    The anticipated proceeds would provide additional funding for the group’s Zambian copper development programme, although the Large Waste Project disposal has not yet been completed.

    Jubilee said the planned sale is intended to reduce its exposure to the development requirements of the Large Waste Project while allowing the company to allocate resources to other assets within its portfolio.

    The group is focusing on expanding its existing copper operations, including the Molefe Mine, where results from the second phase of drilling are expected shortly.

    According to management, the company’s investment priorities include projects that can utilise its established mining, processing and refining infrastructure in Zambia.

    These facilities include the Roan Concentrator, which processes copper-bearing feedstock, and the Sable Refinery, which forms part of Jubilee’s integrated copper production operations.

    The company intends to combine processing activities involving third-party feedstock with the development of its own mining and exploration assets.

    The proposed Large Waste Project disposal represents a further step in Jubilee’s restructuring of its asset portfolio following the sale of its South African operations.

    Completion of the transaction and receipt of the remaining consideration will depend on the outstanding due diligence process and applicable transaction requirements.

    Jubilee Metals Group is a copper producer and resource developer listed on London’s AIM market and the Johannesburg Stock Exchange’s AltX market. The company is focused on developing an integrated copper business in Zambia through mining, processing, refining and exploration activities.

  • MedPal AI Reports Record Daily Prescription Orders and £6.4 Million Liquidity Position

    MedPal AI Reports Record Daily Prescription Orders and £6.4 Million Liquidity Position

    MedPal AI (LSE:MPAL) has reported a record day of prescription dispensing at its New Health clinic, processing more than 2,300 private prescription orders with a combined value of approximately £300,000, as the company expands its medication inventory following a £5 million equity placing.

    The digital healthcare and pharmacy group said the placing, which was predominantly supported by existing and institutional investors, is being used primarily to increase medication stock levels to meet demand across its operations.

    As of 6 October 2026, MedPal reported approximately £6.4 million in combined cash, near-cash assets and stock. The company also identified VAT receivables, NHS prescription income and manufacturer rebates as components supporting its working capital position.

    Alongside the recent equity financing, MedPal has received an indicative £8 million working capital financing term sheet from a non-bank lender. The proposal remains indicative, and the company is continuing discussions with banking institutions regarding additional funding arrangements.

    The group has also called a general meeting to seek shareholder approval for resolutions primarily relating to its authority to issue shares and the provision of broker warrants.

    According to MedPal, the proposed resolutions are intended to restore routine corporate authorities following its recent financing activities. The company reiterated that it does not currently plan to undertake a further equity fundraising.

    The trading update follows increased prescription activity at New Health, the group’s private clinic focused on GLP-1 weight management treatments. The reported daily order volume represents a record for the business, although the company has not provided comparative figures for earlier periods in the supplied update.

    MedPal operates a range of digital healthcare and pharmacy services, including NHS Distance Selling Pharmacy hubs, private prescription services and a business-to-business pharmacy supply operation serving care homes.

    The company also provides eMARx electronic medication administration software and is developing Juno, an artificial intelligence-based health companion intended to support patient interactions and healthcare management.

    These services form part of MedPal’s planned Health OS platform, which aims to integrate prescribing, dispensing, medication delivery and AI-supported patient services.

    MedPal AI plc is a London-listed digital health and pharmacy company combining prescription dispensing, healthcare software and artificial intelligence development. Its operations span NHS and private pharmacy services, care home medication supply and digital patient support technologies.

  • Tesco First-Half Adjusted Operating Profit Rises 6.3% to £1.78 Billion as Share Buyback Target Increases

    Tesco First-Half Adjusted Operating Profit Rises 6.3% to £1.78 Billion as Share Buyback Target Increases

    Tesco (LSE:TSCO) reported a 6.3% increase in adjusted operating profit to £1.78 billion for the first half of its 2026/27 financial year, alongside higher sales, earnings and free cash flow.

    The supermarket group recorded sales excluding VAT and fuel of £33.8 billion, representing growth of 1.6% at constant exchange rates. The company attributed its performance to changes in its sales mix, cost reductions and contributions from additional revenue streams.

    Adjusted diluted earnings per share increased 12.2% compared with the corresponding period last year, while free cash flow rose 21% to £1.57 billion. Tesco also reported a reduction in net debt compared with the prior-year period.

    Following the first-half performance, the retailer increased its share repurchase target for the current financial year to £950 million and announced a higher interim dividend.

    Tesco said customer satisfaction reached a record level during the reporting period, supported by its pricing strategy, product development and expansion of digital shopping services.

    Online sales increased 8%, reflecting continued activity across the group’s grocery delivery operations. Tesco also reported growth in its Whoosh rapid delivery service and expanded its delivery arrangements through partnerships with Uber Eats and Deliveroo.

    The company continued to invest in digital capabilities, including the use of artificial intelligence for personalised customer services and product recommendations.

    Other areas of development included Tesco’s retail media activities and its range of non-food products and services, which provide additional revenue opportunities alongside its core grocery operations.

    Management identified cost savings, operational efficiency and the development of additional income streams as factors contributing to the group’s first-half financial performance.

    Tesco’s latest results also reflect its ongoing capital allocation activities, with increased shareholder distributions through the expanded buyback programme and interim dividend.

    Tesco plc is a multinational grocery and general merchandise retailer operating primarily in the UK, Ireland and Central Europe. Its activities include supermarket retailing, online grocery services, rapid delivery and wholesale distribution through Booker.

    The group also operates across clothing, pharmacy, financial services and telecommunications, alongside its principal food retailing business.