Blog

  • Helix Exploration Highlights US Helium Operations Following DOE Critical Material Designation

    Helix Exploration Highlights US Helium Operations Following DOE Critical Material Designation

    Helix Exploration PLC (LSE:HEX) has highlighted the significance of the US Department of Energy’s (DOE) decision to designate helium as a critical material under the Energy Act of 2020, citing the relevance of the classification to its production and processing operations in the United States.

    The designation, announced on 23 October 2026, formally recognises helium’s role in semiconductor manufacturing, advanced technologies and national security, as well as the importance of maintaining reliable domestic supply chains.

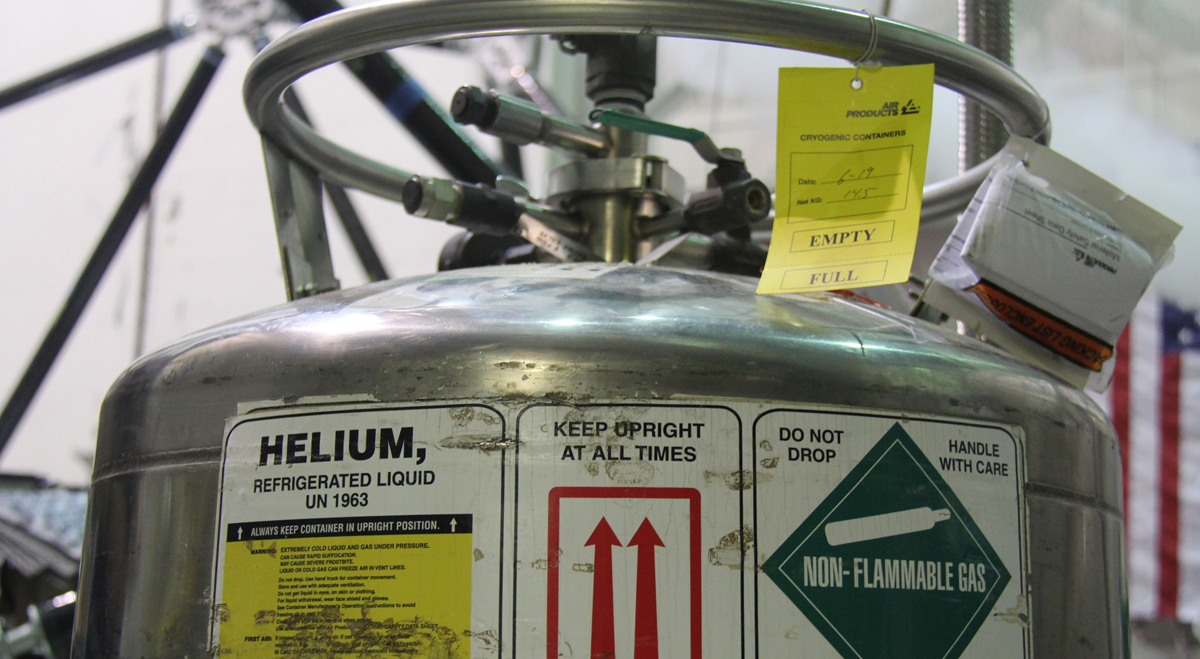
    Helix, which operates helium production facilities in Montana and owns processing and liquefaction infrastructure in Oklahoma, said the decision aligns with its strategy to expand domestic helium production and processing capacity.

    DOE Recognises Helium’s Role in US Supply Chains

    The DOE’s designation reflects the use of helium in semiconductor manufacturing and other advanced technologies, alongside concerns about global supply availability and domestic supply chain resilience.

    The department identified domestic helium resources as an important component of US supply security but acknowledged that limited refining capacity and lengthy permitting processes continue to restrict production.

    Helix said the federal decision provides additional recognition of the importance of investment in US helium production, processing and liquefaction infrastructure.

    The company is developing operations across multiple stages of the helium supply chain, from exploration and extraction to processing and liquefaction.

    Rudyard Production and Oklahoma Liquefaction Infrastructure

    Helix began helium production at its Rudyard Project in Montana in February 2026, followed by its first commercial sales in July. According to the company, Rudyard represents the first helium production operation in Montana.

    The company is progressing a programme to increase production and processing capacity at the site, using its existing infrastructure and company-owned drilling rig.

    In July 2026, Helix acquired the Keyes Helium Complex in Oklahoma, gaining ownership of one of six operational helium liquefaction facilities in the United States.

    Liquefaction allows helium to be stored and transported more efficiently for delivery to customers in industrial, medical and advanced technology markets.

    Helix said its combination of production assets, drilling equipment and downstream processing infrastructure provides opportunities to expand output and undertake third-party processing and liquefaction activities.

    The company believes the DOE’s designation supports its longer-term investment strategy, although the announcement did not include changes to production targets, financial guidance or planned capital expenditure.

    Helix Outlines Plans for Further Capacity Expansion

    Helix intends to continue expanding its production and processing operations at Rudyard while developing its integrated helium business through the Keyes facility.

    The company said its existing infrastructure provides a foundation for increasing domestic helium supply and participating in different stages of the US supply chain.

    Bo Sears, Chief Executive Officer of Helix Exploration, said the federal designation recognises the importance of domestic helium resources and the infrastructure needed to supply industrial and technology markets.

    Management also highlighted the company’s transition from exploration to commercial production since its initial public offering and the addition of liquefaction capacity through the Keyes acquisition.

    Helix said it remains focused on increasing production capacity and developing its position as an integrated helium supplier serving US and international customers.
  • Are Investors Increasing Protection Against AI Debt Risk? CDS Trading Volumes Rise

    Are Investors Increasing Protection Against AI Debt Risk? CDS Trading Volumes Rise

    Why is trading in AI-related credit derivatives increasing?

    Investors are purchasing more credit default swaps linked to major technology companies as borrowing to finance artificial intelligence infrastructure expands.

    According to Morgan Stanley Research, CDS trading associated with bonds issued by Oracle (NYSE:ORCL), SpaceX (NASDAQ:SPCX), Alphabet (NASDAQ:GOOGL), Amazon (NASDAQ:AMZN), Meta (NASDAQ:META), Broadcom (NASDAQ:AVGO) and Nvidia (NASDAQ:NVDA) averaged more than $9 billion per week in September.

    The figure represents a substantial increase from less than $2 billion in July.

    Bloomberg data also indicate that trading in US corporate CDS indices has already surpassed the volume recorded for the whole of 2025.

    The increase reflects demand from investors seeking protection against changes in corporate credit risk as technology companies expand their borrowing.

    How has AI-related debt issuance changed?

    Morgan Stanley estimates that AI-linked companies have issued approximately $466 billion of debt so far in 2026.

    That compares with $101 billion during the corresponding period last year.

    The borrowing is being used to finance data centres, semiconductors and other infrastructure required for artificial intelligence services.

    The scale of investment has prompted closer examination of how quickly companies can generate revenue and cash flow from their infrastructure spending.

    Investors are also considering the financial connections between AI developers, cloud computing providers and the companies supplying the necessary hardware.

    Which companies have seen the largest increases in credit protection costs?

    Several major technology companies have experienced record CDS spreads.

    Meta’s five-year CDS reached 108 basis points this month, while Nvidia’s rose to 101 basis points.

    Oracle’s spread increased to 322 basis points on Monday from 144 basis points at the start of 2026.

    SpaceX’s CDS reached 226 basis points, compared with 110 basis points when trading began in late June.

    Alphabet and Amazon also recorded all-time highs in their credit protection costs, while Microsoft (NASDAQ:MSFT) and CoreWeave (NASDAQ:CRWV) experienced increases.

    A higher CDS spread means that investors must pay more to obtain protection against a specified credit event, although the price can also reflect market liquidity and demand for hedging.

    Why are portfolio managers using CDS instead of selling their investments?

    Credit default swaps allow investors to obtain protection against credit events without necessarily selling their existing securities.

    Multi-asset and equity managers are using these instruments to manage risks associated with their exposure to AI-related businesses.

    The approach has become more relevant because companies across the AI sector are linked through infrastructure contracts, financing commitments and commercial relationships.

    “CDS has become a key bellwether of investor sentiment towards hyperscaler funding and the broader AI trade,” said Société Générale’s Manish Kabra.

    The increased activity indicates that investors are monitoring corporate credit markets alongside equity valuations when assessing the sector.

    What makes CoreWeave’s CDS pricing different?

    CoreWeave’s five-year CDS spread reached approximately 1,090 basis points, substantially higher than the spreads reported for many larger technology companies.

    At the quoted price, purchasing $10 million of protection would require an upfront payment of around $1.82 million, followed by quarterly payments of $125,000.

    The pricing reflects the terms of the CDS contract and the market’s assessment of the risks associated with CoreWeave’s debt.

    Robert Dafforn, chief investment officer at Polus Capital, pointed to the high levels of leverage used in parts of the AI infrastructure sector.

    He also expressed concern that some capital expenditure may not produce sufficient returns.

    What could influence CDS markets in the coming months?

    Future demand for AI-related credit protection will depend partly on borrowing requirements, financing costs and the financial performance of companies developing AI infrastructure.

    The expansion in debt issuance has increased the importance of assessing whether expected revenue can support investment and repayment obligations.

    CDS spreads provide one market-based measure of changing credit conditions, but they do not independently establish whether a company will default.

    The recent rise in trading volumes and protection costs indicates that investors are increasingly using credit derivatives to manage risks associated with the financing of artificial intelligence infrastructure.

  • Have Government Bond Yields Peaked? JPMorgan Sees Potential Support for Global Stocks

    Have Government Bond Yields Peaked? JPMorgan Sees Potential Support for Global Stocks

    What is JPMorgan’s latest view on bond markets?

    JPMorgan strategists led by Mislav Matejka believe the recent rise in government bond yields may be losing momentum, potentially improving conditions for equity markets through the end of 2026.

    The bank previously identified signs that the increase in yields had become extended and that bonds were entering oversold territory.

    Its fixed income team’s year-end forecasts for longer-dated yields across major markets are now broadly in line with or below prevailing levels.

    The outlook suggests that further substantial increases in borrowing costs are not central to JPMorgan’s current market expectations.

    Why would stable yields benefit equity valuations?

    Higher government bond yields have contributed to declining equity valuation multiples by increasing the cost of capital and changing the relative returns available to investors.

    During the recent bond market selloff, forward price-to-earnings multiples fell by three points for the S&P 500 and MSCI All-Country World Equity Index.

    European equity multiples declined by approximately two points.

    JPMorgan believes the pressure on valuations could moderate if yields stop rising.

    “The multiple compression might not need to continue,” the strategists said.

    The bank also expects more stable yields to ease concerns about consumer finances, the durability of the economic cycle and funding costs for AI-related investment.

    Have markets already adjusted to the Federal Reserve’s interest rate outlook?

    JPMorgan believes that most of the repricing associated with Federal Reserve interest rate expectations has already occurred.

    The strategists said changes in federal funds futures account for nearly all of the increase in the 10-year US Treasury yield this year.

    They do not anticipate substantial further adjustments to the market’s expectations for US policy rates.

    Inflation expectations also remain contained, according to consumer surveys and financial market measures.

    Although recent US inflation figures have been elevated, JPMorgan estimates that underlying inflation is only around 0.3 percentage points above levels before the Iran war.

    European core inflation trends remain broadly similar to their pre-conflict levels, while wage growth and wage expectations remain subdued.

    Could AI debt issuance or European sovereign risks disrupt the outlook?

    JPMorgan does not expect borrowing by AI-related companies to materially reduce demand for government bonds.

    The bank also believes free cash flow at major hyperscale technology companies could prove better than current forecasts suggest.

    In Europe, the strategists identified France as an ongoing concern but did not consider a broader sovereign debt crisis their central scenario.

    They cited the European Central Bank’s policy tools, stronger banking sector balance sheets, more diversified sovereign bond holdings and lower credit defaults than during the 2010–2012 eurozone debt crisis.

    These factors support JPMorgan’s view that current financial risks may remain contained, although they have not been eliminated.

    What do corporate earnings suggest about the year-end equity outlook?

    JPMorgan described the early third-quarter earnings season as broadly supportive of equities.

    Among the first 29 US companies and 14 European companies to report, most exceeded earnings expectations and raised their guidance.

    The bank believes continued earnings growth, combined with stabilising bond yields, could help global stock markets recover from recent valuation pressure.

    Oil prices remain a source of uncertainty because of their potential effects on inflation and monetary policy expectations.

    Nevertheless, the strategists concluded that equities could perform positively through year-end if bond yields and corporate earnings develop in line with their forecasts.

  • Why Is Jefferies Concerned About iPhone 18 Pro Sales? China Discounts and Supply Chain Cuts Raise Questions

    Why Is Jefferies Concerned About iPhone 18 Pro Sales? China Discounts and Supply Chain Cuts Raise Questions

    What has Jefferies identified in the latest iPhone sales data?

    Jefferies analyst Edison Lee has reported further signs of weaker demand for Apple’s (NASDAQ:AAPL) iPhone 18 Pro and Pro Max, citing changes in delivery availability, resale pricing and component orders.

    In a Monday research note, Lee said the brokerage’s monitoring continued to indicate subdued demand for the two premium models.

    The assessment contrasts with reported growth in overall iPhone sales in China, which Jefferies believes was partly supported by discounted sales of older devices.

    Why are shorter delivery times significant?

    Jefferies reported that delivery times for both iPhone 18 Pro models in China have declined to zero days.

    The comparable waiting periods for the previous generation were six days for the Pro and 25 days for the Pro Max.

    Delivery times in Japan have also shortened substantially year on year.

    However, Jefferies noted that US delivery times for the Pro Max have increased, indicating that availability trends differ between markets.

    Shorter lead times can reflect reduced demand, increased supply or a combination of the two factors.

    What has happened to iPhone pricing in China?

    Chinese online retailer PDD introduced discounts of 6% for the iPhone 18 Pro and 9% for the Pro Max on 16 October.

    Jefferies also found that resale prices for the Pro models had moved below retail prices from 29 September.

    By comparison, the equivalent devices last year were trading at premiums of between 1% and 6%.

    The brokerage views these pricing changes as additional evidence that demand for the latest premium models may be below earlier expectations.

    Are Apple’s suppliers receiving fewer orders?

    Jefferies said industry contacts have reported reductions of approximately 10% to 15% in orders for certain iPhone components, including 2-nanometre chips.

    The reported change in final assembly orders has been smaller, with some suppliers indicating a net reduction of around 2 million devices.

    The difference suggests that the full effect of component order adjustments on finished-device production remains uncertain.

    “We will continue to monitor supply chain feedback, but do believe further order cuts are possible if weak demand continues,” Lee wrote.

    Apple has not confirmed the reported reductions in the information cited by Jefferies.

    Why do overall iPhone sales figures present a different picture?

    Reported iPhone sales volumes in China increased by more than 40% year on year during the first two weeks after shipments began.

    That rate slowed to approximately 8% in early October.

    Jefferies believes discounted sales of remaining iPhone 17 Pro and Pro Max inventory contributed to the initial increase.

    As a result, the brokerage argues that overall iPhone sales growth should not be interpreted as a direct measure of demand for the iPhone 18 Pro range.

    What is the outlook for Apple’s foldable Duo?

    Apple’s foldable Duo recorded delivery lead times exceeding 90 days after pre-orders began on 16 October.

    Jefferies estimates that this corresponds to a maximum of approximately 6 million to 7 million shipments during 2026, consistent with market expectations.

    The extended waiting period differs from the immediate availability reported for the iPhone 18 Pro models in China.

    Jefferies will continue monitoring supply chain information, retail pricing and delivery times to assess whether Apple makes further adjustments to production.

  • Evercore Outlines Key Credit and Treasury Yield Thresholds That Could Signal AI Stock Market Correction

    Evercore Outlines Key Credit and Treasury Yield Thresholds That Could Signal AI Stock Market Correction

    Evercore strategists have identified a series of financial market indicators that could signal a correction in artificial intelligence-related stocks following last week’s technology sector selloff.

    In a research note published on Sunday, a team led by Julian Emanuel said the recent declines marked the beginning of a price discovery phase for AI investments, with investors reassessing valuations, borrowing costs and the financial requirements of large-scale infrastructure development.

    The firm identified four indicators that could signal a transition from the current bull market into a correction, or potentially a bear market if economic conditions deteriorate into recession.

    Despite the identified risks, Evercore reiterated its year-end 2026 target of 7,750 for the S&P 500.

    Credit Spreads and Earnings Revisions Among Key Indicators

    Evercore highlighted four market developments that it believes warrant close attention as investors evaluate the sustainability of the AI-related equity rally.

    The first is an increase in investment-grade credit default swap (CDS) spreads above their March peak of 68.33.

    The second is a rise in high-yield CDS spreads beyond their previous high of 411.04.

    CDS spreads reflect the cost of obtaining protection against a borrower’s default. An increase generally indicates that market participants are demanding greater compensation for credit risk.

    The third indicator is a reversal in the upward trend of analysts’ earnings-per-share estimates, which could suggest that expectations for corporate profitability are weakening.

    The fourth is a rise in the yield on 10-year US Treasury securities above 5.62%.

    According to Evercore, these indicators could help determine whether recent market weakness remains concentrated in technology stocks or develops into a broader reassessment of financial asset valuations.

    US Treasury Yield of 5.62% Identified as Fiscal Warning Level

    Evercore’s Washington policy team said a 10-year Treasury yield above 5.62% could increase concerns about US fiscal conditions and government borrowing costs.

    The strategists noted that the recent yield peak of 5.36% provided a reference point for assessing further increases.

    They described 5.62% as “a reasonable level at which alarm bells would be expected to ring.”

    The team referred to such a development as a potential “fiscal alarm bell.”

    Higher government bond yields can influence borrowing costs across the economy, including corporate debt financing and household lending.

    They can also affect equity valuations by increasing the discount rates applied to expected future earnings.

    This relationship is particularly relevant for growth-oriented technology companies, where a substantial proportion of market valuations may depend on profits expected several years into the future.

    Evercore Questions Assumptions Behind AI Debt Expansion

    The strategists also examined the financing requirements associated with the expansion of AI infrastructure.

    Evercore referred to an estimated $1.3 trillion in investment by 2027, including spending on data centres, computing capacity and related infrastructure.

    The firm questioned the assumption that major technology companies, often described as hyperscalers, could continue issuing debt regardless of market conditions, even if their free cash flow became negative.

    Evercore characterised that assumption as “pure fantasy.”

    The strategists argued that borrowing costs, investor demand and access to capital markets remain important constraints on corporate investment plans.

    Their analysis suggests that the increasing use of debt to finance AI infrastructure could make the sector more sensitive to changes in credit conditions.

    Previous Market Cycles Provide Historical Comparisons

    Evercore compared current investor expectations with several previous periods of financial market instability.

    These included the collapse of the dot-com bubble in 2000, the 2018 equity market decline associated with trade tensions and Federal Reserve rate increases, and the bursting of Japan’s asset price bubble in 1989.

    The firm also referenced the prolonged period of economic stagnation that followed Japan’s market downturn.

    “Last week reaffirmed the ‘this time is no different’ notion amid a perfect storm for the AI bull market, highlighting dividing lines that, if crossed, could tip the bull market into correction, or even bear market,” Emanuel’s team wrote.

    The comparisons were used to illustrate the potential consequences of changes in market expectations and financing conditions.

    They do not establish that the current AI investment cycle will follow the same pattern as those earlier episodes.

    Evercore Maintains AI Equity Exposure With Risk Hedges

    Although Evercore identified several potential warning signals, the firm maintained its recommendation to retain exposure to selected AI-related stocks while the specified market thresholds remain unbreached.

    The strategists referred to their preferred group of companies as the “AI class of 2026.”

    They also recommended maintaining hedges against potential volatility surrounding the November 3 US midterm elections.

    The suggested strategies included exposure to negative-beta stocks, S&P 500 straddles and December Nasdaq-100 put spread collars.

    Negative-beta securities may provide diversification when broader equity markets decline, while options-based strategies can be structured to manage exposure to market movements.

    Evercore’s recommendations reflect its assessment of current market risks and potential investment positioning rather than a forecast that a correction will necessarily occur.

    Technical Levels Could Influence Investment Positioning

    Evercore also identified technical reference points that could prompt changes to its recommended equity exposure.

    The strategists suggested that investors could increase long positions and remove hedges if the Nasdaq-100 tested its 200-day moving average, described in the source report as being around 674.

    They identified a corresponding level of 725 for the S&P 500.

    The reported figures appear inconsistent with the headline levels of the two indices and may refer to a different technical measure. The original information does not provide sufficient detail to resolve that discrepancy.

    The strategists nevertheless presented these levels as potential conditions for adjusting market positioning.

    S&P 500 Year-End Target Remains at 7,750

    Evercore maintained its S&P 500 target of 7,750 for the end of 2026 despite the recent decline in technology shares.

    The firm’s analysis distinguishes between short-term price volatility and developments that could indicate a more sustained deterioration in market conditions.

    Its framework places particular emphasis on credit market spreads, corporate earnings revisions and Treasury yields as measures of financial pressure.

    The report also highlights the importance of debt financing as technology companies expand their AI infrastructure investment programmes.

    For now, Evercore’s outlook remains conditional on whether the identified market indicators cross their specified thresholds and whether broader economic conditions continue to support corporate earnings.

  • Market Open: BlackRock Smaller Companies Buyback, Trustpilot Board Changes

    Market Open: BlackRock Smaller Companies Buyback, Trustpilot Board Changes

    FTSE 100 opens flat as weak UK retail sales weigh. BlackRock Smaller Companies buys back shares, Trustpilot reshapes its board and Brent edges up.

    Market Overview

    European markets opened cautiously on Friday. The FTSE 100 was broadly flat, down 0.002 per cent at 10,724.72, after UK retail sales volumes fell 0.4 per cent in September, a weaker result than forecast, and consumer confidence dropped sharply ahead of next week’s Budget. The Euronext 100 edged up 0.068 percent to 1,845.68. The DAX fell 0.177 percent to 25,326.66 as civil unrest in France pushed French government bond yields to 24-year highs and investors moved out of continental equities. On Wall Street, the Nasdaq closed down 2.90 per cent at 28,958.69 and the S&P 500 fell 1.21 per cent to 7,663.43, as concerns over AI-related spending and debt financing weighed on technology shares.

    Geopolitical risk remains the main macro driver. Brent crude edged higher, staying near five-month highs on fears of a US-Iran conflict and Houthi strikes on Saudi energy infrastructure, which have added to inflation concerns ahead of next week’s central bank meetings. Gold was unchanged, while copper and natural gas slipped slightly. Bitcoin eased against sterling. The pound was mixed: marginally weaker against the US dollar, slightly firmer against the yen, Australian dollar and Swiss franc, and flat against the euro.


    Market Numbers

    FTSE 100: Down (-0.002%), 10,724.72
    Euronext 100: Up (+0.068%), 1,845.68
    DAX: Down (-0.177%), 25,326.66
    NASDAQ: Down, 28,958.69
    S&P 500: Down, 7,663.43


    In the Headlines

    Share buyback – BlackRock Smaller Companies Trust (LSE:BRSC)
    BlackRock Smaller Companies Trust bought back 85,000 ordinary shares at an average of 266 pence each and is holding them in treasury, which now holds 61,143,655 shares, or 20.47 per cent of issued capital. From 26 October, the trust’s voting share capital falls to 237,548,950 shares, the figure shareholders should use for FCA disclosure thresholds.

    Board changes – Trustpilot Group (LSE:TRST)
    Trustpilot is changing its board committees from 1 November. Joe Hurd will chair the Trust & Transparency Committee, Claire Davenport will take responsibility for workforce engagement, and John-Paul Savant will join the Audit & Risk Committee. The company says the changes are meant to strengthen oversight of trust, transparency and risk, which are central to how it is valued as a review platform.


    Currencies (vs GBP)

    USD: Down (-0.0037%), $1.3403
    CHF: Up (+0.0018%), Fr.1.099
    EUR: Unchanged (0.00%), €1.1945
    JPY: Up (+0.0179%), ¥209.804
    AUD: Up (+0.0131%), $1.9096
    Bitcoin (BTC/GBP): Down (-0.32%), £61,084.5


    Commodities

    Copper: Down
    Gold: Unchanged
    Brent Crude: Up
    Natural Gas: Down

  • Aquis Stock Exchange Weekly Highlights 19.10.26

    Reveille Resources PLC (AQSE:REV) announced the appointment of Dr Camillo Mario Pessina, the former lead geologist for Val Vedello at AGIP Nucleare, as a Strategic Consultant, bringing first-hand knowledge of Italy’s largest uranium deposits. Read more

    ProBiotix Health Plc (AQSE:PBX) reported sales up 36% and gross profit up 88% for the nine months to September 2026,  resulting in an EBITDA profit compared to a loss in the same period last year.

    Steen Andersen, CEO: “We are pleased with the continued growth achieved during the first nine months of 2026, and the resilience demonstrated by the business, despite ongoing global uncertainty affecting some of our markets. Our investment in the Chinese market is beginning to deliver results, and with the refocused US commercial activities expected to gain momentum in early 2027, we remain confident in the Group’s outlook and future growth prospects.” Read more

    energy B plc (AQSE:NRGB) announced agreements to increase its shareholding in the Gatwick energy site to 100%, with production expected to restart in early 2027. The Company also raised £100,000 through a placing and conditional subscription, with Chairman David Lenigas subscribing for £50,000.

    Neil Ritson, CEO: “These minority interest buyout agreements are important to us as they will give us day to day control of the Gatwick energy site going forward. This will allow us to streamline our approach to the future field development and in dealing with the UK Government and regulators. We hope to restart production at the site early 2027.” Read more

    Wishbone Gold Plc (AQSE:WSBN) announced the latest assay results from its ongoing drilling programme at the Red Setter project in Western Australia, identifying wide zones of gold and copper mineralisation at shallow depths. Read more

    Arbuthnot Banking Group PLC (AQSE:ARBB) reported strong Q3 results with customer loans up 12%, funds under management up 21% and full year profit now expected to be ahead of prior expectations. Read more

    Sulnox Group PLC (AQSE:SNOX) announced the appointment of Exeno Yamamizu Corporation as its first Japan-based distributor, marking Sulnox’s entry into the world’s third-largest shipowning nation.

    Ben Richardson, CEO: “Japan is one of the world’s most influential maritime markets and an important step in our growth across Asia. Its shipowners hold themselves to exacting standards, and we believe the evidence behind Sulnox Eco will resonate strongly with them.” Read more

    All Aquis Stock Exchange Announcements

  • Could CoreWeave’s Debt Problems Affect Global Banks? J.P. Morgan Assesses Lending Exposure

    Could CoreWeave’s Debt Problems Affect Global Banks? J.P. Morgan Assesses Lending Exposure

    What prompted J.P. Morgan’s review of CoreWeave’s financing?

    J.P. Morgan examined global banks’ exposure to CoreWeave (NASDAQ:CRWV) following a decline in the AI cloud infrastructure provider’s shares and bonds.

    The market movements occurred amid growing scrutiny of the borrowing required to finance the expansion of artificial intelligence infrastructure.

    CoreWeave has accumulated approximately $50 billion in debt while developing computing capacity for major technology customers.

    Last week, the yield on its bonds due in 2031 approached 16%, while the cost of credit default protection rose to around 1,000 basis points.

    The developments prompted questions about whether financial pressure at AI infrastructure companies could create risks for the banks providing their funding.

    How much exposure do major banks have to CoreWeave?

    According to J.P. Morgan, large US investment banks and Japan’s MUFG could each have between $1 billion and $3 billion in exposure to CoreWeave.

    Most other European and Asian institutions are estimated to have exposures below $500 million.

    The figures are based on simplified assumptions because banks do not provide comprehensive disclosures about their lending and investment exposure to the AI infrastructure sector.

    J.P. Morgan therefore cautioned that the estimates should not be treated as precise measures of individual banks’ positions.

    What protects banks involved in CoreWeave’s financing?

    J.P. Morgan identified the structure of CoreWeave’s borrowing arrangements as an important factor in assessing lenders’ risks.

    Much of the financing consists of delayed draw term loans, under which committed funds are released in stages as projects achieve agreed milestones.

    These arrangements are largely managed through special-purpose vehicles and are supported by security arrangements linked to the financed assets.

    CoreWeave has approximately $24 billion in committed delayed draw term loans, including $15 billion already drawn and $9 billion not yet utilised.

    J.P. Morgan analysts led by Kian Abouhossein said the banks’ exposures were well managed and secured.

    The brokerage’s assessment suggests that the structure of the financing may limit direct lender risks, although it does not remove the possibility of losses.

    Why does CoreWeave still face financing challenges?

    CoreWeave’s business requires substantial spending on data centres and computing equipment before the full revenue associated with customer contracts is received.

    The company has secured agreements worth tens of billions of dollars with major technology businesses, but its infrastructure expansion continues to require external capital.

    J.P. Morgan identified the timing difference between upfront investment and future customer payments as a central financial risk.

    The brokerage expects CoreWeave’s free cash flow to remain negative until 2030.

    This forecast indicates that the company may continue to require financing to support its capital expenditure and operating requirements.

    What is J.P. Morgan’s outlook for CoreWeave shares?

    J.P. Morgan maintains an overweight rating on CoreWeave, with a price target of $125 for the end of 2027.

    The brokerage’s assessment of the banking sector focuses on the direct credit exposure of lenders rather than solely on movements in CoreWeave’s share price or bond yields.

    Although the company’s debt securities have experienced significant selling pressure, J.P. Morgan estimates that most global banks have relatively limited exposure.

    The analysis also highlights the uncertainty surrounding broader AI infrastructure financing, particularly because banks provide limited disclosure about their involvement in the sector.

    For lenders, the principal considerations remain the security supporting individual loans, the progress of financed projects and the ability of borrowers to generate sufficient cash flow over time.

  • Could China Prevent a SpaceX-Tesla Merger? JPMorgan Examines Regulatory Risks and a Possible Solution

    Could China Prevent a SpaceX-Tesla Merger? JPMorgan Examines Regulatory Risks and a Possible Solution

    What is JPMorgan’s assessment of a potential SpaceX-Tesla merger?

    JPMorgan believes regulatory approval in China represents the most substantial obstacle to a potential merger between SpaceX and Tesla (NASDAQ:TSLA), despite the need for Tesla shareholder support.

    Analyst Rajat Gupta outlined the risks in a Wednesday research note following Elon Musk’s disclosure that special committees at both companies had begun formally examining a possible combination.

    The bank considers a merger strategically feasible but believes Tesla’s significant Chinese operations could complicate regulatory approval because of SpaceX’s relationships with the US defence sector.

    No binding merger agreement has been announced.

    What transaction terms is JPMorgan considering?

    JPMorgan’s preliminary analysis assumes a premium of approximately 30% to 35% to Tesla’s market capitalisation.

    The bank believes such a premium could support a merger-of-equals structure while allowing Musk to retain voting control exceeding 50% in the combined business.

    Musk increased his voting stake in Tesla to approximately 20% in June 2026 after exercising his 2018 compensation award.

    Gupta interpreted the increase as potentially relevant to a future shareholder vote.

    SpaceX’s valuation of approximately $2 trillion, around 10% above its initial public offering valuation, could also provide shares for an equity-financed transaction.

    JPMorgan analyst Doug Anmuth separately raised his SpaceX price target to $500, more than doubling his previous estimate.

    Why does JPMorgan see a strategic rationale for combining the companies?

    Tesla and SpaceX already have commercial and technological relationships that JPMorgan believes could support a combined corporate structure.

    The bank identified shared engineering resources, artificial intelligence infrastructure and the Terafab chip facility in Texas among the factors supporting a potential transaction.

    SpaceX has purchased Tesla Megapack batteries and Cybertrucks, while Tesla invested $2 billion in xAI, which has since become part of SpaceX.

    “The strategic logic for a combination remains coherent,” Gupta wrote, referring to the businesses’ existing connections and Musk’s leadership.

    The analysis suggests that a merger could consolidate several related technology activities, although no financial synergies have been formally disclosed.

    Why could Chinese regulators oppose the transaction?

    Tesla generates approximately one-fifth of its revenue in China, which also accounts for a larger proportion of the company’s operating earnings and free cash flow.

    Its Shanghai manufacturing operations are an important part of the business.

    Although JPMorgan attributes only about 10% of its approximately $1.7 trillion sum-of-the-parts valuation to China, the bank considers those operations significant from a regulatory perspective.

    The potential merger would also involve SpaceX, a company with extensive US defence-related contracts.

    Starlink, SpaceX’s satellite communications business, has not been authorised to operate in China.

    Gupta believes these factors could make Chinese approval more difficult than obtaining support from Tesla shareholders.

    Could Tesla separate its Chinese business to facilitate a merger?

    JPMorgan outlined a potential ownership structure intended to address the Chinese regulatory challenge.

    Under the proposal, Tesla’s Chinese operations could be placed under the majority control of a consortium based in China.

    The consortium could hold more than 50% of the local entity, while Tesla would continue receiving payments through licensing agreements.

    Those arrangements could cover Tesla’s brand, separated Full Self-Driving technology and possible future commercial agreements involving Optimus.

    JPMorgan compared the proposal with the ownership and control arrangements associated with TikTok in the United States, but in reverse.

    “We believe one such avenue would be to ring-fence TSLA’s China business or transfer control,” Gupta wrote.

    The arrangement remains hypothetical, and there is no indication that Chinese regulators or the companies have agreed to it.

    What remains unresolved before a merger could proceed?

    A potential transaction would require agreement on valuation, ownership and voting arrangements, together with the relevant shareholder and regulatory approvals.

    JPMorgan also considers Musk’s broader interest in consolidating artificial intelligence-related businesses a factor supporting the merger rationale.

    The bank described the longer-term objective as bringing the AI ecosystem under a single corporate structure.

    However, its analysis identifies Chinese regulatory approval as the central unresolved issue, particularly given Tesla’s manufacturing presence in Shanghai and SpaceX’s US defence relationships.

    The special committees at Tesla and SpaceX are examining a possible combination, but no definitive merger terms or timetable have been announced.

  • Could the AI Market Bubble Burst Soon? Yardeni Research’s Indicator Points to Limited Near-Term Triggers

    Could the AI Market Bubble Burst Soon? Yardeni Research’s Indicator Points to Limited Near-Term Triggers

    What is Yardeni Research’s latest assessment of the AI market?

    Yardeni Research has identified bubble-like conditions in artificial intelligence-related equities but says the financial factors that have preceded previous market downturns are not yet sufficiently widespread to indicate an imminent reversal.

    The firm’s assessment is based on a newly developed AI Bubble Meter, created using Anthropic’s Claude Fable 5.1 model.

    The indicator compares current market conditions with historical episodes of speculative investment, including the technology boom that ended in 2000 and the US housing expansion that reversed in 2006–2007.

    According to Yardeni Research, the tool currently indicates that a bubble exists, although the factors associated with its potential collapse remain comparatively limited.

    What does the new AI Bubble Meter measure?

    The model separates market conditions into two categories.

    The first, Conditions, evaluates whether the characteristics associated with previous financial bubbles are present.

    The second, Triggers, examines developments that could bring a speculative expansion to an end, particularly rising financing costs and excessive credit growth.

    Yardeni Research reported a Conditions score of 83 out of 100, compared with a Triggers score of 34.

    The difference between the readings suggests that although AI-related market valuations display characteristics associated with previous bubbles, the broader financial pressures that contributed to earlier downturns are not yet fully established.

    Which financial risks have started to emerge?

    One development identified by the firm is the increase in the yield on the two-year US Treasury note.

    The yield has risen 115 basis points from its December low, indicating higher short-term borrowing costs.

    Yardeni Research is comparing that increase with the rises of approximately 200 to 350 basis points recorded before the reversals associated with the technology bubble in 2000 and the housing bubble in 2006.

    The firm also noted that credit conditions outside AI-related activities have not shown the same degree of expansion associated with previous speculative cycles.

    “The preconditions of a bubble are in place and have been for a while, but the forces that ended past booms are only partially present,” Yardeni Research said.

    What does the historical evidence show?

    Yardeni Research examined market data dating back to 1965 to assess the relationship between its indicators and subsequent S&P 500 performance.

    When Conditions readings were high but Triggers readings remained low, a bear market followed within two years in 9% of the historical periods examined.

    The S&P 500 recorded a median inflation-adjusted return of 18.3% over the following two years during those periods.

    When both indicators were elevated, the historical incidence of a bear market within two years increased to 42%.

    Those periods were also associated with a median inflation-adjusted market decline of 12.5%.

    The findings illustrate how the model distinguishes between speculative market conditions and the financial developments that have historically accompanied significant corrections. They do not establish the probability of a future downturn.

    Why is the Triggers reading particularly important?

    Yardeni Research considers the Triggers indicator relevant to assessing whether current conditions are becoming more similar to those observed before earlier market reversals.

    The firm said:

    “But the Triggers dial is the one to watch: If it starts rising toward High, so do the risks.”

    Further increases in Treasury yields, particularly alongside signs of excessive credit expansion, could affect the indicator’s assessment.

    The current Triggers score of 34 remains below the Conditions reading of 83, indicating a difference between the presence of bubble characteristics and the development of potential catalysts for a correction.

    What role will upcoming AI company earnings play?

    Yardeni Research also intends to review third-quarter financial reports from major hyperscale computing companies for indications of unused infrastructure capacity.

    The analysis will focus on whether investment in AI computing facilities is being matched by demand for the services those facilities provide.

    Evidence of excess capacity could become relevant to assessments of the sustainability of capital spending across the sector.

    For the time being, the firm’s AI Bubble Meter identifies elevated speculative conditions without showing the same level of financial triggers associated with previous major market downturns.