Author: Fiona Craig

  • Nuformix Reports Positive Preclinical Data for Inhaled Fibrosis Candidate NXP002

    Nuformix Reports Positive Preclinical Data for Inhaled Fibrosis Candidate NXP002

    Nuformix (LSE:NFX) has reported encouraging preclinical results from an inhaled pharmacokinetic and target engagement study of NXP002, its lead development candidate for idiopathic pulmonary fibrosis, progressive pulmonary fibrosis and other progressive fibrosing interstitial lung diseases.

    The study demonstrated that NXP002 could be successfully nebulised across a broad range of doses, producing substantial and dose-dependent exposure within the lungs while keeping systemic exposure relatively limited. Achieving high local concentrations with reduced exposure elsewhere in the body is an important consideration for therapies intended to be administered by inhalation over extended periods.

    Nuformix said lung concentrations reached levels expected to produce pharmacological activity. The study also demonstrated attenuation of a key fibrosis biomarker in vivo, providing further evidence that NXP002 is engaging its intended biological target.

    The findings allow the company to begin modelling a potential therapeutic window for NXP002, with the aim of identifying dose levels capable of delivering sufficient efficacy while maintaining an appropriate safety profile. The results also provide an important link between Nuformix’s previous ex vivo work using human lung tissue and its latest in vivo inhalation studies.

    Following the positive data, Nuformix plans to advance NXP002 through additional preclinical development, including non-GLP dose-range-finding studies. These activities are intended to generate further information on dosing, efficacy and tolerability as the company builds the evidence required to support the programme’s next stages.

    The results could also strengthen Nuformix’s position in discussions with potential development and commercial partners. The company expects to continue its partnering activities, including engagement with industry participants around the upcoming European Respiratory Society Congress.

    Nuformix’s wider investment outlook remains constrained by its early-stage financial profile. The company currently generates no revenue and continues to record losses and negative free cash flow, leaving cash requirements and balance-sheet resources as important considerations. Technical indicators are also weak, with the shares trading below major moving averages. Valuation provides some support through a relatively low price-to-earnings measure, although this does not fully offset the risks associated with continued cash burn and limited financial resources.

    More About Nuformix Plc

    Nuformix plc is a UK-listed pharmaceutical development company focused on developing treatments for areas of unmet medical need, particularly fibrosis and oncology.

    The company uses drug repurposing alongside its expertise in discovering, developing and patenting novel forms of existing compounds. Its approach is designed to create differentiated therapies through changes to factors such as dosage, formulation, delivery method or product presentation, with the potential to support early-stage licensing and partnership opportunities.

    NXP002 is Nuformix’s lead preclinical programme and is being developed as a potential inhaled therapy for idiopathic pulmonary fibrosis, progressive pulmonary fibrosis and other progressive fibrosing interstitial lung diseases.

    By targeting new indications and differentiated product profiles, Nuformix aims to establish commercially attractive development opportunities that can be advanced through partnerships with larger pharmaceutical and biotechnology companies.
  • Ithaca Energy Raises 2026 Dividend Guidance After Record North Sea Production

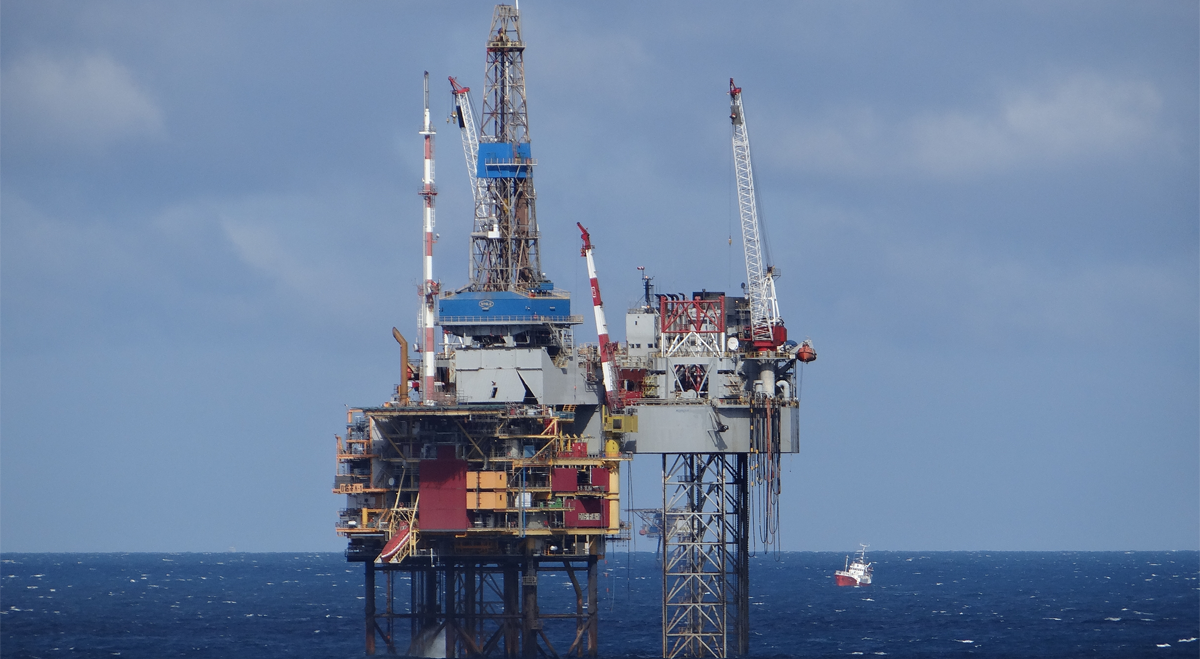
    Ithaca Energy Raises 2026 Dividend Guidance After Record North Sea Production

    Ithaca Energy (LSE:ITH) delivered a strong first half of 2026, with record second-quarter production, robust cash generation and progress across its North Sea development portfolio prompting the company to increase its dividend guidance for the year.

    Production reached a record 131 thousand barrels of oil equivalent per day (kboe/d) during the second quarter, taking the first-half average to 128 kboe/d. The performance allowed management to reaffirm its full-year production guidance, while production efficiency across operated assets reached 90%.

    Financial performance was supported by the higher production levels, with adjusted EBITDAX exceeding $1.1 billion during the first half. Ithaca also reported lower leverage and an improved outlook for operating costs, strengthening its capacity to return cash to shareholders while continuing to invest in future projects.

    Against this backdrop, the board increased its 2026 dividend guidance to between $500 million and $530 million and declared an interim distribution of $255 million. The higher shareholder return reflects confidence in the group’s cash-generating capacity and financial position.

    Operationally, Ithaca maintained a strong safety performance while keeping its emissions intensity below the wider basin average. Progress was also made across several developments intended to support future production and extend the life of its North Sea portfolio.

    Rosebank, one of the company’s most significant projects, has entered the final execution phase, with first oil targeted for 2027. Other developments including Cambo, Fotla, Tornado and Cygnus are also progressing through important stages, providing a pipeline of potential organic growth opportunities.

    Ithaca has complemented this development programme with selective transactions designed to strengthen its position in key production hubs. These include a farm-in to Tobermory and a farm-down of Fotla, moves intended to establish commercial partnerships and enhance the company’s position in the West of Shetland gas region.

    Financial and operational flexibility has also been strengthened through a rig-sharing agreement with Harbour Energy and the issuance of additional senior notes. Available liquidity increased to $1.9 billion while leverage remained low, providing resources to advance Ithaca’s project portfolio while maintaining shareholder distributions.

    Ithaca’s broader investment outlook is underpinned by strong operating profitability and free cash flow, although earnings volatility and less conservative balance-sheet trends remain potential risks. Near-term technical indicators are also relatively weak. Valuation presents a mixed picture, with the high dividend yield providing support while the price-to-earnings multiple remains relatively elevated for a cyclical oil and gas producer.

    More About Ithaca Energy PLC

    Ithaca Energy PLC is a UK North Sea oil and gas producer with a portfolio spanning both operated and non-operated assets across the UK Continental Shelf.

    Its production portfolio includes a combination of oil and natural gas assets, while its development strategy is focused on extending production and cash generation through projects including Rosebank, Cambo and other opportunities in the West of Shetland region.

    The company combines organic investment with targeted mergers, acquisitions and portfolio transactions, seeking to allocate capital towards projects capable of generating attractive returns. Its strategy is centred on maintaining sustainable production, developing its resource base and generating cash flow that can support both future investment and shareholder distributions.

  • Oxford Nanopore Cuts First-Half Losses as It Targets More Than $700 Million Revenue by 2030

    Oxford Nanopore Cuts First-Half Losses as It Targets More Than $700 Million Revenue by 2030

    Oxford Nanopore (LSE:ONT) delivered higher first-half revenue and a substantial reduction in adjusted losses during 2026, as stronger demand across key end markets and improved cost discipline supported progress towards profitability.

    Revenue for the six months reached £116.7 million, representing growth of 12.3% on a constant-currency basis. Performance was supported by particularly strong demand across the EMEAI region and from BioPharma and Clinical customers, helping offset weaker conditions in APAC, most notably China.

    Profitability metrics also improved significantly. Gross margin increased by 400 basis points to 62.2%, while the adjusted EBITDA loss narrowed to £22.1 million, less than half the level recorded in the comparable period. The improvement reflected a combination of higher gross profit and tighter management of the group’s cost base.

    Oxford Nanopore’s PromethION sequencing platform was a major contributor to growth, with the company reporting solid demand across Clinical, BioPharma, Industrial and Research applications. The performance reinforces management’s strategy of directing resources towards markets where its sequencing technology has the strongest commercial potential.

    As part of this approach, Oxford Nanopore has established four strategic priorities designed to sharpen its market focus, accelerate adoption and improve operational execution. The group continues to target adjusted EBITDA breakeven in FY27, followed by positive free cash flow in FY28.

    Looking further ahead, management has introduced a new objective of generating more than $700 million in annual revenue by 2030. Achieving this target would represent an important milestone towards Oxford Nanopore’s longer-term ambition of developing into a business with revenue exceeding $1 billion.

    Commercial activity has continued since the end of the reporting period. Oxford Nanopore signed a global cross-licensing agreement with a diagnostics company that is expected to generate licensing payments, committed product purchases and recurring royalties.

    The company also entered an agreement to integrate its sequencing technology into MyOme’s rare disease platform, potentially expanding the application of nanopore sequencing within clinical diagnostics. New executive appointments across medical and marketing leadership further demonstrate Oxford Nanopore’s efforts to strengthen its regulatory, commercial and market-development capabilities.

    Oxford Nanopore’s investment outlook is improving as revenue grows, gross margins expand and losses narrow, supported by cost controls and constructive FY26 guidance. However, substantial operating losses and continued cash consumption remain important risks. Technical indicators are mixed, with the shares below key longer-term moving averages, while valuation remains constrained by negative earnings and the absence of a dividend yield.

    More About Oxford Nanopore Technologies PLC

    Oxford Nanopore Technologies plc is a London-listed molecular sensing and sequencing technology company serving BioPharma, clinical, research and industrial markets worldwide.

    Its nanopore-based technology enables real-time analysis of DNA and RNA across a range of applications. The company’s portfolio includes its PromethION high-throughput sequencing systems and portable MinION devices, alongside associated consumables, software and services.

    Oxford Nanopore operates internationally across EMEAI, the Americas and APAC, with its strategy increasingly focused on expanding adoption in higher-growth Clinical and BioPharma applications while continuing to serve established research customers.

    The company is also pursuing opportunities in regulated and industrial markets, supported by a strategy centred on customer-led growth, targeted innovation and greater operational discipline. Its goal of exceeding $700 million in revenue by 2030 represents a key step towards its longer-term ambition of building a business generating more than $1 billion in annual sales.

  • Rockfire Resources Reports Further High-Grade Intercepts as Molaoi Feasibility Work Advances

    Rockfire Resources Reports Further High-Grade Intercepts as Molaoi Feasibility Work Advances

    Rockfire Resources (LSE:ROCK) has reported additional high-grade mineralisation from diamond drilling at its wholly owned Molaoi zinc deposit in Greece, as the explorer continues technical studies aimed at advancing the project towards potential development.

    Results from drill hole HMO-020 included multiple intersections containing zinc and germanium. Rockfire expects the new drilling data to contribute towards its targeted increase in Indicated Resource tonnage, providing further geological information as the company works to improve confidence in the Molaoi resource.

    Alongside drilling, Rockfire is progressing feasibility-related studies across several areas of the project. Comminution and point load testing is being undertaken to assess the characteristics of the mineralisation and help determine appropriate equipment requirements for potential future mining and processing operations.

    Metallurgical work is also evaluating different processing routes, including flotation and zinc smelting, as well as options for producing a marketable germanium product. Germanium is considered a critical mineral and represents an additional potential source of value alongside Molaoi’s zinc, lead and silver mineralisation.

    The latest work demonstrates continued technical progress at Molaoi during the summer period despite a temporary pause in drilling. Results from the ongoing studies are expected to contribute to the broader feasibility assessment and help Rockfire determine the most suitable development and processing strategy for the deposit.

    From an investment perspective, Rockfire’s outlook remains constrained by its pre-revenue status, continuing net losses and persistent negative free cash flow, including a substantial operating cash outflow during 2025. Technical indicators provide some support, with the shares trading above shorter-term moving averages, although they remain below the 200-day moving average and MACD is slightly negative. Valuation also remains difficult to assess favourably given negative earnings and the absence of a dividend yield.

    More About Rockfire Resources PLC

    Rockfire Resources plc is a London-listed mineral exploration company with interests in gold, base metals and critical minerals.

    Its flagship asset is the 100%-owned Molaoi deposit in Greece, which contains high-grade zinc, lead, silver and germanium mineralisation. The company is carrying out drilling and technical studies designed to increase confidence in the resource and evaluate potential pathways towards future development.

    Rockfire also holds a portfolio of gold, copper and silver projects in Queensland, Australia, including the Plateau and Marengo prospects. These assets are subject to farm-in arrangements with ASX-listed partners, allowing exploration activity to continue while Rockfire concentrates resources on advancing Molaoi.

  • Ultimate Products Grows Proprietary Brand Sales as FY26 Revenue Declines

    Ultimate Products Grows Proprietary Brand Sales as FY26 Revenue Declines

    Ultimate Products (LSE:ULTP) reported lower overall revenue for FY26 as cautious consumer spending and a deliberate reduction in non-core clearance activity weighed on sales, although growth across its proprietary brands provided a more positive signal for its longer-term strategy.

    Unaudited revenue for the year stood at £144.9 million, representing a 3.5% decline from the previous year. In contrast, revenue generated by the group’s proprietary brands increased 5.3% to £128.4 million, highlighting continued progress in shifting the sales mix towards owned labels and strengthening brand equity.

    Adjusted EBITDA for FY26 was £10.0 million, while gross margin eased to 22.6%. Operating costs remained broadly stable despite the group absorbing approximately £760,000 of restructuring charges associated with the transformation of its commercial function.

    Ultimate Products also made progress in reducing its borrowings, with net bank debt falling to £8.6 million. This brought leverage down to 0.9 times adjusted EBITDA, giving the group greater financial flexibility as it continues to invest in its operational and commercial capabilities.

    Trading showed signs of stabilisation during the second half, when revenue was broadly unchanged year-on-year compared with the decline recorded during the first six months. The performance points to greater resilience despite continued pressure across the wider general merchandise market.

    Looking ahead, the board expects FY27 trading to be broadly comparable with FY26 as cautious consumer demand and geopolitical uncertainty continue to affect the operating environment. Nevertheless, management believes investments being made across the business should strengthen its ability to capture growth opportunities when market conditions improve.

    A central part of this strategy is increasing market share and building the value of core proprietary brands including Salter and Beldray. The continued expansion of these brands could help improve the quality of Ultimate Products’ revenue mix while reducing its reliance on lower-value third-party clearance activity.

    The broader investment outlook is supported by improved free cash flow and lower leverage, while a moderate price-to-earnings valuation and strong dividend yield provide additional support. Technical indicators are also constructive following an upward share-price trend, although overbought readings on the RSI and Stochastic indicators suggest some risk of near-term consolidation.

    More About Ultimate Products plc

    Ultimate Products plc is a UK homeware group that owns consumer brands including Salter and Beldray. Market research indicates that almost 80% of UK households own at least one product from the group’s portfolio.

    The company sells small domestic appliances, housewares, laundry and audio products through more than 300 retailers across over 30 countries. Its products are also available through the group’s own digital channels and major third-party e-commerce platforms.

    Founded in 1997 and headquartered in Oldham, Greater Manchester, Ultimate Products operates design, sales, marketing and warehousing facilities across two sites and maintains international showrooms in Guangzhou and Paris.

    The group employs more than 300 people and operates a substantial Graduate Development Scheme. It also holds exclusive licensing agreements covering the Russell Hobbs trademark for cookware and laundry products, excluding electrical appliances.

  • INPP Agrees £58 Million-Plus UK Schools PPP Sale as Capital Recycling Continues

    INPP Agrees £58 Million-Plus UK Schools PPP Sale as Capital Recycling Continues

    International Public Partnerships (LSE:INPP) has agreed to dispose of its interests in nine UK public-private partnership projects covering 15 schools across four London boroughs, continuing its strategy of recycling capital from mature infrastructure investments.

    The assets, which form part of the Building Schools for the Future programme, are being sold to a separately managed account managed by InfraRed Capital Partners on behalf of a pension fund. INPP expects the transaction to generate gross proceeds of more than £58 million.

    Importantly for shareholders, the disposal has been agreed at a premium to INPP’s most recently published valuation of the investments. The pricing provides further evidence of the underlying value within the company’s infrastructure portfolio and its ability to realise mature assets at attractive levels.

    The latest transaction takes INPP’s total realisations over the past three years to more than £440 million, representing approximately 17% of its portfolio. All of these disposals have been completed at or above the corresponding published valuations.

    Alongside these sales, INPP has committed to reinvest approximately £480 million over the same period. These investments have a combined internal rate of return above the portfolio discount rate, supporting the company’s objective of recycling capital into opportunities capable of generating accretive long-term returns.

    The strategy allows INPP to monetise established investments while redeploying proceeds into new infrastructure opportunities offering potentially stronger risk-adjusted returns. Management believes the combination of successful disposals and disciplined reinvestment demonstrates both the quality of the existing portfolio and the effectiveness of its capital allocation approach.

    INPP’s broader investment outlook is supported by its debt-free balance sheet and improving cash generation, while a relatively low price-to-earnings multiple and high dividend yield provide additional valuation support. Earnings have, however, varied between reporting periods. Technical indicators also suggest the shares are currently overbought following an upward trend, potentially increasing the risk of shorter-term volatility.

    More About International Public Partnerships

    International Public Partnerships Limited is a listed infrastructure investment company focused on public infrastructure assets and businesses designed to meet long-term societal and environmental requirements.

    Its diversified portfolio includes more than 130 investments spanning utility and energy transmission infrastructure, transport, education, healthcare, justice and digital infrastructure.

    INPP has investments across the UK, Europe, Australia, New Zealand and North America. Its strategy is centred on generating sustainable long-term income and capital growth for shareholders while investing in infrastructure that provides essential public services.

  • discoverIE Expands Indian Manufacturing Capacity With New Bangalore Facility

    discoverIE Expands Indian Manufacturing Capacity With New Bangalore Facility

    discoverIE Group plc (LSE:DSCV) has significantly increased its manufacturing capabilities in India with the opening of a new 9,000-square-metre facility in Jigani, Bangalore, as the electronics specialist responds to growing demand across electrification, renewable energy and infrastructure markets.

    The new facility forms part of discoverIE’s Noratel business and more than doubles the footprint of its existing Bangalore operation while providing approximately three times the previous production capacity. The site will manufacture specialised power transformers and magnetic components used across a range of electrification applications.

    India represents an important domestic market for the operation, with around 70% of existing Bangalore production currently supplied to customers within the country. Demand is being supported particularly by investment in renewable energy and infrastructure, while the additional capacity will also give discoverIE greater scope to pursue export opportunities.

    The expansion is intended to accommodate increasing order volumes and recently secured projects while providing capacity for further growth. It also follows the UK-India Free Trade Agreement coming into force in July 2026, providing a supportive backdrop for discoverIE as it increases its manufacturing presence in one of its targeted growth markets.

    The investment reinforces the group’s strategy of concentrating resources on structurally attractive sectors benefiting from electrification and sustainability trends. By increasing local manufacturing capacity, discoverIE is positioned to serve expanding Indian demand while also using the Bangalore operation as a platform for international sales.

    From an investment perspective, discoverIE’s outlook is supported by steady financial performance, improving earnings and consistently positive free cash flow. Higher leverage remains a consideration, while technical indicators point to a strong share-price uptrend but also suggest overbought conditions that could create near-term volatility. Valuation represents another potential constraint, with a relatively high price-to-earnings multiple and only a modest dividend yield.

    More About discoverIE Group plc

    discoverIE Group plc is a FTSE 250-listed international designer and manufacturer of customised electronic components for industrial applications.

    Operating through its Magnetics & Controls and Sensing & Connectivity divisions, the group develops application-specific components for original equipment manufacturers across markets including medical technology, transportation electrification, renewable energy, security and industrial automation.

    Its business model is built around long-term customer relationships and customised products that can generate recurring revenue throughout the lifecycle of customers’ applications. discoverIE operates across 21 countries and focuses on markets benefiting from long-term structural trends including electrification, automation and sustainability.

  • Angling Direct Posts Resilient Half-Year Growth as UK Store Network Expands

    Angling Direct Posts Resilient Half-Year Growth as UK Store Network Expands

    Angling Direct plc (LSE:ANG) delivered further growth during the first half of its financial year despite challenging consumer conditions and weather-related disruption, as the fishing tackle retailer continued to expand its UK store network and strengthen its digital proposition.

    Revenue for the six months ended 31 July 2026 increased 5.1% to £56.4 million, supported by a 6.9% rise in UK sales. Like-for-like UK revenue grew 2.9%, demonstrating continued underlying demand despite pressures affecting the wider retail environment.

    Performance in Europe remained more challenging, with sales declining as Angling Direct maintained its focus on generating profitable business rather than pursuing revenue growth at the expense of margins. The group continues to take a disciplined approach to its European operations as it works towards improving their longer-term contribution.

    Cash generation remained strong during the period, helping lift net cash to £14.5 million. The healthy cash position has allowed Angling Direct to continue its share buyback programme while retaining financial flexibility to support investment in future growth. Trading remains in line with market expectations, with management maintaining confidence in the group’s medium-term targets and longer-term market opportunity.

    Expansion of the physical store network also continued, with new locations opening in Crawley, Kettering and Gloucester. These additions increased Angling Direct’s estate to 60 stores across England and Wales and further extended its reach within the domestic fishing tackle market.

    Customer engagement through the MyAD loyalty programme also strengthened, with membership exceeding 696,000 subscribers. The growing customer base complements the retailer’s stores, e-commerce operations and mobile apps, reinforcing its omni-channel strategy and providing additional opportunities to build market share.

    Angling Direct’s wider investment outlook is supported by improving revenue and profitability alongside controlled leverage. Free cash flow has been less consistent, however, while technical indicators remain a notable weakness, with the shares trading below major moving averages and momentum signals remaining subdued. Valuation appears broadly neutral based on its price-to-earnings multiple, with no dividend data providing additional support.

    More About Angling Direct plc

    Angling Direct plc is a UK omni-channel specialist fishing tackle retailer offering more than 25,000 products from established third-party brands as well as its own Advanta and Discover ranges.

    Headquartered in Norfolk, the company operates 60 stores across England and Wales alongside its e-commerce platform and dedicated mobile applications. It also has a developing European operation supported by a distribution facility in the Netherlands.

    Angling Direct serves both experienced anglers and people taking up fishing for the first time. Its strategy combines physical retail expansion with digital development, customer loyalty initiatives and sustainability programmes designed to strengthen engagement and support long-term growth in the recreational angling market.

  • Trainline to Cooperate With CMA Investigation Into UK Booking Fee Transparency

    Trainline to Cooperate With CMA Investigation Into UK Booking Fee Transparency

    Trainline plc (LSE:TRN) has said it will cooperate fully with the UK Competition and Markets Authority after the regulator launched an investigation into the way certain fees are displayed during the company’s UK booking process.

    The CMA is examining Trainline’s practices under the Digital Markets, Competition and Consumers Act 2024, with the investigation focused on how some charges are presented to customers as they progress through the booking journey.

    Trainline said it has already been in discussions with the regulator for several months and has begun making improvements to the way fees are communicated on its platform. The company intends to continue working with the CMA as the investigation proceeds, with an emphasis on ensuring its booking experience remains transparent and compliant with UK consumer protection requirements.

    The review is particularly relevant given the importance of pricing clarity and customer trust to Trainline’s digital business model. Any changes resulting from the investigation could affect how the company presents booking costs to UK customers, while its response to the regulatory scrutiny may also influence its reputation and relationship with users.

    Trainline’s broader investment outlook is supported by strong profitability and improving operating leverage, alongside positive technical trends and a relatively undemanding price-to-earnings valuation. These strengths are partly offset by higher balance-sheet leverage and recent variability in free cash flow, which could increase financial risk if trading conditions deteriorate.

    More About Trainline

    Trainline plc is an independent digital rail and coach travel platform that enables millions of customers to search for and purchase tickets through its website and mobile app.

    The platform brings together routes, fares and timetable information from numerous rail and coach operators across Europe, allowing travellers to compare options, book journeys and manage tickets through a single digital service.

    Trainline has established a significant digital presence across European travel markets, with its app carrying a 4.9-star rating. Convenience, pricing transparency and ease of use are central to its customer proposition, making the presentation of booking fees an important element of both the user experience and the company’s regulatory obligations.

  • Tap Global Seeks U.S. Investor Access Through OTC Market Quotation

    Tap Global Seeks U.S. Investor Access Through OTC Market Quotation

    Tap Global Group plc (LSE:TAP) has applied for its existing ordinary shares to be cross-traded on the OTCID Basic Market operated by OTC Markets in the United States, as the digital finance company looks to increase its visibility and accessibility among North American investors.

    The proposed OTCID quotation would complement Tap Global’s primary listing on London’s AIM market rather than involve the issuance of a new class of shares. If approved, the arrangement could make it easier for U.S.-based investors to trade the company’s shares while potentially widening its shareholder base and improving secondary-market liquidity.

    Management sees the move as an opportunity to strengthen Tap Global’s profile in the U.S., a major global centre for digital assets and cryptocurrency investment. Greater exposure to North American capital markets could also support the company’s broader international ambitions as it expands its regulated digital finance operations and develops its payments and crypto services.

    Admission to the OTCID Basic Market remains subject to the necessary regulatory and market approvals, meaning there is currently no certainty that the application will result in a quotation.

    Tap Global operates at the intersection of conventional financial services and digital assets, with more than 400,000 registered customers and a Mastercard-supported card that enables users to convert cryptocurrency into fiat currency for everyday spending.

    More About Tap Global Group plc

    Tap Global Group plc is a digital finance business offering traditional payment and cryptocurrency services through its Tap app for individual and business customers. Its platform provides access to more than 70 cryptocurrencies and connects with several major exchanges.

    The company uses proprietary AI-powered middleware to identify pricing and execution opportunities across connected trading venues, with the aim of providing users with competitive real-time cryptocurrency transactions.

    Tap Global Limited, the group’s European operation, became the first cryptocurrency fintech to secure Mastercard approval in Europe, allowing customers to convert digital assets into fiat currency and use the Tap card at millions of merchants worldwide.

    The group operates under distributed ledger technology regulation in Gibraltar and also holds virtual asset service provider registration in Bulgaria as it positions its European operations within the evolving regulatory framework for digital assets, including the EU’s MiCA regime.